September 30, 2021

12:52 pm

SPX has lost its grip on its support at the 100-day Movig Average at 4345.00 and is now entering the panic phase of the market.  Gamma is seriously negative below 4400.00 and may only beget more selling.  Can a bounce happen here?  Yes, but may be limited by today’s peak at 4382.00.   Once beneath 4300.00 the cascade begins.

ZeroHedge remarks, “After another energetic session of buying in Asia, US futures began fading as Europe opened and accelerated lower as US opened…
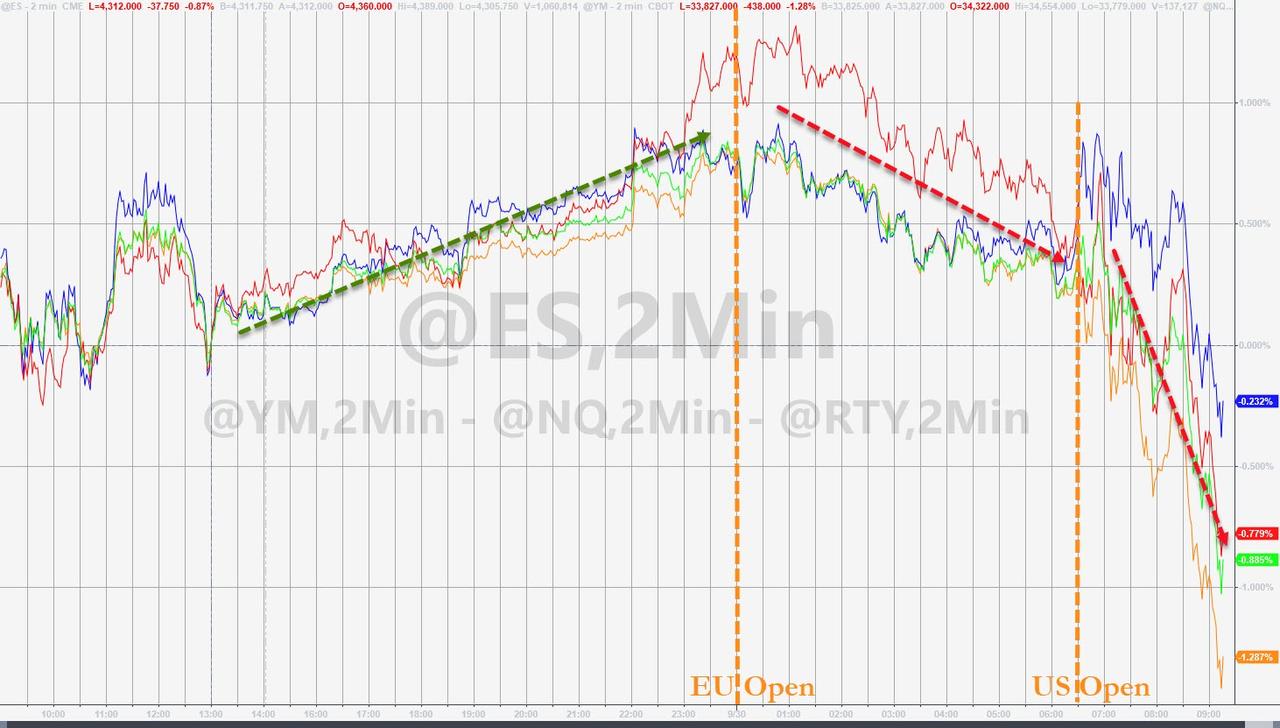
Critically, this push lower has sent all the major US equity indices below key technical supports:

  • S&P broke below its 100DMA
  • Nasdaq broke below its 100DMA
  • Dow broke below its 100DM
  • Russell 2000 broke below its 200DMA”


ZeroHedge also notes, “Another day, another rollercoaster for stocks as futures were bid overnight until the European open and selling started…
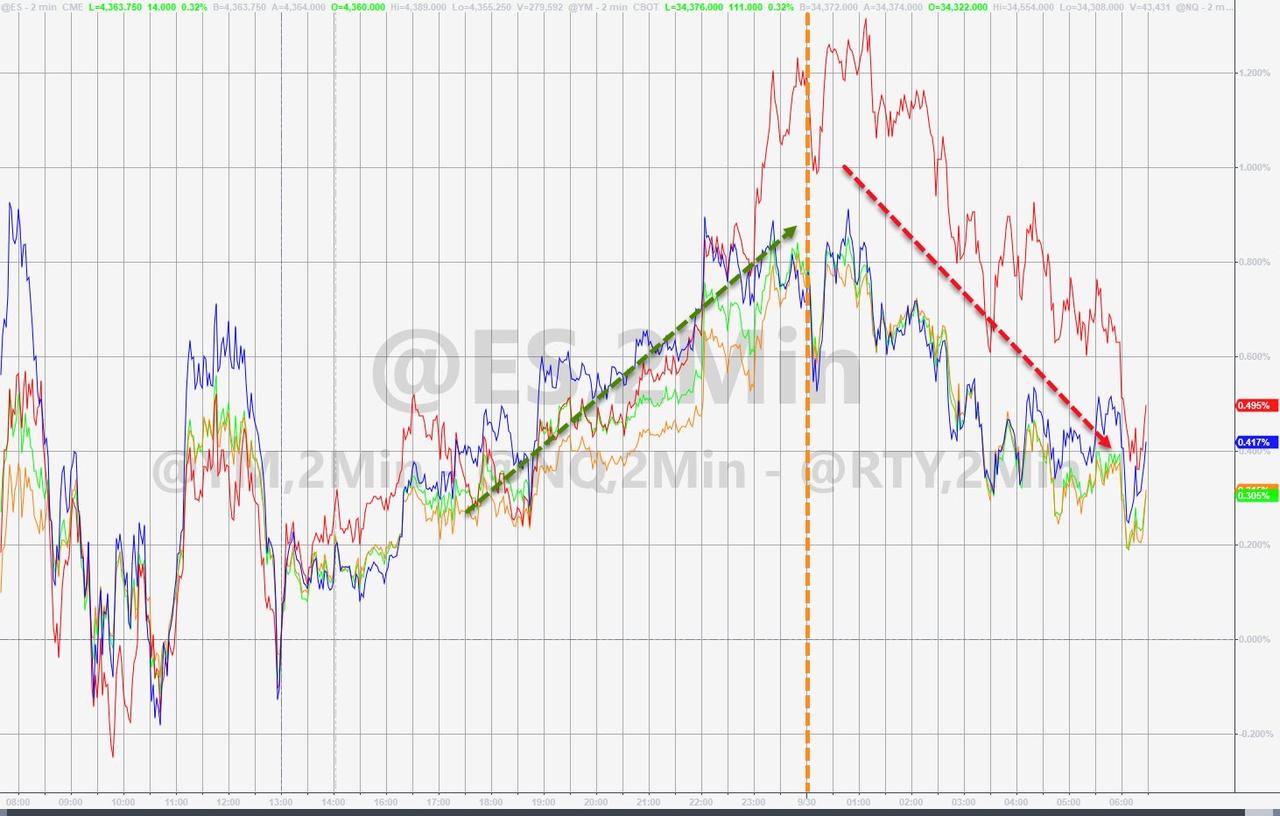
But notably, Treasury yields have “stabilized” in a narrow range after their explosive surge higher recently. Nomura’s Charlie McElligott suggests that it does feel like the worst of the “short Gamma” dynamics clearly seen in both UST futs and ED$ futs early this week are now in a “cleaner” place…
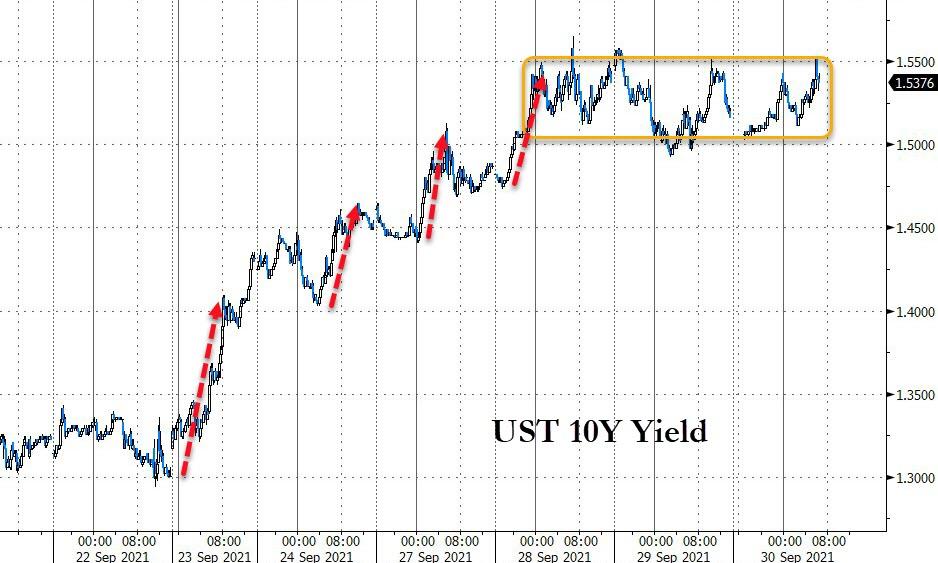
But, the Nomura strategist suggests that today’s potential fireworks inside the Equities space will more than likely be generated from the absolutely mongo-sized qtrly SPX Put Spread Collar that is being rolled, where paper needs to buy 44,600 SPX SepQ 4430 Call (on the cover) to buy the DecQ 3490 / 4140 Put Spread while selling the DecQ 4515 Call x 44,600 – the trade will lift the Street on ~$3.1B in Gamma and SELL 14.5mm in Vega.”


6:50 am

Good Morning!

I am due for an early morninr appointment, so this session will be brief.

SPX futures are higher this morning, but could not make resistance at 4400.00.  The 38.2% Fib retracement is at 4391.05 and it appears that SPX may stay clenched at that level.  The reason?  Open interest at 4400.00 in today’s expiring put contracts is 19,663  versus open interest in today’s (expiring) calls is  11,149.  An accident here may bring a cascade of selling as open interest in puts outnumber calls quite a way down from 4400.00.

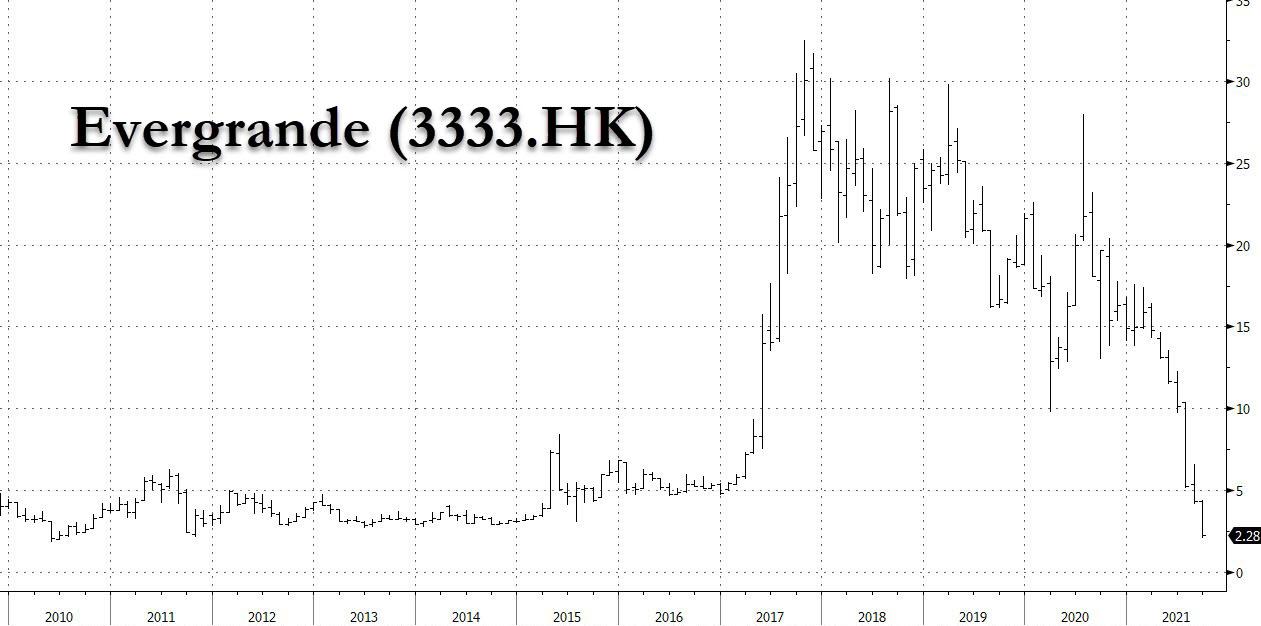
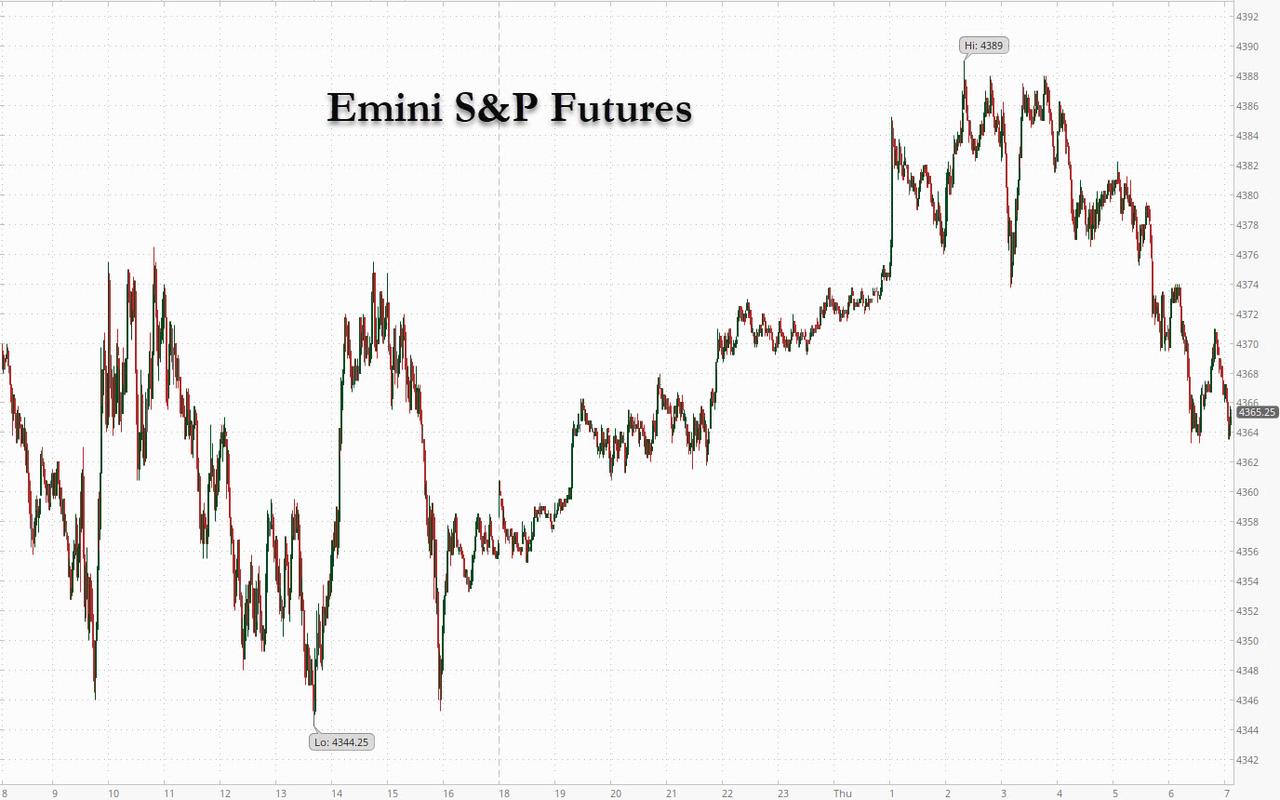
ZeroHedge reports, “US equity futures faded an overnight rally on the last day of September as lingering global-growth risks underscored by China’s official manufacturing PMI contracted for the first time since Feb 2020 as widely expected offset a debt-ceiling deal in Washington and central-bank assurances about transitory inflation. The deal to extend government funding removes one uncertainty from the minds of investors, amid China risks and concerns over Federal Reserve tapering. Comments from Fed Chair Powell and ECB head Christine Lagarde about inflation being transitory rather than permanent also helped sentiment, even if nobody actually believes them any more.In China, authorities told bankers to help local governments support the property market and homebuyers, signaling concern at the economic fallout from the debt crisis at China Evergrande

As of 7:15am ET, S&P futures were up 18 points ot 0.44%, trimming an earlier gain of 0.9%. Dow eminis were up 135 or 0.4% and Nasdaq futs rose 0.43%. 10Y TSY yields were higher, rising as high as 1.54% and last seen at 1.5289%; the US Dollar erased earlier losses and was unchanged.”
 

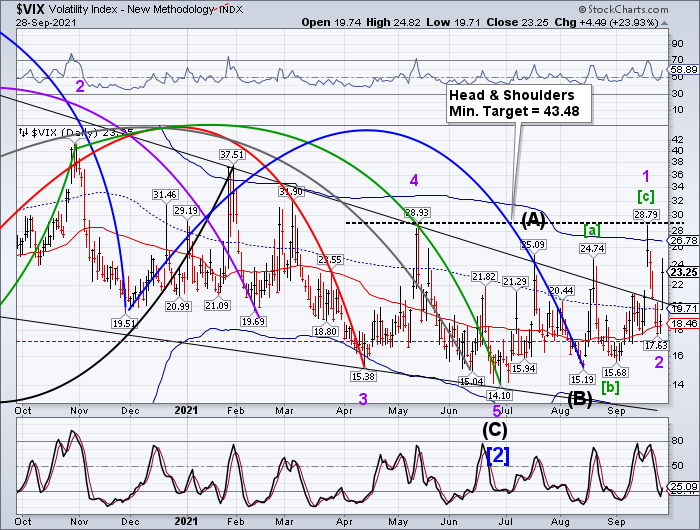
VIX futures have pulled back to the trendline at 20.50 but have recovered back nearer the close.

The NYSE Hi-Lo Index closed at -11.00, giving no support for a further rally.


NDX futures remain range-bound within yesterday’s trading range as a battle rages over which options get paid.  QQQs (closing price: 359.28) are especially sensitive, since opoen interest in today’s expiring put contracts is 15,980 versus open interest of 7,325 call contracts.  The Max Pain zone is 361.00, which is still slightly tilted toward puts.  Calls dominate at 362.00 and above.  Today’s options expiration is a minefield where the dealers dare not trod either to the right or the left.

CharlesHughSmith opines, “The banquet of consequences is being served, and risk-off crashes are, like revenge, best served cold.

The ideal setup for a crash is a consensus that a crash is impossible–in other words, just like the present: sure, there are carefully measured murmurings about a “correction” but nobody with anything to lose in the way of public credibility is calling for an honest-to-goodness crash, a real crash, not a wimpy, limp-wristed dip that will immediately be bought.

What I’m calling for is a rip your face off, weeping bitter tears over the grave of the speculative wealth that you thought was forever crash. All those buying the dip because the Fed will never let the market go down will be crushed like scurrying cockroaches and all those trying to rotate into the next hot sector or asset class will also be crushed like scurrying cockroaches because when the Everything Bubble pops, well, everything pops. There is no shelter in a risk-off cascade.

The crash is coming as a result of multiple mutually reinforcing dynamics, the first being that no “serious person” believes a crash is possible, much less imminent. In no particular order, here are a raft of other causally consequential triggers of a cascading market crash:”


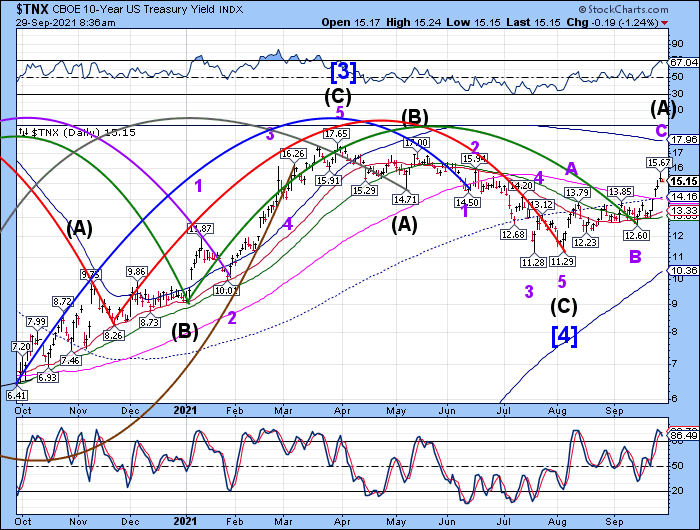
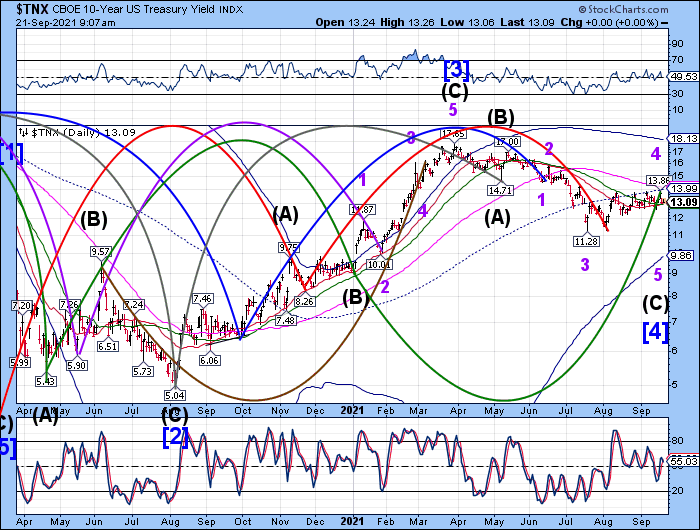
TNX is on the rise again with a high at 15.57.  With only two weeks to go to its next Master Cycle (high), a breakout may be underway.   The Cycles Model suggests a possible rally of the current Master Cycle to the October 18 drop dead date.  The decline in stocks may extend beyond that date, as the damage of higher rates may be realized.

ZeroHedge observes, “Now that Sen. Joe Manchin has denounced his own party’s multi-trillion plan to expand the social safety net as “the definition of fiscal insanity,” we can be virtually assured that the entire Democratic domestic agenda has essentially been left dead in the water, since the progressive Left won’t agree to back the Dems’ “bipartisan” infrastructure plan via reconciliation without first passing the larger spending package through both chambers.
Whatever the outcome, Manchin’s statement suggests it will likely take weeks and months – not days – for President Biden and the leadership to negotiate the votes – if indeed they can ever resolve the intractable divide within their own party, which has largely taken the form of aggressive leftists in the House (exemplified by the AOC-led “squad”) vs. a pair of moderates (Manchin and Arizona’s Kyrsten Sinema) in the Senate.”

That’s fortunate, in a sense, since it means Chuck Schumer and Nancy Pelosi will have no choice but to focus on the arguably more pressing priorities: keeping the government funded while raising the debt ceiling, ideally before Treasury Secretary Janet Yellen’s “drop-dead” date of Oct. 18.


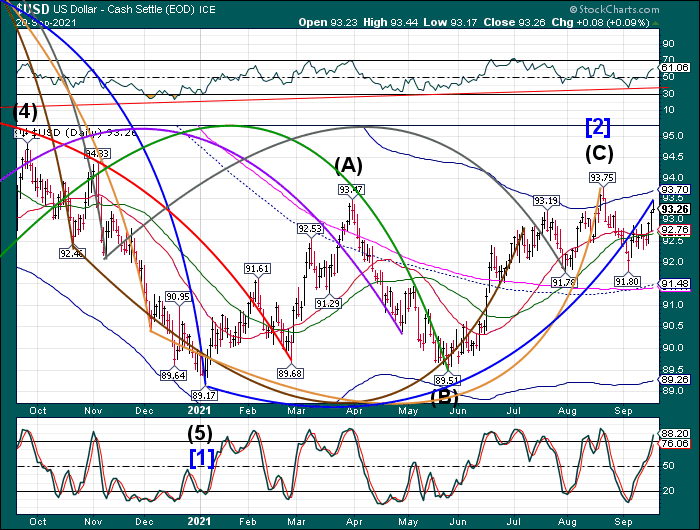
USD futures are consolidating this morning after yesterday’s breakout rally on day 266 of the Master Cycle.    Normally we would anticipate a two-to-three week correction after the Master Cycle, but due to the extended older Master Cycle, we may only see an abbreviated correction before moving higher.  The new Master Cycle may not end until mid-November.


Posted in Published | Comments Off on September 30, 2021

September 29, 2021

11:40 am

While SPX hugs its Max Pain zone at 4375.00 to 4400.00, NDX is also walking a tightrope in the options arena.  QQQ (359.95) is the best example where a slip may plunge it into the abyss.  At the 360.00 strike, open interest in put contracs is 13,020 vs calls at 6580.  Above that level is positive, while beneath 360.00 becomes deeply negative.  Don’t be surprised to see these Max Pain levels maintained through the end of the day.  However, accidents do happen.  Meanwhile the NYSE Hi-Lo Index is at -4.00 and the NDX Hi-Lo Index is at -40.00.

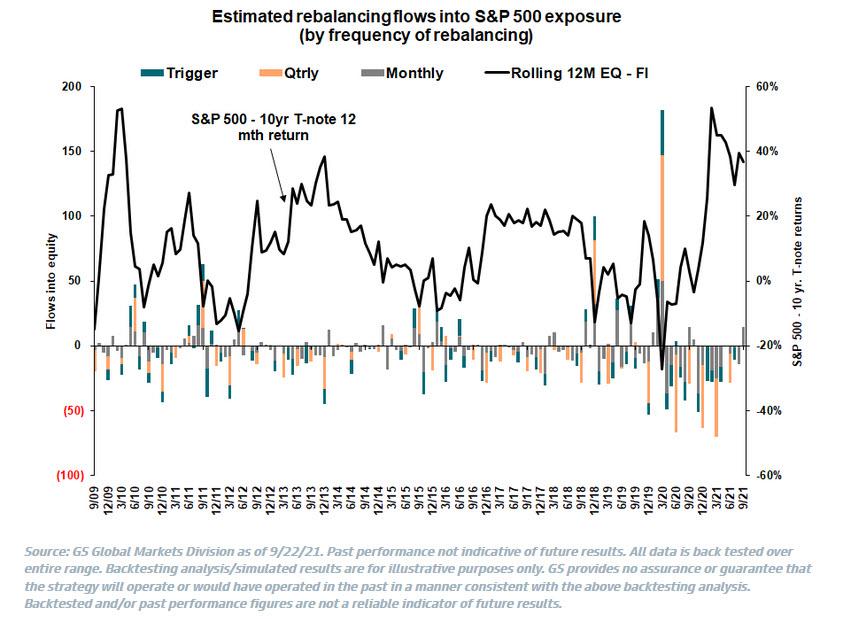
The dealers are hoping that pensions will ante up at the table for quarter-end rebalancing.

ZeroHedge observes, “With month- and quarter-end on deck, Goldman’s theoretical, “model-based” estimates are for a net $14 billion of US equities to buy from US pensions given the moves in equities and bonds over the month and quarter.

How does this stack up vs history? According to Goldman’s Gillian Hood, this ranks in the 36th percentile amongst all buy and sell estimates in absolute dollar value over the past three years. In absolute terms, this falls below the three year average absolute dollar value of $26bn worth of equities to be rebalanced.”


7:55 am

Good Morning!

SPX futures appear to have completed Wave [c] of 2 this morning just shy of the 38.2% retracement level at 4391.05.   It is unclear whether another attempt at retracement may be made at the open.  While futures are still positive, negative gamma prevails for today’s options expiration.  While open interest in today’s options remains neutral at 4400.00, it becomes progressively more negative the further south that prices go.  Open interest in puts outnumber calls by 1750 at 4350.00 and outnumber calls by over 2000 at 4325.00.  Puts have the upper hand by 5000 contracts at 4300.00.

In an event that largely goes unnoticed, the La Palma Volcano is having increasing tremors and quakes along with stronger eruptions that may further destabilize the volcano.  The implication is a possible collapse into the Atlantic with knock-on results for the East Coast of the United States.

ZeroHedge reports, “U.S. index futures rebounded on Tuesday from Monday’s stagflation-fear driven rout as an increase in Treasury yields abated and the greenback dropped from a 10 month high while Brent crude dropped from a 3 year high of $80/barrel after API showed a surprise stockpile build across all products.

One day after one of Wall Street’s worst selloff of this year which saw the S&P’s biggest one-day drop since May, dip buyers made yet another another triumphal return to global markets, with Nasdaq 100 futures climbing 130 points or 0.9% after the tech-heavy index tumbled the most since March on Tuesday as U.S. Treasury yields rose on tapering and stagflationconcerns. S&P 500 futures rose 28 points or 0.6% after the underlying gauge also slumped amid mounting concern over the debt-ceiling impasse in Washington.”


The NYSE Hi-Lo Index closed at 0.00 yesterday, confirming the sell signal.  Internals are extremely weak.  Unfortunately, the live quotes during market hours include ETFs that double and triple count individual stocks.  They are removed in the after hours to obtain the correct count, which we see this morning.


VIX futures pulled back to 21.45 this morning but has recovered somewhat as I write.  The Cycles Model indicates an increase in trending strength going into the weekend and lasting through mid week.  This implies a breakout above the neckline and the follow-through rally that may match the June 2020 high at 44.44 over the next week.


TNX futures pulled back to 14.94 in the overnight session.  The Cycles Model suggest a bit more of a pullback by the weekend, then a period of strength during the first half of next week.  This may lead to a Master Cycle high by mid-October.

ZeroHedge observes, “Maybe the market has been too hypnotized by the promise of cheap free money flowing forever, or maybe it remembers how the Fed stepped in last March to ensure that nobody lost any money and thus nobody wants to sell this time, or maybe it is just too used to buying every single dip so that news of the Fed’s taper actually sent stocks higher. But all that may soon change, because as Deutsche Bank’s Jim Reid calculates in terms of global central bank hikes exceeding cuts, we are now at the highest differential for a decade on a rolling 12-month basis.

In other words, we are now entering the most aggressively global hiking cycle in a decade.”


USD futures not only broke out above its previous high at 93.75 but also broke above its Cycle Top resistance at 93.83 this morning.  This is lending credence to the notion that the Master Cycle may be extending until the end of the week, in a period of strength.  A probable target for this rally may be 94.79, the equivalent of the June 2020 high and the 38.2% retracement level for the decline which extended from January 2020 to February 12, 2021 (12.9 months).


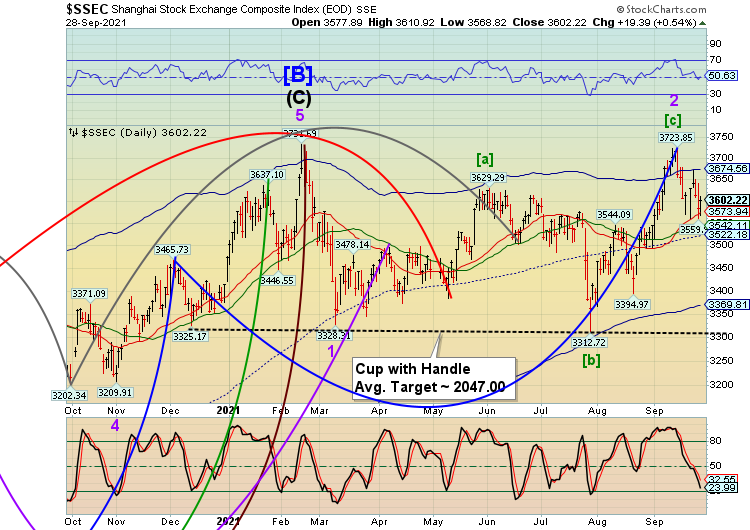
The Sanghai Composite Index fell to to a low of 3518.04 during today’s session before it bounced back toward the 50-day Moving Average at 3542.11.  It is on a confirmed sell signal with a projected decline that may last until the second week of October.  The high in September missed the February high by 8 points, attesting to the great lengths the Bank of China went through to keep stocks elevated, to no avail.

ZeroHedge reports, “China’s cash-strapped property giant Evergrande was on the verge of defaulting on a second bond on Wednesday despite agreeing to settle debt with a Chinese bank in a $1.5 billion stake divestment deal, a move which sent Evergrande’s worthless stock squeezing higher, now up 50% from a week ago.

Early on Wednesday, Evergrande said in an exchange filing that it would sell a 9.99 billion yuan ($1.5 billion) stake it owns in Shengjing Bank – its most valuable financial unit – to a state-owned asset management company. The bank, one of Evergrande’s main lenders, demanded all net proceeds from the sale go towards settling the developer’s debts with Shengjing.

“The company’s liquidity issue has adversely affected Shengjing Bank in a material way,” Evergrande said in the statement, adding that the introduction of the purchaser — state-owned Shenyang Shengjing Finance Investment Group Co. — will help to stabilize the bank’s operations.”


Posted in Published | 7 Comments

September 28, 2021 Pray for our Country

2:55 pm

SPX bounced from the 100-day MovingAverage at 4341.00 at 1:00 pm.  It appears that the bounce may be ending shortly.  The 38.2% retracement level is at 4391.05, if it can make it.  This is no time for taking short profits.  There may yet be another two weeks to go on the dowside.


7:40 am

Good Morning!

The projected final probe to 4475.00 did not materialize.  In fact, there appears to be a truncated Wave [v] of C in the final hour which remained within the Triangle boundaries.

This morning the SPX futures tumbled to 4398.40, giving up the 50-day Moving Average support at 4438.03.  Welcome to phase 2 of the decline.  Should this event mark the halfway point of the decline, we may now see a panic phase lasting until October 20.

The La Palma Volcano has opened new vents and the lava flow is more liquid than before, suggesting a deeper source than what was earlier witnessed.  Vents are now cutting across the cone that may destabilize it.  The U.S. Tsunami Warning System does not see this as a threat.

ZeroHedge reports, “For much of 2021, a vocal contingent of market bulls had claimed that there is no way the broader market could sell off as long as the gigacap tech “general” refused to drop. Well, it looks like that day is finally upon us because this morning US equity futures are sliding again, continuing their Monday drop as yields from the US to Germany again, the 10Y TSY rising as high as 1.55%, driven to an extent by Fed tapering fears but mostly by the surge in oil which has pushed Brent above $80, the highest price since late 2018. The dollar gained amid the deteriorating global supply crunch from oil to semiconductors.

The surge in oil sparked a new round of stagflation fears, sending Nasdaq futures down 240 points or 1.3% as the yield on the benchmark 10-year U.S. Treasury climbed sharply. S&P 500 and Dow Jones futures also retreated, with spoos sliding below 4,400 as to a session low of 4,390.”


VIX futures soared to 21.45 this morning, above the mid-Cycle resistance at 19.73 and the trendline just above 20.00.  This may be the beginning of a period of strength that may intensify through next week.  Another period of strength may develop during the week of October 18.


The NYSE Hi-Lo Index made a new high yesterday, as expected, but closed beneath the 50-da Moving Average at 77.46.  That appears to be the end of the retracement with new lows developing through October 15.


USD futures rose to 93.68, breaking out above the existing high in what may be a running correction.  This may lead to a recalibration of the Wave structure.


TNX resumed its climb as it continues toward its next Master cycle high due in mid-October.  This is starting to look ugly and may be the cause of a couple of Federal Reserve presidents resignations.

More resignations may come as the realization that the Fed does not control rates becomes apparent.  In addition, when will the dealer banks start to rebel as the Fed loosens the reverse repo spigots to accomodate the banks having to guarantee the purchase of unsold treasury paper?

ZeroHedge reports, “In the aftermath of the ugly 2Y auction at 1130am, moments ago the Treasury followed up with its second coupon auction of the day when it sold $61 billion in 5Y notes. And unlike the “gruesome” tailing 2Y sale, this time demand was far more solid.

Printing at a high yield of 0.990%, the auction stopped through the When Issued 0.994% by 0.4bps, even if it too was the highest yield since February 2020 and decidedly above last month’s 0.831% now that the Fed’s tapering is officially in play.

The Bid to Cover came in at 2.37, which unlike the near record plunge in the 2Y BTC was actually a modest improvement to last month’s 2.35, and also printed right on top of the six-auction average.

The Internals were soggier, with Indirects taking down just 54.3%, below the recent average of 59.8%, and the lowest since March 2020 when foreign buyers took down just 52.1%. And with Directs taking down 20.2% higher than the 17.1% recent average, Dealers were left holding 25.5%, or the most since February.”


NDX futures made a morning low of 14939.40 as it lost the 50-day Moving Average support at 15191.70.  While the NDX all-time high was made on September 7, five days later than the SPX, it may be playing catch-up in the decline.

ZeroHedge remarks, “Below is what ZH premium clients received yesterday as one of our TME thematic emails. On rates, tech and volatility. Don’t miss the next one, sign up here.

Was this the bounce?

Here we are with major index futs reversing from overnight highs. Both SPX and NASDAQ futs reversed right on short term resistance levels.

We would love to see how this behaves should we dip once more from here.

While Spoos is above the 50 day, NASDAQ is right on it…watch those yields moving higher again.

Rates matter…especially for tech. Then you have the power crunch in China to consider as well. Hard to produce all those iPhones if Beijing is tightening the energy consumption policy…”


The GSCI Ag Index has broken out above Intermediate-term (the higher) resistance at 413.39 and is clearly on a buy signal.   For those who want to be long in a short world, this is the place to be.  The Cycles Model indicates that this rally may last through mid-December.  Not only do we have drought in the Western States, but also snow in Argentina and frost in Brazil and flooding in Europe and China.  Can it get any worse?
ZeroHedge answers that question, “Millions of Britons could face a “national shortage” of turkeys, toys, and trees this Christmas due to a lack of skilled European employees following Brexit, according to the chair of a farming association.

The Road Haulage Association (RHA) last month said the UK is facing a shortage of around 100,000 HGV drivers, which along with Brexit, has been further exacerbated by people leaving the industry as well as the pandemic, which halted driver training and testing for nearly a year.

As a result, food supply chains have been drastically disrupted, leading to shortages across some UK supermarket shelves.

Kate Martin of the Traditional Farm Fresh Turkey Association (TFTA) told the PA news agency that Christmas could see a “national shortage” of turkeys on the UK’s supermarket shelves, driven by the declining supply of skilled European workers.”


Posted in Published | 1 Comment

September 27, 2021

12:10 pm

SPX is nearing the end of a probable Triangle formation.  Once complete, it may rise to 4475.00 to 4485.00.    Triangles often precede the final Wave in a series.  Standby for a final push higher this afternoon.  Once SPX reaches 4475.00, it may be appropriate to add short positions.  The rally may delay until the open tomorrow, but I wouldn’t count on it.


7:30 am

Good Morning!

SPX futures have lingered near the top of its retracement, suggesting more to come.  The next resistance is at the top of Wave B at 4486.87. Shoould SPX decline beneath 4430.00, it may be an indicator of the resumption of the decline.

Today completes market day 17 (17.2) of the Master Cycle which topped out on September 2.  Wave (C) may be equal to Waves (A) and (B) in time, stretching the decline to October 21-22.  Most analysts and hedge funds are still positive, viewing the surge of new money as a positive sign, rather than as lemmings racing toward the cliff.

The NYSE Hi-Lo Index closed at 34.00 on Friday.  It may go higher today in a Trading Cycle high but a reversal may be right around the corner.

ZeroHedge reports, “US index futures, European markets and Asian stocks all turned negative during the overnight session, surrendering earlier gains as investors turned increasingly concerned about China’s looming slowdown – and outright contraction – amid a global stagflationary energy crunch, which sent 10Y TSY yields just shy of 1.50% this morning following a Goldman upgrade in its Brent price target to $90 late on Sunday. At 745 a.m. ET, S&P 500 e-minis were down 4.75 points, or 0.1% after rising as much as 0.6%, Nasdaq 100 e-minis were down 83 points, or 0.54% and Dow e-minis were up 80 points, or 0.23%. The euro slipped as Germany looked set for months of complex coalition talks.”


VIX futures are higher this morning, reaching a high of 19.08.  It may be aiming for the mid-Cycle resistance at 19.76 as it prepares for much higher levels.


TNX is challenging the 15.00 level this morning.  The next resistance is the Cycle Top at 17.99, giving ample room to move higher.  The next Master Cycle high may occur during the week of October 11.

ZeroHedge observes, “Following the hotter than expected durable goods headline data, 30Y Yields briefly spiked up to almost 2.05%, but fell back on the core data – although they are still holding above 2.00%

Source: Bloomberg

This has been a key level to watch in recent months…”


USD futures are higher this morning, but beneath the Master Cycle high at 93.53.  Should there be a breakout, we may see USD make a considerable advance.  Resistance lies at the Cycle Toop at 93.78.


Posted in Published | 2 Comments

September 24, 2021 Pray for our Country

12;00 PM

For those of your who may not be aware, the La Palma Volcano has intensified its eruptions and opened up yet another vent.  The threat of a tsunami intensifies, although the NOAA?National Weather Service has not recognized it as a threat.  I have informed family members on the East Coast to seek higher ground.   Should a collapse occur, we would only have 6-9 hours warning.

I am leaving town for the weekend.  Be back on Monday morning.


8:15 am

Good Morning!

SPX futures are down over .5% already.  Welcome to the second half of the decline (in time).  The retracement is showing Wave (2) behavior, so I will leave the current labels.  This Master Cycle is scheduled to land on October 15, but that day being options expiration, may extend several more days due to the bearish gamma.  The list of catalysts has not gone away, although China is rising to the forefront.

9:44 am Note that SPX may yet rise to its Wave B high at 4486.87 as liquidity is still being poured into the markets.  Should new lows be made beneath the 50-day Moving Average at 4437.30  in the next hour, that event goes away.

ZeroHedge observes, “US futures and European stocks fell amid ongoing nerves over the Evergrande default, while cryptocurrency-linked stocks tumbled after the Chinese central bank said such transactions are illegal. Sovereign bond yields fluctuated after an earlier selloff fueled by the prospect of tighter monetary policy. At 745am ET, S&P 500 e-minis were down 19.5 points, or 0.43%, Nasdaq 100 e-minis were down 88.75 points, or 0.58% and Dow e-minis were down 112 points, or 0.33%.”


VIX futures rose to a mornig high of 20.37, challenging the trendline and promises more to come.

Nomura notes that the rally carried big volumes, “Yet despite the return of such scattered bullish flows, McElligott notes that there remains much angst in the Vol space (Skew still roofed as downside demand remaining extreme), versus still “pervasive skepticism” towards broad Equities upside index / ETF / sectors / industries (Call Skew still nuked).”


The NYSE Hi-Lo closed beneath its 50-day Moving Average at 77.68, leaving some doubt about the “RECOVERY.”  Today’s (and future) action may show the real weakness in the NYSE.  Monday’s low was day 256 of the old Master Cycle.  The new Master Cycle is due to bottom on October 15.


TNX gapped above bot the 100-day and mid-Cycle resistance at 14.07, putting it on a buy signal and launching a new rally that may reach the Cycle Top in Wave (A) and 20.00 or higher in Wave (C) of [5].  The spike in volatility today may be a delayed reaction to the rising yields as noted yeterday.

The Cycles Model clearly marked the bottom of Wave [4] on September 15 even though I missed it due to a truncation in which Wave 5 was higher than Wave 3.  The chart is now corrected.

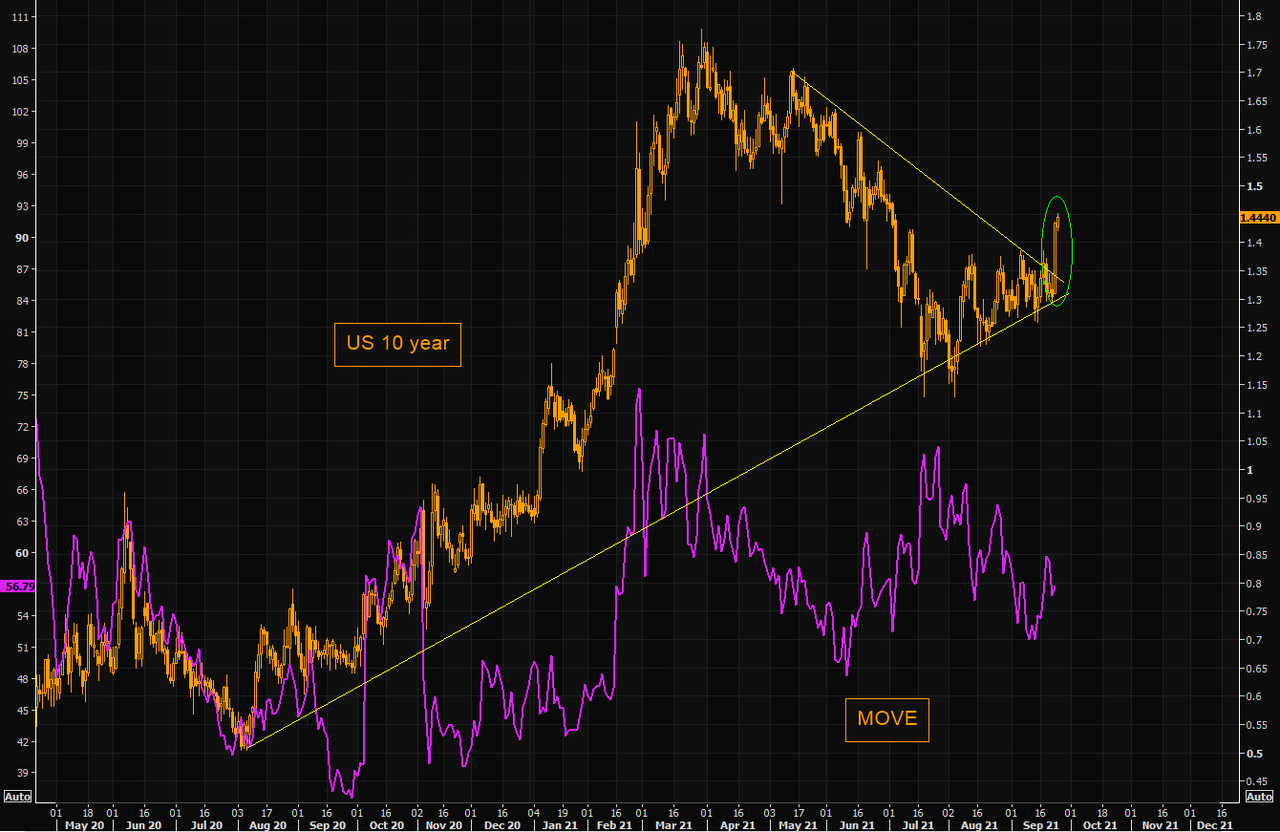
ZeroHedge notes, “While the US 10 year put in a huge candle yesterday, breaking above big resistance levels, bond vol (MOVE) was steady.

The early year squeeze in yields was accompanied with surging bond vol (which Fed dislikes).

The move in yields is so far just one day, but let’s see how bond vol reacts should we get a continuation of the squeeze move.

Source: Refinitiv

A rapid spike in yields was previously considered a market risk

SPX had its first >+1% day since July 23. A confluence of factors contributed to the risk-on behavior. VIX falling below 20 also helped. Inflation L/S best factor, 6M Momo worst. Cyclicals over Defensives. SVX beat SGX by 47bps but Barra Growth outperformed Value. The 10Y closed at 1.423% vs. 1.301% yesterday; the large move in bonds was not met with increased Equity Vol. A rapid spike in yields was previously considered a market risk.”


USD futures appear to be consolidating beneath yesterday’s Master Cycle high.  Although Wave (C) is roughly equivalent to Wave (A),  the correction can go considerably higher, from 98.30, the 61.8% retracemment value, to as high as the Weekly Cycle Top near 100.00.  But  first, there should be a retracementat least down to mid-Cycle support at 91.51.


GKX crossed above its mid-Cycle support/resistance at 407.56 and is testing its 50-day Moving Average at 412.09.  A rally above that level puts i into a buy signal that may last through mid-December.  You can see that Wave [2] appears to be in a modified running correction, where Wave (C) ends higher than Wave (A).  This is very bullish,  since the technicals imply a possible doubling in food prices.  It may also cause a lot of suffering among low income families, who are already having trouble putting food on the table.

ZeroHedge reports, “UK politicians are in utter panic as similarities to the 1970s-style “winter of discontent” of shortages and socio-economic distress could rear its ugly head in the coming months, according to Reuters.

A significant driver in what could very well be a hellacious winter for Brits is soaring natural gas and electricity prices that have already disrupted segments of the UK economy and sent shockwaves through energy markets, chemical producers, and the food industry, among others. Compound this all with labor shortages thanks to Brexit, and the dire situation may worsen.

Some Brits who remember the past worry a winter of discontent could be imminent. Many are facing extraordinary high power bills and sharp food inflation that are eating away at wages, along with shortages of goods at supermarkets.”

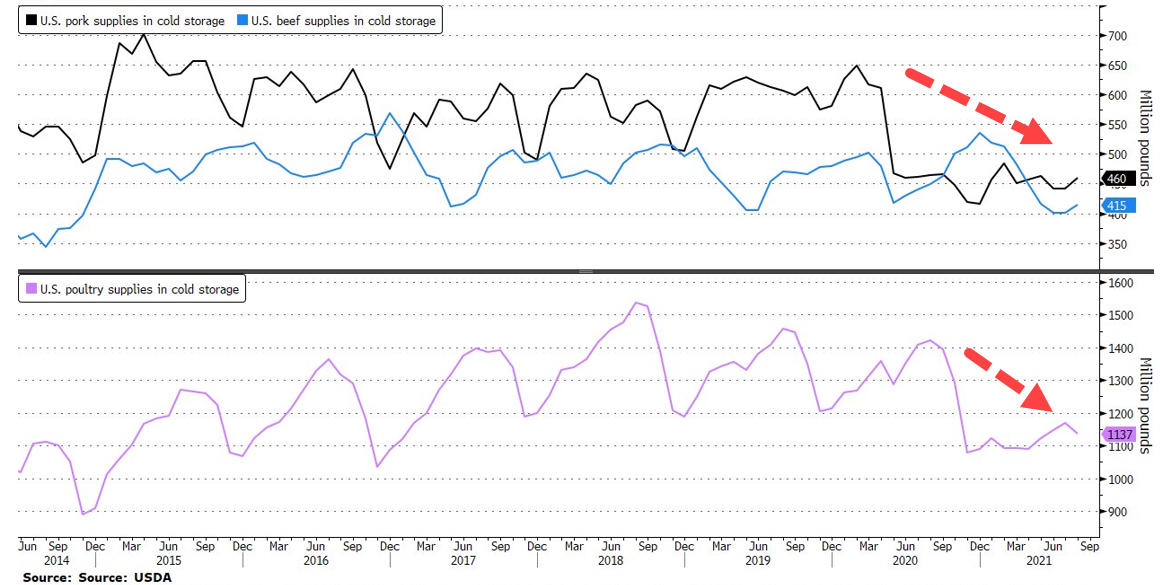
Closer to home, ZeroHedge observes, “Beef, pork, and chicken in US cold storage warehouses have yet to recover from pandemic lows and could continue to support higher prices.

New United States Department of Agriculture (USDA) data shows beef reserves dropped 7.7% from a year ago in August, poultry supplies fell 20%, and pork plunged 44% to their lowest levels since 2017, according to Bloomberg.

Jim Sullivan, commercial director for Stable USA, said low meat inventories would suggest meat prices will stay elevated.

“Prices remain very elevated compared to seasonal expectations,” Sullivan said. “


Posted in Published | Comments Off on September 24, 2021 Pray for our Country

September 23, 2021, Pray for Our Country

10:45 am

I had originally labelled the Waves at 1-2-3.  However, the overlap and dimensions suggest otherwise.  I have concluded that we are either in a (1)-(2) or (A)-(B) formation in a Leading Diagonal Wave (1).  The rally is now approaching the 61.8% Fib retracement of a Wave (1) at 4454.91 and the mid-Cycle resistance at 4466.67.  Should it go higher, I would be inclined to re-label this as an (A)-(B) of a Primary Cycle Ending Diagnal Wave [1].  It may be complete in the next hour in the first example.  Otherwise,  it may not finish until the end of the day.

ZeroHedge observes, “A sudden wave of panic-buying took over the stonk markets this morning after they faded overnight gains.

This sent the majors up to critical technical levels.

The S&P is back at its 50DMA (having bounced off its 100DMA)…


7:50 am

SPX futures have receded back down to the 61.8% Fibonacci retracement level at 4417.74 after testing the 50-day Moving Average at 4433.92 overnight.  It appears that the gap may remain open in the cash market.  SPX has just completed 14 days of what may be a 30 (market) day decline.  All of the components for a panic decline are in place.  1) SPX has tested and failed the 50-day Moving Average.  2)  There is a potential for a government shutdown and default by the end of October.  3)  Evergrande may meet its demise in the next few days.  4)  Investors are losing faith in the Fed.  5) Nuclear sabre rattling by China.  And…6) The LaPalma Volcano has become ashier with an SO2 clound hovering over southern Europe and North Africa.  While the media downplays the probability of a megatsunami, the opening of new vents suggest a possible increase of volcanic activity.

ZeroHedge reports, “US index futures jumped overnight even as the Fed confirmed that a November tapering was now guaranteed and would be completed by mid-2022 with one rate hike now on deck, while maintaining the possibility to extend stimulus if necessitated by the economy. Sentiment got an additional boost from a strong showing of Evergrande stock – which closed up 17% – during the Chinese session, which peaked just after Bloomberg reported that China told Evergrande to avoid a near-term dollar bond default and which suggested that the “government wants to avoid an imminent collapse of the developer” however that quickly reversed when the WSJ reported, just one hour later, that China was making preparations for Evergrande’s demise, and although that hammered stocks, the report explicitly noted that a worst-case scenario for Evergrande would mean a partial or full nationalization as “local-level government agencies and state-owned enterprises have been instructed to step in only at the last minute should Evergrande fail to manage its affairs in an orderly fashion.”

In other words, both reports are bullish: either foreign creditors are made whole (no default) as per BBG or the situation deteriorates and Evergrande is nationalized (“SOEs step in”) as per WSJ.”


VIX futures dove to 19.06 this morning, as it develops the right shoulder of a revised Head & Shoulders pattern.  The Cycles Model suggests a probable turnaround in today’s activities.


Wednesday’s NYSE Hi-Lo Index remained beneath the 50-day Moving Average despite the ramp.  The NYSE is weak, with less than 1.5% of its companies making new 52-week highs.  The Cycles Model suggests something dramatic may be happening in the Hi-Lo Index in the next two days.


TNX remains above the 50-day Moving Average at 12.92 but beneath the mis-Cycle resistance at 14.04.   TNX is in a “trading band squeeze” which indicates a probable test of the Cycle Bottom at 10.02 (Wave [4]) before a dramatic rally above the trading bands in Wave [5].  The test of the Cycle Bottom may occur by mid-October.


Posted in Published | 2 Comments

September 22, 2021

8:05 am

Good Morning!

SPX futures rose to an overnight high of 4388.50, cchallenging the Cycle Bottom resistance at 4376.39, but staying beneath yesterday’s high of 4394.87.  This is meant to work off the oversold condition so that Stochastics reach 50.00 before going back down.  Yesterday’s gap is likely to remain unfilled.

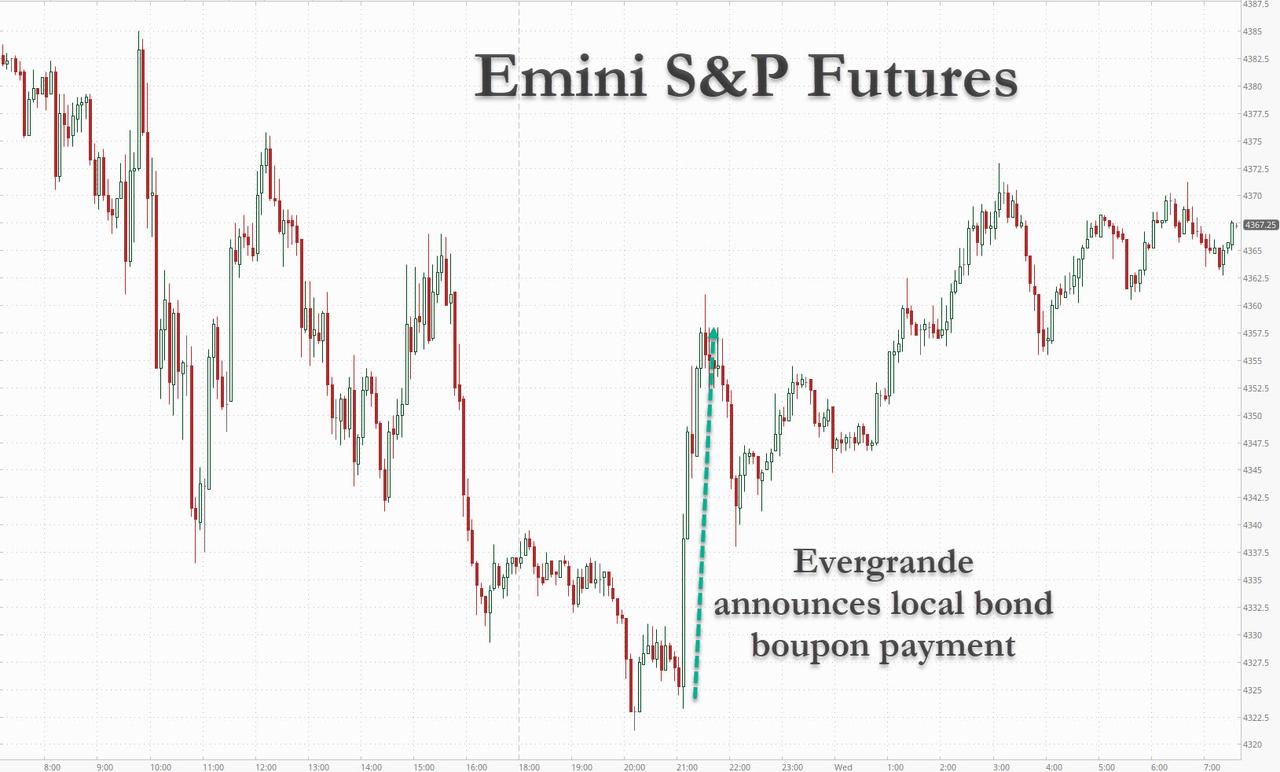
ZeroHedge reports, “Despite today’s looming hawkish FOMC meeting in which Powell is widely expected to unveil that tapering is set to begin as soon as November and where the Fed’s dot plot may signal one rate hike in 2022, futures climbed as investor concerns over China’s Evergrande eased after the property developer negotiated a domestic bond payment deal. Commodities rallied while the dollar was steady.

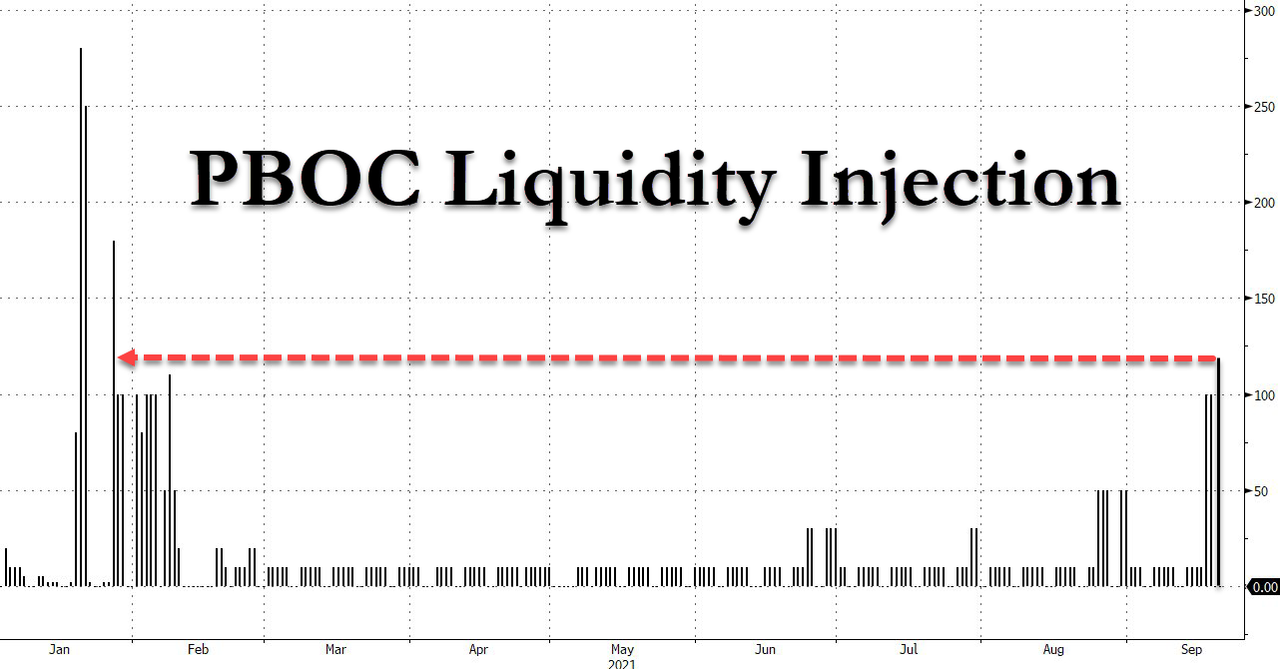
Contracts on the S&P 500 and Nasdaq 100 flipped from losses to gains as China’s central bank boosted liquidity when it injected a gross 120BN in yuan, the most since January…

… and investors mulled a vaguely-worded statement from the troubled developer about an interest payment.  S&P 500 E-minis were up 23.0 points, or 0.53%, at 7:30 a.m. ET. Dow E-minis were up 199 points, or 0.60%, and Nasdaq 100 E-minis were up 44.00 points, or 0.29%.”


VIX futures declined to 22.66, still within yesterday’s trading range.  The Cycles Model suggests a double spike in strength starting today and lasting through the weekend.  In addition, there appears to be another double spike during the week of October 4.  This week’s spike appears capable of meeting or exceeding the Head & Shoulders minimum target of 36.08.


The NYSE Hi-Lo Index closed at -8.00 yesterday, maintaining the sell signal.  Today is day 258 in the Master Cycle, so there is a possibility of an attempt to ramp the number of new 52-week highs.   However, the probability of the VIX ramping by the end of the week suggests otherwise.


TNX appears slightly positive this morning, especially since it is above the 50-day Moving Average at 12.52.  However, a break of that support may send TNX down to the Cycle Bottom at 9.94 in the next three weeks.

ZeroHedge reports, “As expected, in a surprisingly close, 220-211 vote, the Democratic-controlled House passed a bill that would suspend the U.S. debt ceiling into December 2022 and provide the government funding to operate past Sept, 30 if it passes the Senate which it most likely won’t because Senate Republicans, even RINOs such as Mitt Romney, have vowed to block it over the debt limit provision which Democrats purposefully included in the provision.”

ZeroHedge remarks, “Senate Minority Leader Mitch McConnell (R-Ky.) and Sen. Richard Shelby (R-Ala.) on Sept. 21 offered a competing short-term government funding bill, just as House Democrats passed a stopgap measure that also suspends the debt limit until after the 2022 election.

The bill from McConnell and Shelby does not include a debt ceiling suspension, as Republicans have urged Democrats—the majority party—to raise the $28.4 trillion debt ceiling themselves through reconciliation, a special parliamentary procedure that would expedite the passage of a budgetary measure through the Senate.

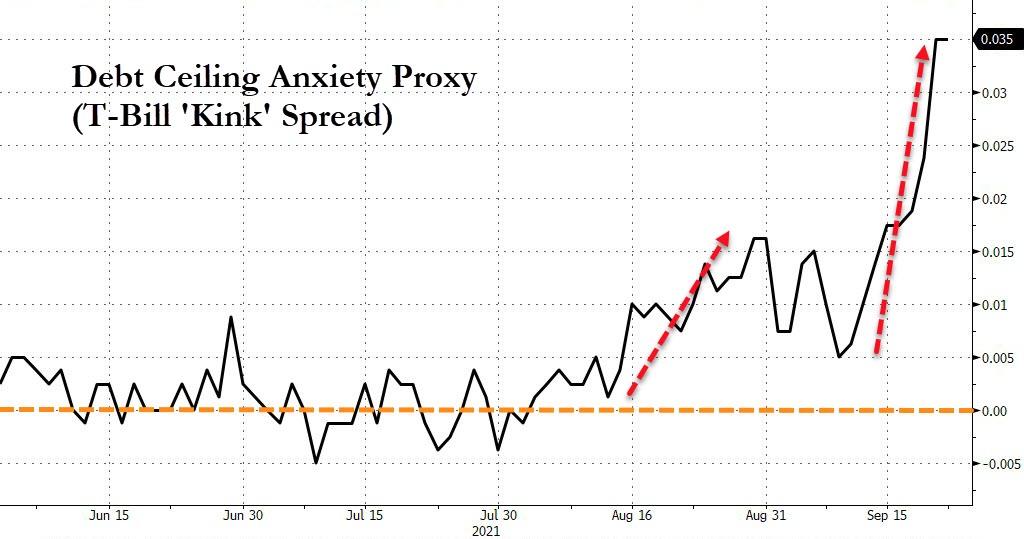
[ZH: The introduction of the bill likely increases the probability of no Senate deal, and for now, the market is tending to agree as debt ceiling anxiety has not eased at all]”


USD futures consolidated in range during the overnight session.  From a Cycles vantage, this week appears to be calm, but next week may be a barn burner as the decline gets underway.  The Cycles Model suggests the decline may last through mid-November before any relief appears.


The Hang Seng (Hong Kong) Index rallied last night on news of the Evergrande repieve.  But the decline may not be over, despite the bounce.  The Cycles Model suggests the decline may continue until October 10, over two weeks from now.  Undoubtedly, there will be more bounces along the way as the index is oversold.  However, the recovery may not take place until the Master Cycle is complete.

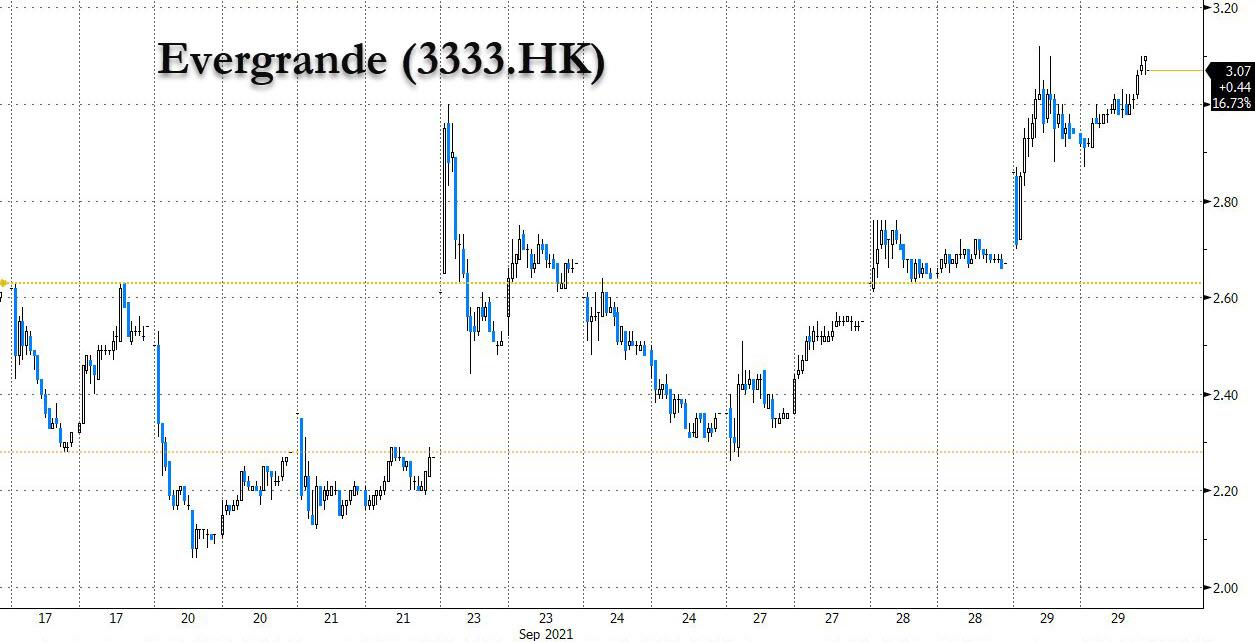
ZeroHedge observes, “After two anxiety-filled days during which China was on holiday and traders hammered Hong Kong trader property stocks, contagion fears arising from China Evergrande Group’s debt crisis moderated overnight with mainland stocks declining less than expected on Wednesday as they resumed trading, after Evergrande’s onshore unit unveiled vaguely worded plans to pay interest due Thursday on a yuan bond, while leaving the fate of a $83.5 million offshore bond coupon payment in limbo.

As we noted earlier, in its filing to the Shenzhen Stock Exchange, the Evergrande unit said that it reached an agreement with yuan bondholders on an interest payment due Sept. 23. It, “has been resolved via negotiations off the clearing house,” but didn’t specify how much or when it will pay the 232m yuan coupon at stake.

The language is potentially ominous because under normal circumstances, Chinese bond issuers would simply transfer money to a clearing house to complete payments. The “off-the-clearing house” approach usually means direct but delayed, or partial payment to bondholders. There could even be a lower interest rate involved. In short: it’s one way to avoid being called a defaulter.

As Bloomberg’s Shen Hong wrote, “Evergrande may have secured bondholders’ agreement with a payment extension or at least succeeded in asking them not to act until compromise is reached, even as it misses the payment due Thursday.”

ZeroHedge further comments, ““If that’s true, we are very close to the China Syndrome ”

Evergrande’s imminent default is rocking markets – but few believe the collapse of a Chinese property developer could trigger a global financial crisis. What if Evergrande is just a symptom of a deeper malaise within the Chinese economy and its political/business structures? Maybe there is more at stake than we realise? What if Emperor Xi decides he needs a distraction?

Amid this week’s market turbulence, and the overnight headlines, Evergrande dominates thinking this morning. The early headlines say the risk is “easing”. Don’t be fooled. S&P are on the wires saying it’s on the brink of default and is unlikely to get govt support. It’s Asia’s largest junk-bond issuer. Anyone for the last few choc-ices then?

The market view on the coming Evergrande “event” is mixed. Some analysts are dismissing it as an internal “China event”, others reckon there may be some systemic risk but one Government can easily address. There is some speculation about “lessons” to be learnt… There are even China supporters who reckon its proof of robust China capitalism – the right to fail is a positive!

I’ve got a darker perspective.

The massive shifts we’ve seen in China’s political/business public persona over the past few years have been variously ascribed: a reaction to Trump’s protectionism, China taking its place as a leading nation, Xi flexing his military muscle, and now a clampdown on divisive wealthy businesses to promote common prosperity.”


Posted in Published | Comments Off on September 22, 2021

September 21, 2021

10:05 am

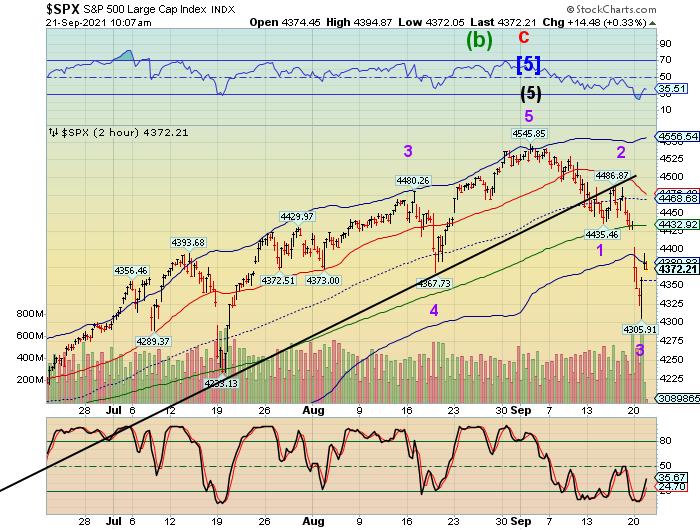
SPX rallied to the 50% Fib retracement level at 4396.49 in the first hour, a bit higher than expected.  The Cycles Model suggests the decline resumes this morning with the largest panic-selling episode just ahead.  While we may see yet another attempt at 4400.00, the worst of the retracement may be over.

ZeroHedge observes, “A dramatic rebound in stocks – off the S&P’s 100DMA – has prompted many commission-rakers and asset-gatherers today to call the end of the Evergrande event and signal the all-clear to new highs.

So what happened? What changed?

Nomura’s Charlie McElligott explains that there is simply no way to overstate the power of the “reflexive vol sellers” into another spike, as this “sell the rip (in vol)” = “buy the dip (in stocks),” particularly as it related Put sellers either directionally shorting “rich” vols yday…and “long sellers” who monetized their downside hedges by the close (a lot of that being 1d SPY Puts from Retail “day traders” which doesn’t show in OI), creating $Delta to buy and again self-fulfilling yet another “turnaround Tuesday”

Critically, that Delta buying in the late day was hugely important then in reducing the absolute $ of systematic deleveraging “accelerant” flows, because only closing down -170bps in SPX then meant a much more manageable -$24.7B of Vol Control de-allocation in coming days, as opposed to what would have been a much more challenging -$62.9B to digest which we estimate would have been triggered off of a “-3% close”…while similarly, Leveraged ETFs only needed to rebalance -$5.9B at EOD, as opposed to a hypothetical -$8.9B assumed at the low of the day.”

(Please read the whole article.)


9:45 am

The S&P GSCI Ag Index took a brief pause in its ascent.  The Cycles Model infers a continued rally through mid-December as food prices skyrocket.   There are no bullish formations to speak of, but should Wave [3] be equal to Wave [1], the target would be 670.00.  Wave [3] may be the strongest of the series, so that would be a minimum.  Since this is a Primary Wave [3], it suggests a potential target between 850.00 and 1000.00.

ZeroHedge reports, “Robusta coffee prices continued to soar to record-highs this week as concerns deepen over the outlook from Brazil, the world’s top producer.

“Cheaper robusta-coffee beans, used widely in instant-coffee beverages such as Nestle SA’s Nescafe brands, are sold out in Brazil. After drought and frost ruined crops of the higher-end arabica variety favored by cafes like Starbucks Corp., local roasters are racing for robusta replacements and driving prices to new records each day,” Bloomberg wrote.

Spot prices for Brazil robusta Espirito Santo have nearly doubled this year, up 356 reais per 60-kg bag, or about 87% to 769 reais.”


8:20 am

Good Morning!

SPX futures rose to 4406.40 before being repelled by the gap left at 4402.95.  The 50% Fibonacci retracement level is at 4396.39 and futures have slid beneath that level.  The 38.2 Fib level is at 4375.04 which I proposed to be the top of the retracement yesterday.  It may yet open at or beneath that level.  That is why I suggested that no action may be needed to take profits.  The Cycles Model proposes the decline may resume in the first hour of the cash market.

ZeroHedge reports, “Even though China was closed for a second day, and even though the Evergrande drama is nowhere closer to a resolution with a bond default imminent and with Beijing mute on how it will resolve the potential “Lehman moment” even as rating agency S&P chimed in saying a default is likely and it does not expect China’s government “to provide any direct support” to the privately owned developer, overnight the BTFD crew emerged in full force, and ramped futures amid growing speculation that Beijing will rescue the troubled developer…

… pushing spoos almost 100 points higher from their Monday lows, and European stock were solidly in the green – despite Asian stocks hitting a one-month low – as investors tried to shake off fears of contagion from a potential collapse of China’s Evergrande, although gains were capped by concerns the Federal Reserve could set out a timeline to taper its stimulus at its meeting tomorrow. The dollar dropped from a one-month high, Treasury yields rose and cryptos rebounded from yesterday’s rout.”


The NYSE Hi-Lo Index closed at -73 yesterday, giving the final confirmation of the sell signal.  The interesting item is that the Hi-Lo is due for a Master Cycle low as early as tomorrow, but no agreement with the SPX and VIX.  This is odd, since there is another Master Cycle low in mid-October which syncs with the SPX.  This suggests to me that there may be some  event that may panic and close the markets, since the SPX and VIX are in mid-Cycle.  The two main events that could possibly affect the markets are a government shutdown, Evergrande and the Canary Island Volcano.


VIX futures pulled back to 22.36 this morning before resuming their ascent.  A move back aboe 25.00 may induce hedge funds and CTSs to resume selling, as this is considered gamma negative.


TNX is testing Intermediate-term support at 13.02 witht he 50-day Moving Average just beneath it.   Should it break beneath, it may be a signal for more decline to come.  The proposed Master Cycle terminus in mid-October may be the Cycle Bottom support, near 10.00.  Old habits die hard and a panic sell-off in stocks may drive investors into treasuries.

ZeroHedge observes, “In a risky move inviting a showdown with Republican lawmakers, House Democrats are linking a suspension of the US debt ceiling to a must-pass spending bill required to keep the government operating past September.

If it works, the debt ceiling – which GOP leaders have balked at raising – would be suspended through December 2022.

If nothing is done, the federal government will shut down and default on payments as soon as next month – a prospect which already has anxiety through the roof as measured by the spread between Oct and Nov T-bill yields.


USD futures are lower this morning, suggesting the anticipated Master Cycle may have ended yesterday, day 257 of the Master Cycle.  This appears to go hand-in-hand with treasury yields.  The USD may take a real beating as it is in a multi-year Orthodox Broadening Top and is targeted to land near 85.00 in the current decline.


Posted in Published | Comments Off on September 21, 2021

September 20, 2021, Pray for Our Country

2:45 pm

SPX bounced at Nomura’s final support (before oblivion) at 4310.00, having gone past the 100-day at 4328.00.  Whether it holds or not is still in question.  A decline beneath 4300.00 introduces the concept of a running correction, that is, a corection that may not be able to even make the lowest (25%) Fibonacci retracement, currently at  4353.00.  This is no time to take short profits.  There’s much more to come.

ZeroHedge comments, “US equity markets crashed through several technical levels, with S&P finding some support (for now) at its 100DMA…

As the spike in volatility (VIX is back up near 28)…

…prompted forced sellers in size, Nomura’s Charlie McElligott – who correctly called this post-opex plunge – notes some remarkable flows going-through earlier this morning in response to the initial “vol squeeze” risk-off, as we witnessed brave vol sellers not waiting for the market purge- or Fed event risk- to clear, and instead, actively attempted to harvest “rich” index vol & skew / shorted it, while others monetized downside hedge gains (because the back-test on vol spikes tells you that you have under 1 day before the rally in spot, LOL)…”


12:15 pm

VIX has risen above the neckline and is testing the Cycle Top resistance at 26.95.  While the SPX Master Cycle is scheduled to end on October 15, the VIX Master Cycle is not due to terminate until October 26, 11 days later.  There are other anomalies among the Cycles that suggest that what is happening ths October may not be normal.  This suggests such possibilities as a market closure.

ZeroHedge comments, “The last seven times that the S&P 500 has traded down to its 50-day moving-average, it has rebounded rapidly and aggressively.

This time – for now – is different, as Friday saw the S&P cash close back below the 50DMA and futures indicate a serious move below it at the open…

And things could escalate, as. following the extinction of a serious chunk of options on Friday, we start today with a sharply negative gamma position.

This negative gamma position doesn’t flip positive unless markets recover the 4425 area. For today we look to 4415 as resistance, with support at 4360 and 4310.”


8:15 am

SPX futures are down over 80 points as I write, crossing beneath the 50-day Moving Average and approaching the 43-week Moving Average at 4308.00.  The combination run-off from options expiration and Evergrande now at its lowest point ever, soon to be insolvent.

I am highlighting the weekly SPX chart to show the three-year Orthodox Broadening Top with a throw-over lasting a year.  Normally the throw-over of this height and duration may disqualify the Broadening Top, but a decline beneath 3900.00 may re-instate the Broadening Top and result in a quick decline to 2100.00.

ZeroHedge reports, “In retrospect, China, Japan, South Korea and Taiwan picked a great day to take a holiday, which as we noted last night hammered Hong Kong stocks more than 3%, slamming the Hong Kong property sector and sending Evergrande – which is expected to default within hours to a bank loan due Monday while crucial interest payment deadline on its offshore bonds looms on Thursday – to its lowest market cap ever (it closed down 10.2% just off the worst levels of the day) before the rout spread to European bourses and US equity futures as Evergrande’s escalating liquidity – and now solvency – crisis spread beyond the sector.

At 24,099 points, Hong Kong’s broader Hang Seng index has closed at its lowest level since October 2020.

“Evergrande is just the tip of the iceberg,” said Louis Tse, managing director at Wealthy Securities, a Hong Kong-based brokerage. Chinese developers were under substantial repayment pressure on dollar-denominated bonds, he added, while markets had become nervous that Beijing would push listed real estate groups to cut the costs of housing in mainland China and Hong Kong.

“That affects the banks as well — if you have lower property prices what happens to their mortgages?” Tse said. “It has a chain effect.”

But there may be yet another risk that is being summarily dismissed by the mainstream media.  Newsweek reports, “volcano has erupted on the Spanish Canary Island of La Palma, prompting unfounded fears that a so-called mega-tsunami could be headed to the East Coast of the United States.

The Cumbre Vieja volcano began erupting at around 3.12 p.m. local time (10:12 a.m. EDT) on Sunday, according to officials. It forced the evacuation of around 5,000 people from their homes in villages in the area, Canary Islands president, Angel Victor Torres, said in a press conference on Sunday. It marked the volcano’s first eruption since 1971.”

For those living on the East Coast, it may be advisable to monitor www.tsunami.gov for updates.  Should El Cumbre Vieja collapse, the espimated time to landfall in the United States would be 6-9 hours.


VIX futures have reached a new high at 26.75, crossing the Head & Shoulders neckline.  VIX has 3-4 weeks left in its Master Cycle, giving it time to go well past the Head & Shoulders target of 36.08.

ZeroHedge notes, “The last seven times that the S&P 500 has traded down to its 50-day moving-average, it has rebounded rapidly and aggressively.

This time – for now – is different, as Friday saw the S&P cash close back below the 50DMA and futures indicate a serious move below it at the open…

And things could escalate, as. following the extinction of a serious chunk of options on Friday, we start today with a sharply negative gamma position.”


The NYSE Hi-Lo Index opened at -28.00 and declined from there.  This is the final confirmation of the decline and SPX sell signal.

ZeroHedge remarks, “As futures indicated, the US cash equity open was greeted by an avalanche of selling, breaking the S&P back below its 50DMA…

This was the second largest sell-program in history with TICK crashing to -2067 (record low as -2069 on 5/11/21)…

…which means that we were off by just 2 stocks from the biggest selling-wave in history.

A sea of red in stonks…”


TNX appears to have made a Master Cycle high last Friday at 13.86.  This may allow a decline to the next Master Cycle(low) due in three weeks.  Today’s action is indicative on money flows into treasuries and out of stocks.  We may expect the next Master Cycle to reach its low at or near the Cycle Bottom, currently at 9.79.


Posted in Published | 1 Comment

September 17, 2021

12:38 pm

SPY may be on the verge of a gamma meltdown as there are 17,000 more put contracs than calls at 446.00.  At 445.00 there are 33,500 more puts than calls.  At 444.00 there are 28,000 more puts than calls.  SPY has already tested the 50-day Moving Average at 441.37.  Once beneath it, there may be no stopping the decline.

QQQ is in a similar position ar 374.50.  Puts begin accumulating at 378.00 and lower.


12:05 pm

SPX declined impulsively to the 50-day Moving Average at 431.95 and bounced.  The 38.2% Fib retracement is at 4453.85 while the 50% Fib retracement is at 4459.98.  A quikk bounce to one of these levels may ensue before a resumption of the decline.  Tere is a high probability that the retracement may not make either of these targets.  A decline beneath 4433.99 tells us SPX is in failure mode.

ZeroHedge observes, “That’s the message from the options market as ~30% of SPX gamma will expire at 9:30AM ET (and 60% of SPY, 35% of QQQ, and a very large set of stock options expiring on the close).

SpotGamma warns that 4500SPX/450SPY is still the biggest overhead level, with another heavy concentration of gamma at the 4475 area (and 4450 is the Put Wall)

The visual below on this expiration is well framed by this gamma table wherein light grey depicts the gamma expiring today.

As you can see the “board” will be reset for next week, just ahead of the 9/22 FOMC.”


8:00 am

Good Morning!

SPX futures are lower, having reached a low of 4458.20.  This is likely to be the Max Pain zone for SPX options due to the fact that puts have a slight edge over calls at 4460.00 and below.  SPY (close: 447.17) otions are also in the Max Pain zone.  However, open interest in 446.00 put contractss are 25,500 more than calls.  Moreover, 445.00 put contracts are 33,000 more than calls.  You get the picture.

ZeroHedge reports, “Quad-witching opex Friday has arrived, bringing with it the usual drama of gigantic gamma expiration, including $1.5trillion of SPX index,
$310bln of options on ES futs, $220bln of SPY options, $610bln of other index…

… a surge in market volumes, spike in volatility and now expected rebound in risk assetsWith over a third of market gamma set to expire today – specifically some 35% of SPX, 50% SPY, and 35% of QQQ gamma according to SpotGamma – brace for a bump ride as the absolutely gargantuan S&P pin at 4,500 is about to get much smaller, drastically reducing the market’s downside buffer.”


VIX futures ranged up to 19.60 this morning as tensions rise going into Quad Witching day.  Should SPY decline bebeath 445.00 we may see the VIX spike to the neckline at 24.50.  While today’s trending strength is neutral, next week appears to be another story.  We may see a breakout above the neckline by Wednesday, at the latest.


The NYSE Hi-Lo closed at 45.00, admittedly higher than Wednesday’s close, but in the danger zone nonetheless.  Trending strength (in the decline) is building with a possible Master Cycle low by mid-Week.  That may be followed by another Master Cycle low in mid-October.


TNX is rising into its Master Cycle (high) next week.  Thus far the behavior is stunted, since the minimal Wave (A) of [5] should reach 14.00.  Either my analysis is wrong (go figure!) or something dramatic is about to happen in the next few days.


Gold futures declined to 1752.05 this morning.  GLD options are hovering just above 163.00 with over 9,000 net put contracts.  Should that level be breached today, GLD may go into a tailspin as it anticipates a Master Cycle low by the end of next week.


The GSCI Ag Index rallied above its 50-day Moving Average at 410.15 and may challenge its Intermediate-term resistance at 414.60 in the next few days.  The Cycles Model says that GKX has clear sailing higher through mid-December.  The minimal target may be near 600.00, but could go considerably higher.  The secular uptrend may last another 5 years or longer.


Posted in Published | Comments Off on September 17, 2021