October 22, 2021

8:00 am

Good Morning!

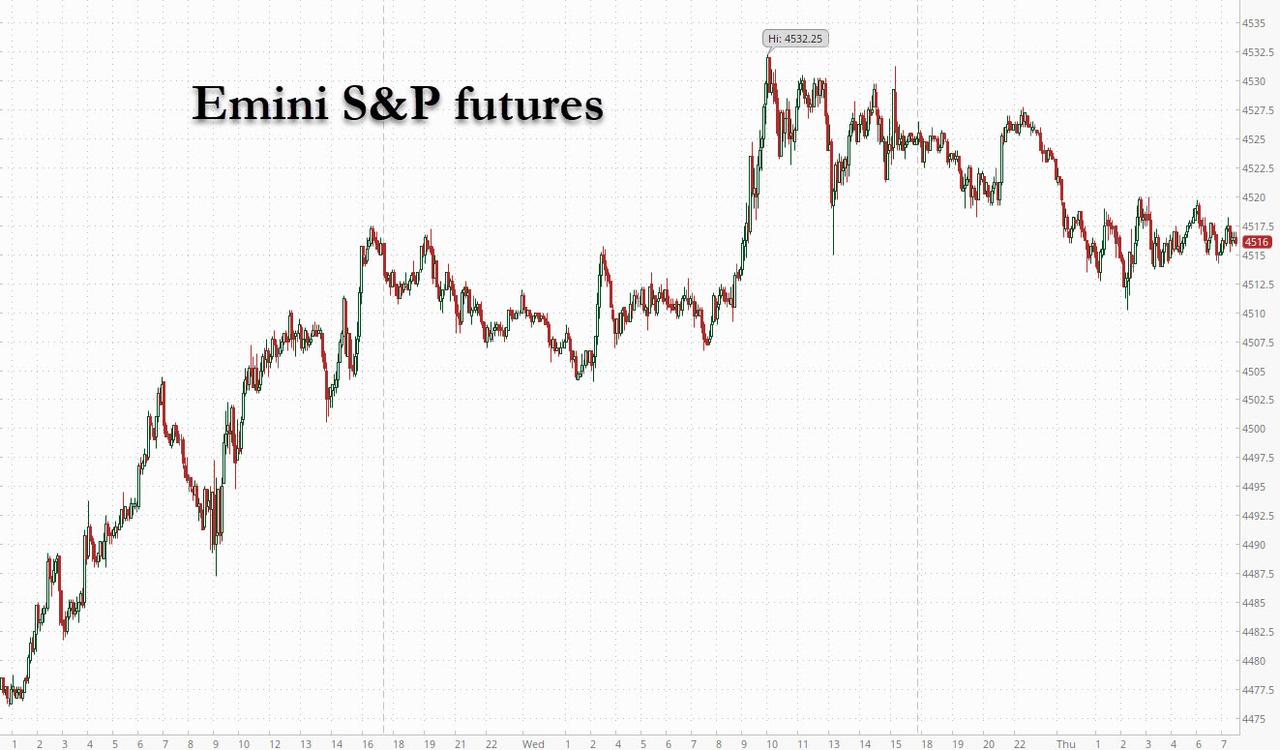
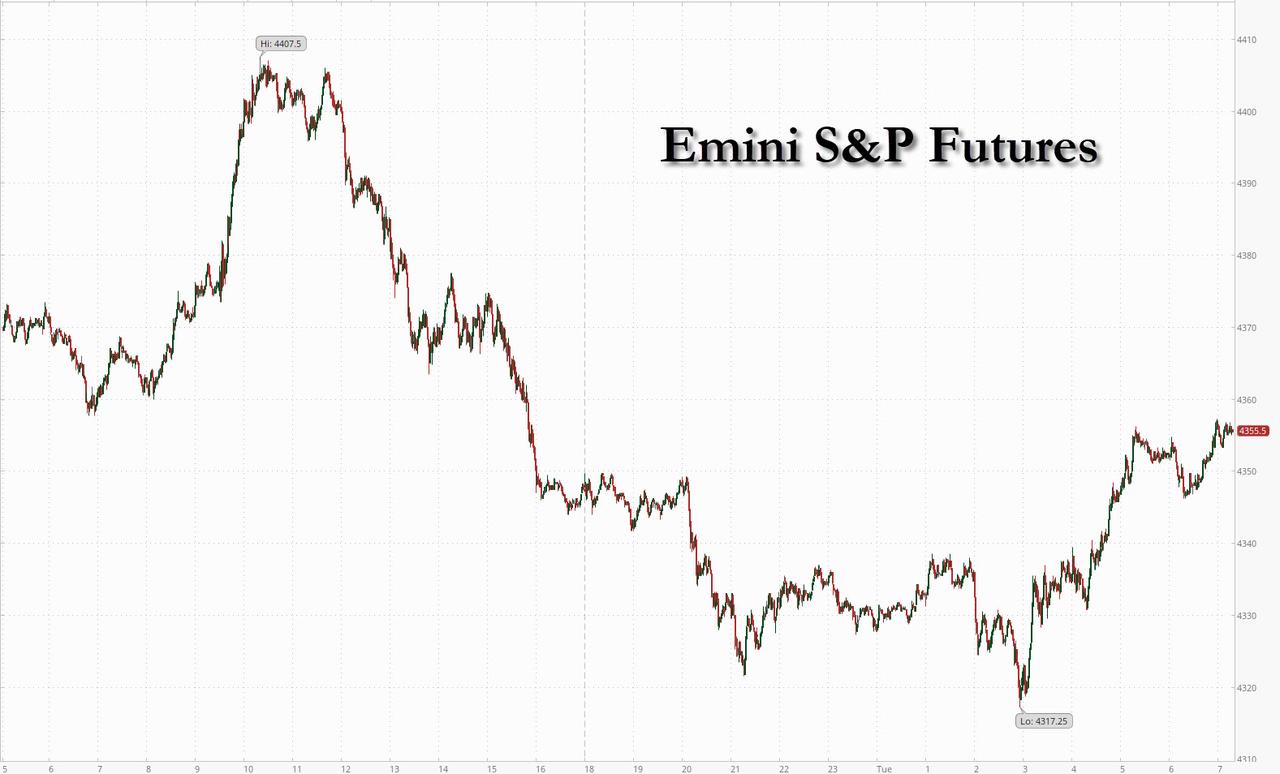
SPX futures are now testing the Cycle Top resistance at 4555.49 on day 266 of the Master Cycle.  Though unexpected, this should not be considered out-of-the ordinary as Cycles may expand or contract based on various inputs.   The single most obvious input today is options expiration.  Since dealers and hedge funds are net long, today’s options expiration may be a way to reduce long exposure without massive sales.  The shares are simply transferred to the options holders, who then may hold or sell.  In the meantime, the dealers book a profit at all-time highs.

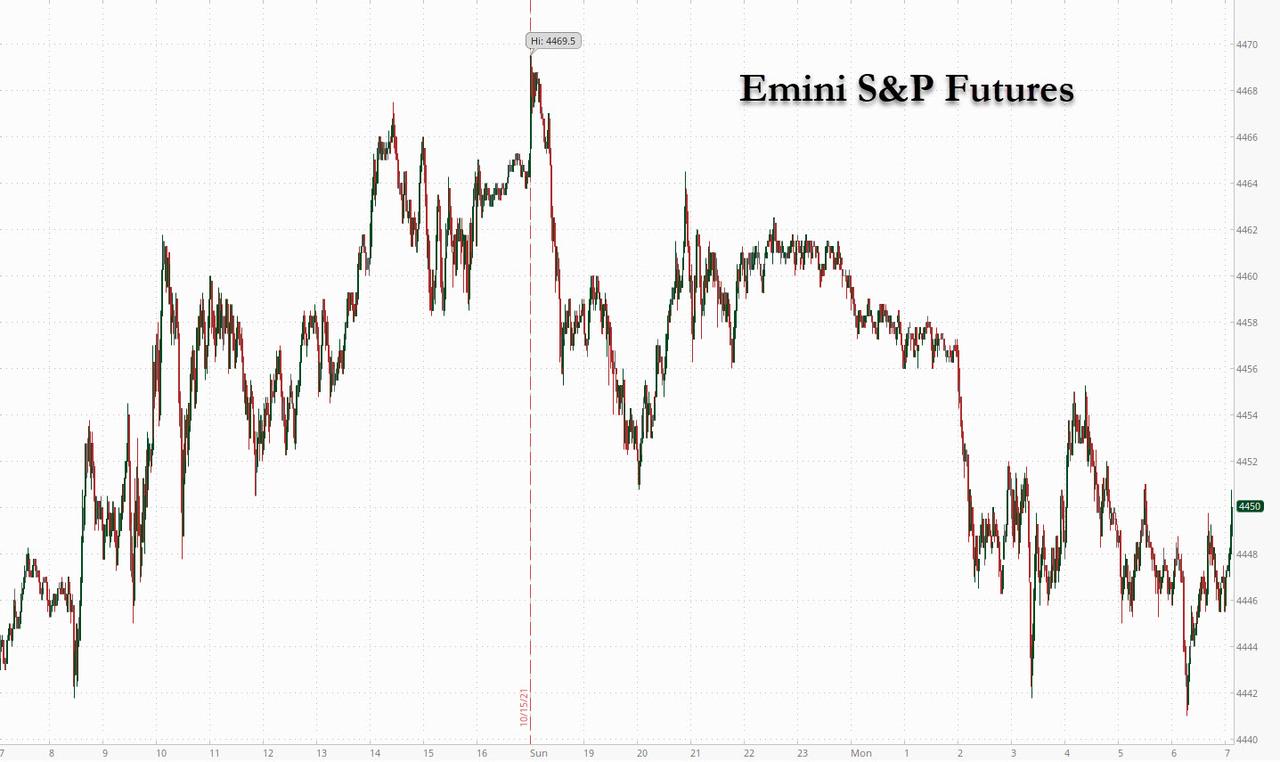
ZeroHedge reports, “S&P 500 futures traded to within 2 points of their September all time high, rising 0.12% to 4547, just shy of their 4549.5 record after China’s Evergrande unexpectedly made a last minute coupon payment, averting an imminent weekend default and boosting risk sentiment. But while spoos were up, Nasdaq futures edged -0.18% lower after Intel warned of lower profit margins, while Snap crashed 22%, leading declines among social media firms after flagging a hit to digital advertising from privacy changes by Apple. Intel plunged 10% in premarket trading as it missed third-quarter sales expectations, while its Chief Executive pointed to shortage of other chips holding back sales of the company’s flagship processors. 10Y yields dropped 2bps, the dollar slumped and bitcoin traded above $63,000. Fed Chair Powell is scheduled to speak at 11am ET. “


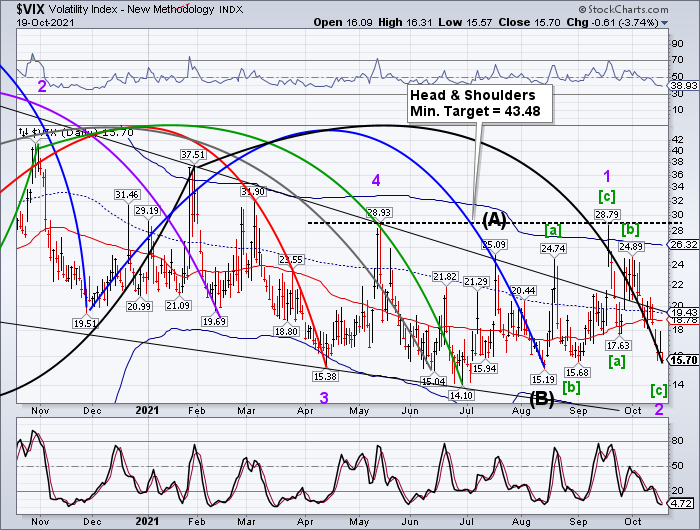
VIX futures tested yesterday’s low at 14.92 this morning but has not gone lower.    Today is day 254 of the VIX Master Cycle.  While it may go lower, the June low appears to be the limit.

ZeroHedge asks, “What If COVID Rears It’s Ugly Head Again?

The financial market focus on COVID has been much lower over the past few weeks. But what if COVID will be like the Halloween monster that always comes back? We now had the first major new lock-down in a “European” country – Latvia – that closes for 4 weeks. Latvia is “early” in entering the dark, cold and depressing northern hemisphere autumn & winter season…Now, Latvia has a pretty poor vaccination rate (just touching 50%) but so do many other countries around the world. Can COVID be the real “I will be back” monster for this Halloween?”


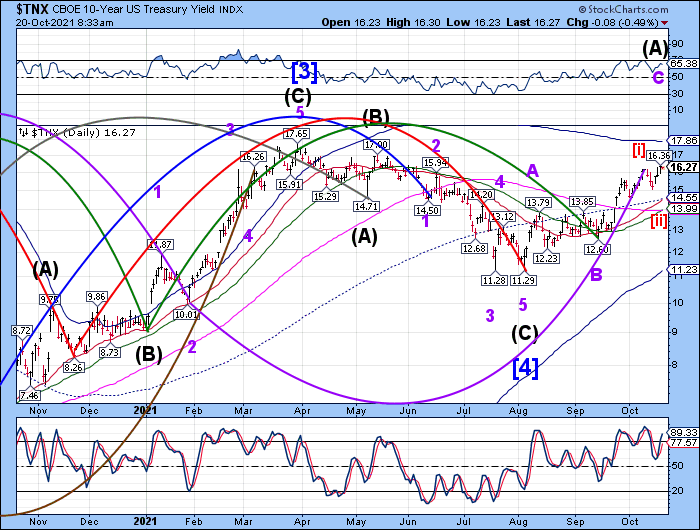
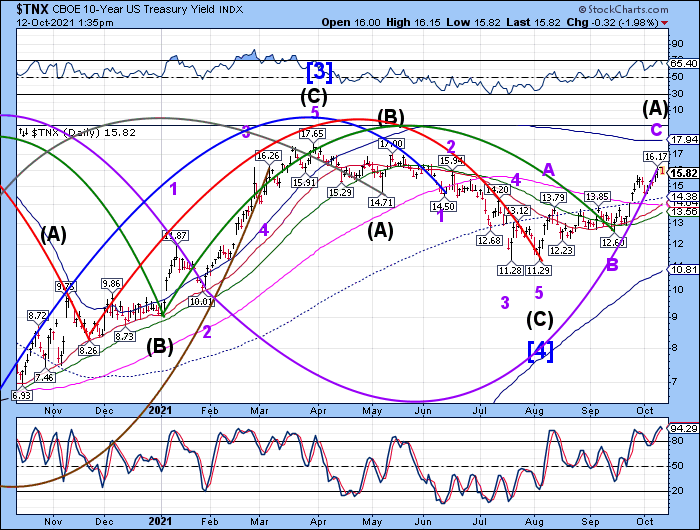
TNX futures climbed to a morning high of 16.99, suggesting the cash market may do the same.  If you think this is crazy, the Cycles Model calls for a triple play of trending strength next week.  If the media doesn’t report it, will it go away?


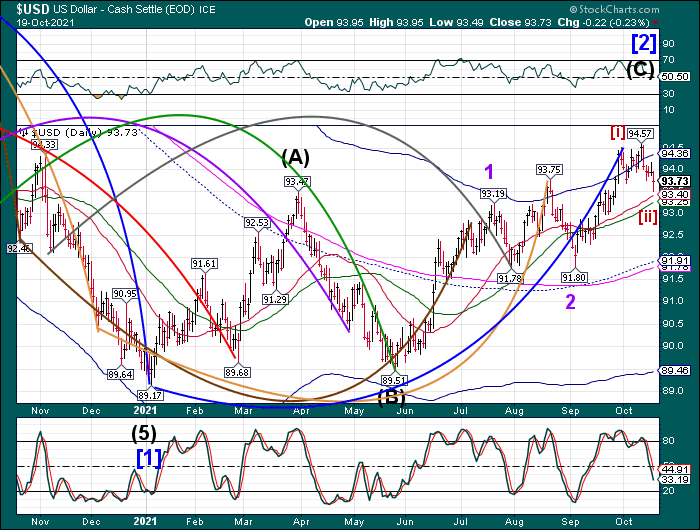
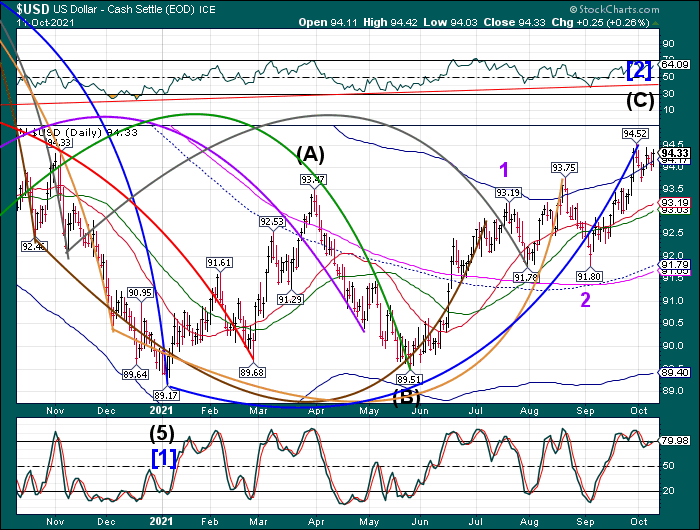
USD futures appear to be consolidating after yesterday’s corrective low.  The consolidation may not last, as the Cycles Model suggests trending strength comes roaring back as early as today.


Posted in Published | Comments Off on October 22, 2021

Ocober 21, 2021

10:20 am

SPX may have made its secondary high this morning, exactly 34.4 market days from its all-time high.  Noting confirmed yet.  Just though you’d like to know.


8:20 am

Good Morning!

The Industrials made a new all-time high yesterday, above the August 16 high of 35631.91, but was not accompanied by the other indexes.  US 30 futures made a morning low of 35483.20, having made no follow-through to yesterday’s high.  In addition, none of the other indices followed the DJIA to a new all-time high.  Dow Theory states that a new high must be confirmed by another index making a similar breakout to a new high.  The reversal without confirmation of a new high by other indices is problematic.  Note the declining volume after the September 20 low, giving us another non-confirmation.


Dow Theory takes its primary confirmation from the Dow Jones Transportation Average, which is lagging substantially behind the Dow 30 Industrials.  Logistical problems, high fuel costs and lack of manpower all suggest that the Transports may continue to lag the Industrials.  While Dow Theory is not a foolproof means of judging the markets, it still may be used as a guide to the market’s health.


SPX futures slid to a morning low of 4518.80.  Not enough to call it a reversal, but intriguing that it stopped short of a new high yesterday and has lost momentum.  4500.00 is still the critical juncture for tomorrow’s options, with the Max Pain zone at 4485.00.  While the primary dealers and hedge funds are interested in the least payout, they are still primarily long, with hedge funds being leveraged long.

ZeroHedge reports, “US index futures dropped after IBM and Tesla fell after their quarterly results, with investors turned cautious awaiting more reports to see the see the adverse impact of supply chain disruption and labor shortages on companies even as jitters remained over elevated inflation and the outlook for China’s property sector. The dollar reversed an overnight drop, while Treasuries fell pushing the 10Y yield to a 5-month high of 1.68%. At 745 a.m. ET, Dow e-minis were down 98 points, or 0.3%, S&P 500 e-minis were down 14 points, or 0.31%, and Nasdaq 100 e-minis were down 49.25 points, or 0.32%.”


VIX futures climbed to 16.11 in the overnight session.  The 50-day Moving Average is at 18.84 and may be used as a buy signal.

RealInvestmentAdvice asks, “Is A Volatility Storm Coming?

“Volatility often refers to the amount of uncertainty or risk related to the size of changes in a security’s value. A higher volatility means that a security’s value can potentially be spread out over a larger range of values. This means that the price of the security can change dramatically over a short time period in either direction.”    – Investopedia

Federal Reserve Bond Tapering & Interest Rate Hikes Reduce Liquidity

Federal Reserve liquidity injections have bailed out the economy and equity markets for the last 18 months. And as a result, the bailout created a relatively low volatility environment for equity and bond markets.  Will the announced withdrawal of Fed injections of $120B per month set up the monetary system for higher volatility?  We see major economic forces combining in the intermediate future to create a possible ‘volatility storm’ driving valuations down. These economic forces include:

  • Fed tapering
  • Interest rate hikes
  • Inflation
  • Labor wage increases.

One of these macro factors is a challenge for monetary policymakers to mitigate damage to the financial system.  But, a combination of these factors already building may overwhelm the monetary system. Further, markets are at historic high valuations today. But, market weaknesses and structure, along with valuations may create optimal conditions for a volatility storm.”


TNX has reached a new 5-month high at 16.75 (16.82 in futures) this morning.  Normally we would see a pullback in the next day or two before new highs are made, but the strength of the rally is evident and even more strength appears to be due starting Tuesday of next week.

ZeroHedge reports, “After last week’s solid auctions, traders were optimistically eyeing today’s 20Y auction – in the form of a 19-Yyear 10-Month reopening – as some speculated that just because this may be the last fully-sized, $24BN auction before the Treasury starts shrinking the notional next month, demand would be stellar. It wasn’t.

Stopping at 2.100%, more than 30bps above the September 1.795% high yield, the auction not only had the highest yield since June, but tailed dramatically to the 2.075% When Issued, the biggest tail in the 20Y auction history (which, of course, is not that long since the first auction was just last May).

The ugliness spread to the bid to cover, which slumped to 2.25 from 2.36, well below the six auction average of 2.36 and also the lowest since May.”


USD futures tested Intermediate-term support at 93.41 this morning, but appears to be on the rise again.  The Cycles Model calls for a Master Cycle high in the week of November 8.


The GSCI Ag Index climbed above its 50-day Moving Average at 414.25 and is on a buy signal.  The Cycles Model implies a continued uptrend until mid-December.  Serious flooding in China and India have exaserbated food shortages in Asia and

ZeroHedge remarks, “US restaurant chain Caribou Coffee Co. is panic hoarding coffee beans as a global supply deficit grips the world and fuels inflation.

“We continue to increase safety stock on key items,” CEO John Butcher told Bloomberg. Besides coffee beans, he said the company is loading up on cups, lids, packaging, chocolate, and anything that comes to mind as supply chains remain snarled.”


Posted in Published | Comments Off on Ocober 21, 2021

October 20, 2021

3:05 pm

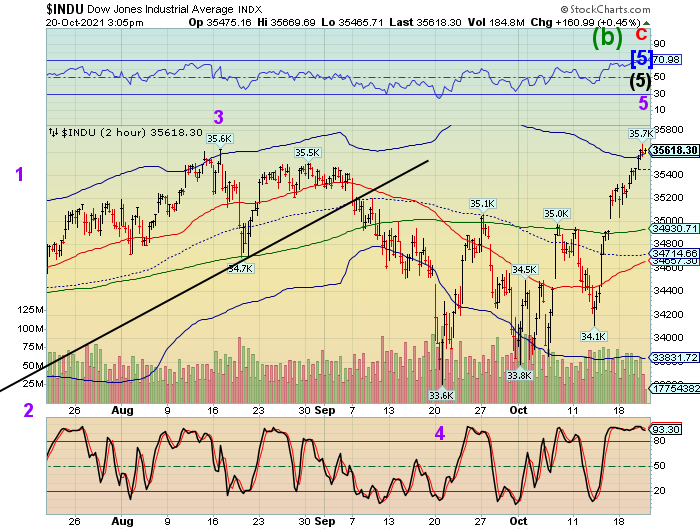
You may recall that in early September when the SPX finished its 5th Wave, I noted that it was missing in the DJIA.  Well, here it is.  The SPX, while very close, has not made a new high.  This created an interesting divergence.  The Wave structure now agrees that both indices may go down in unison.


8:15 am


Good Morning!

SPX futures are flat on day 264 of the Master Cycle.  In today’s expiring options, calls dominate above 4500.00.  Puts gain ascendance at 4475.00 and lower.  Max Pain lies somewhere between those two points.  This is where either the bulls take over and make new highs or an “accident” happens that causes a panic over the next week.  The 1987 crash happened in 4.3 days.

ZeroHedge reports, “US index futures were little changed as investors weighed the start of the earnings season against growing stagflation, tightening, energy crisis, China property and supply risks. S&P 500 futures were flat after the cash index edged closer to a record on Tuesday, rising above 4,500. Contracts on the Nasdaq 100 were also unchanged after the main index rallied for the past five days. At 7:30 a.m. ET, Dow e-minis were down 8 points, or 0.02%, S&P 500 e-minis were down 1 point, or 0.03%, and Nasdaq 100 e-minis were up 5 points, or 0.03%. Oil was down and the dollar steadied. Bitcoin traded just shy of its all time high overnight, and was last seen around $64,000.”


VIX futures made a morning low of 15.60, not breaking yesteray’s low.  Today is day 252 of the VIX Master Cycle.  Should it repeat the pattern of 8.6 months ago, a slingshot move may be in the making.

The NYSE HiLo Index closed at 104.00 yesterday after reaching a high of 183.00.  Although it closed 10 points higher than the day before, the trend is lower.

ZeroHedge warns, “He just called us…

Yesterday, before the market closed, our “VIX guy” called us explaining the case for a continuation of the VIX collapse.

Arguments are basically that everything is awesome and no risks can affect this market as strong seasonality is upon us.

We agree on the seasonality factor, but when the VIX guy calls us explaining why VIX should go even lower post this last volatility reset we get “uneasy”. He continues to hold a 100% inverse track record.

It is probably time to look at some cheap protection trades.”


TNX appears to be in a short-term decline, perhaps to the mid-Cycle support at 14.55 in the next few days.  The reason?  Should equities sell off, the knee-jerk reaction would be to buy treasuries.  The Cycles Model suports that thesis with a triple dose of strength roaring back early next week.

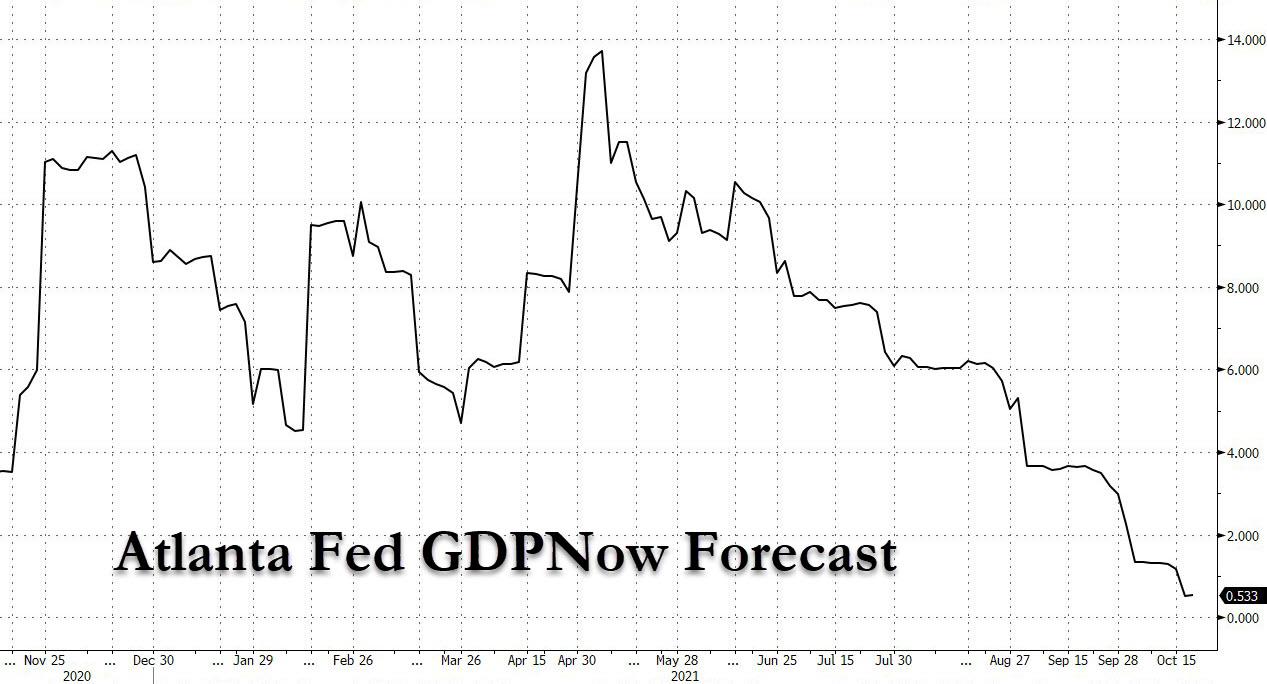
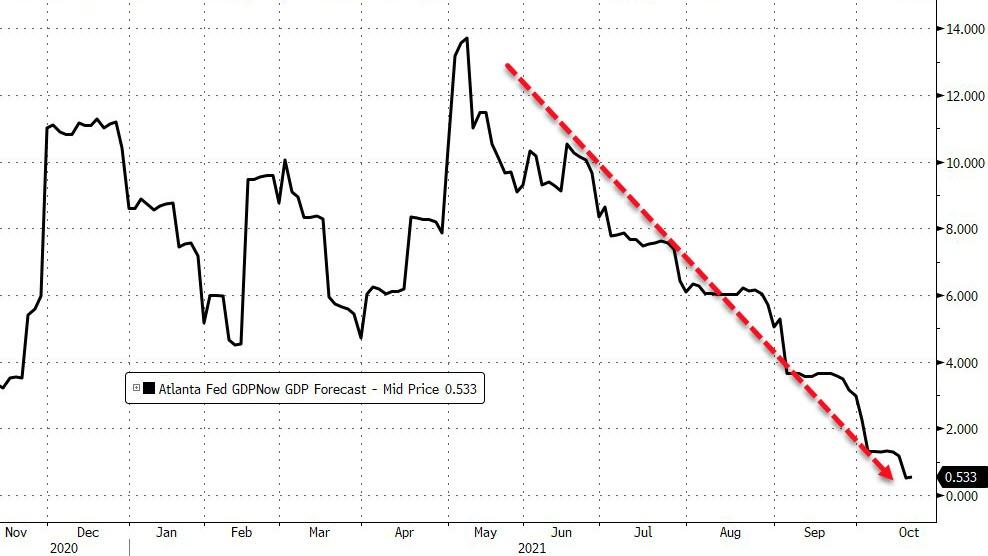
ZeroHedge observes, “t a time when the Wall Street banks are scratching their heads for credible explanations why they are keeping (or raising) their year-end S&P targets at a time when economic growth is in freefall and inflation is soaring (read: stagflation), an unexpected source of honesty has emerged – the Atlanta Fed, which now sees the US on the verge of contraction.

In its latest GDPNow forecast published moments ago, the Atlanta Fed slashed its estimate for real GDP growth in the third quarter of 2021 to just 0.5%, down from 1.2% on October 15, from 6% about two months ago, and down from 14% back in May.

Remarkably, the GDPNow tracker is about to turn negative even as the average “blue chip” Wall Street baank has a Q3 GDP forecast of just below 4%.”


USD futures appear to be re-testing yesterday’s low which may have completed the correction to the rally.  This may be suported by the Cycles Model which suggests strength building over the weekend and coming into full bloom by mid-November.


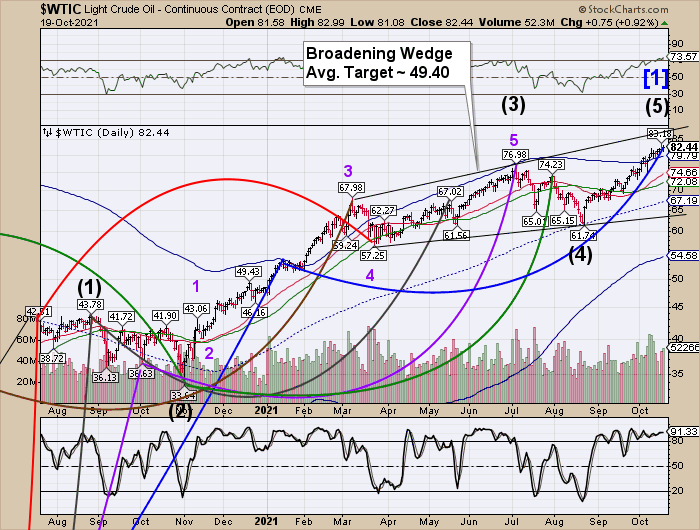
WTIC futures appear to be coming down from Monday’s high, an unusually long Master Cycle of 278 days.  The call for $100.00 oil or even $200.00 oil may be a bit premature.  While shortages of oil derivatives (propane) are appearing and gasoline prices have exceeed their 2018 highs, there is a possibility of a slowdown large enough to correct the current trend.

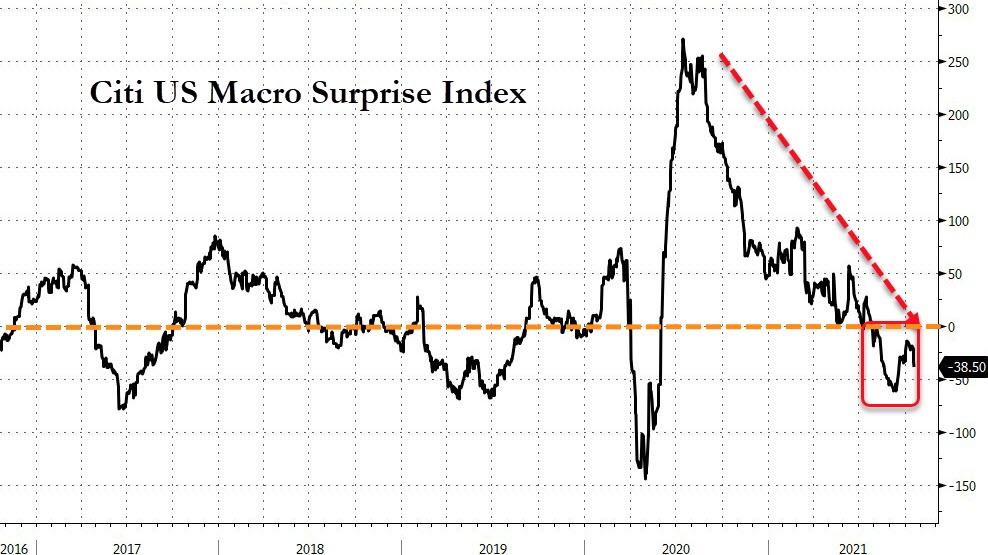
ZeroHedge observes, “US macroeconomic data has been broadly disappointing for months…

Source: Bloomberg

And that has driven forecasts for GDP growth into the floor. Just yesterday, The Atlanta Fed’s GDPNOW model adjusted to forecast just 0.5% GDP growth…

Source: Bloomberg

And at the same time, the market is pricing in an increasingly hawkish trajectory for taper and rate-hikes from The Fed…”


Posted in Published | 1 Comment

October 19, 2021

8:00 am

Good Morning!

SPX futures are now above 4500.00 as Intermediate Wave (B) continues its ascent on borrowed (literally) time.  Today is day 262 of the current Master Cycle.  Since Cycles are organic, so inputs, such as cash, tend to lengthen the growing season.  Wednesday’s options expiration is light, but calls dominate above 4425.00.  Hedge funds and dealer banks are surprisingly long and the talk on Wall Street is bullish.

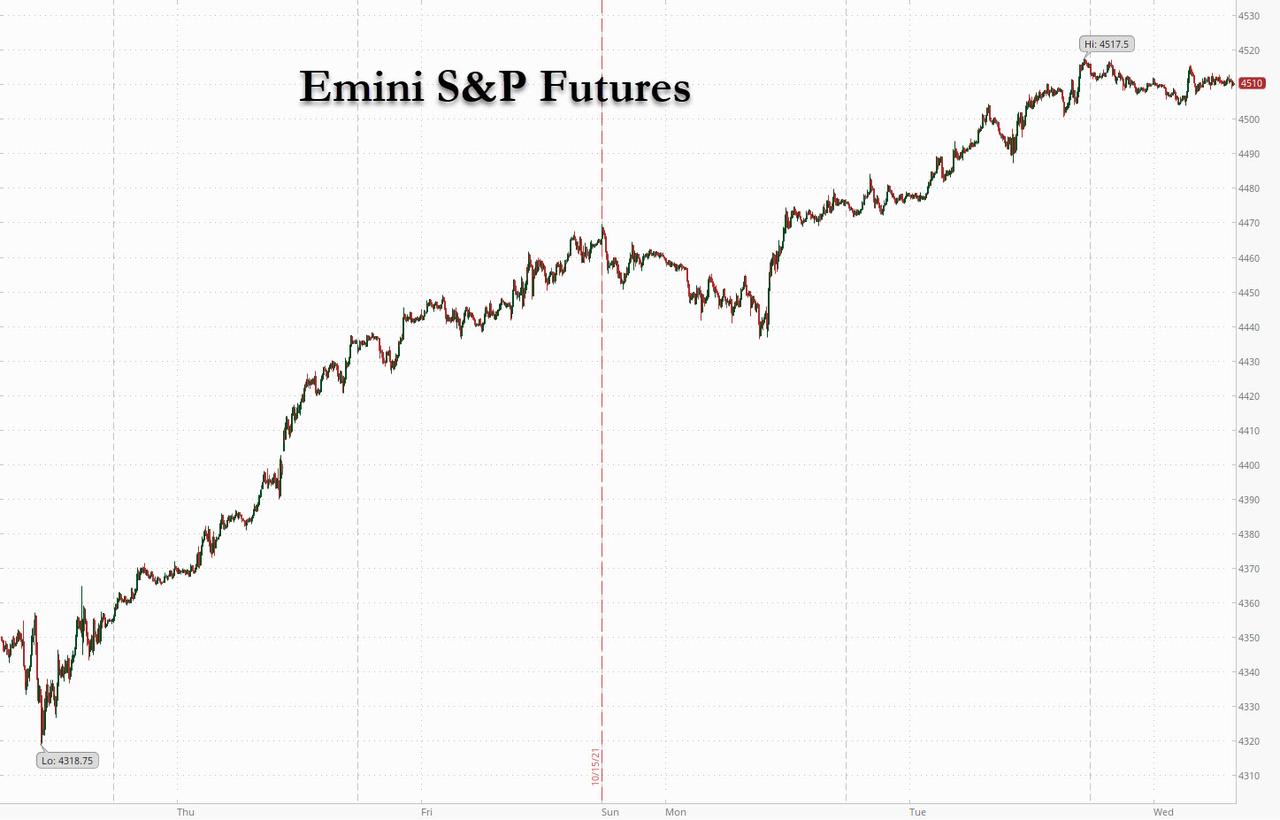
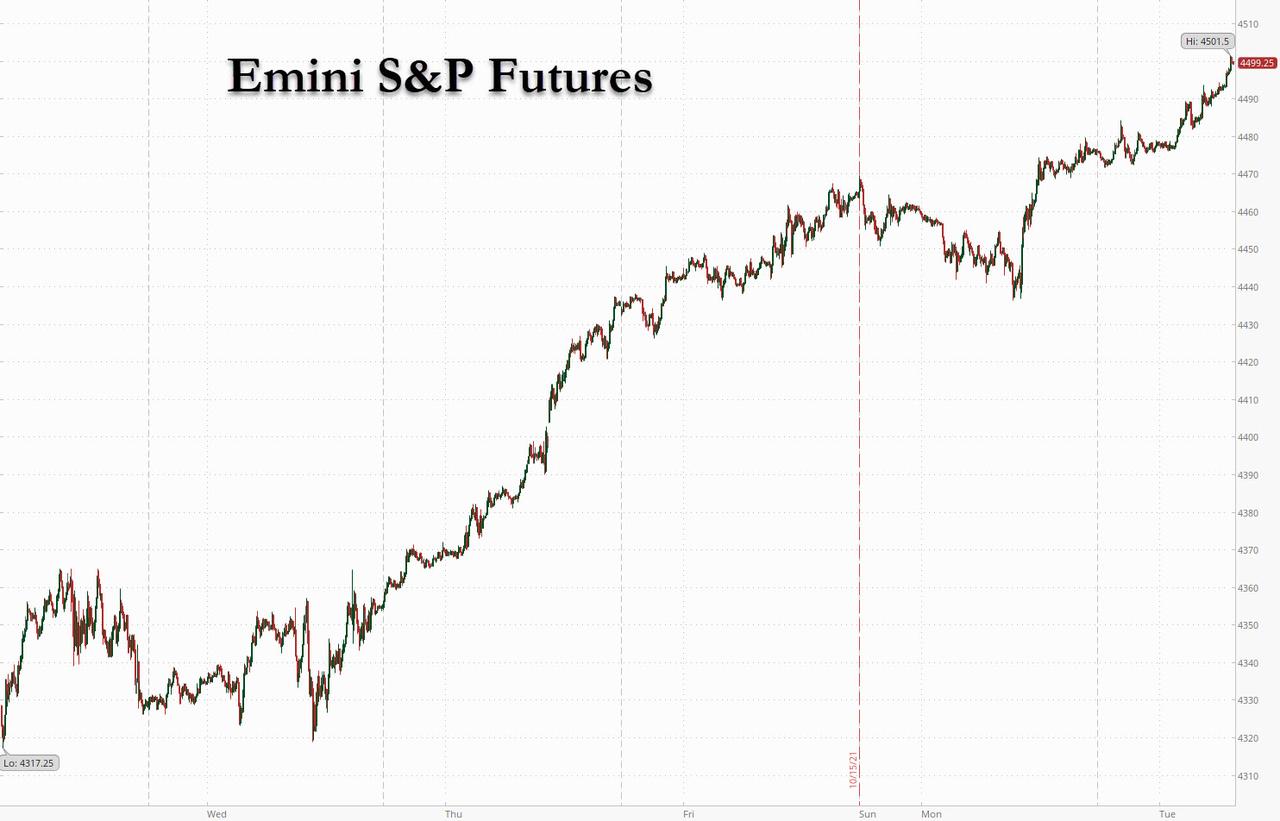
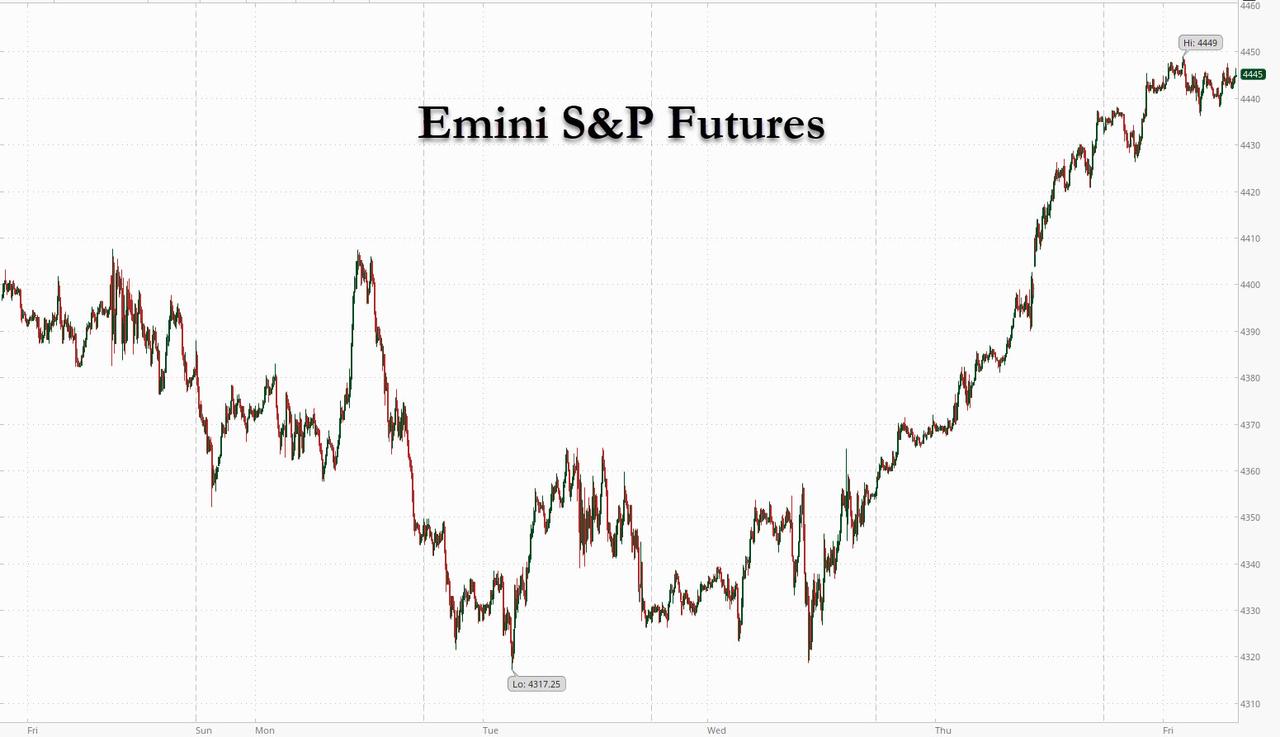
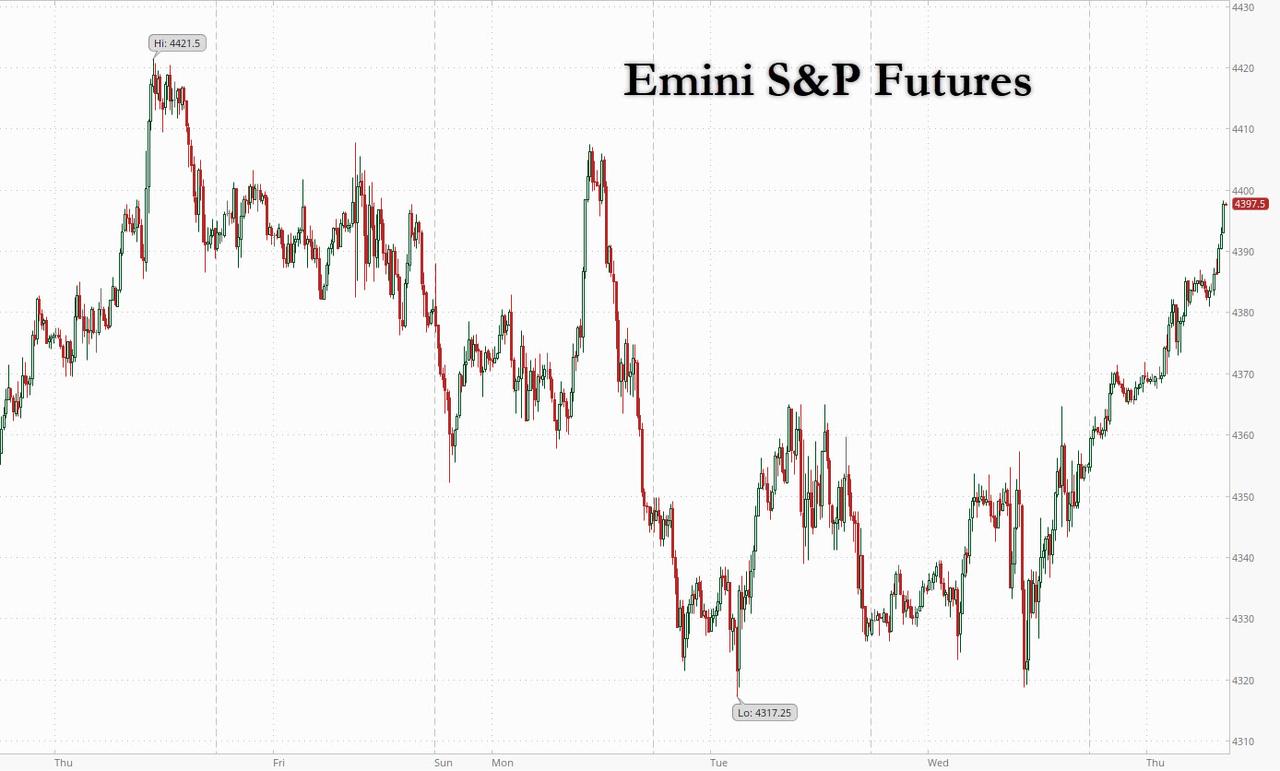
ZeroHedge reports, “Over the weekend, a Goldman flow trader explained why it expected a powerful market meltup to emerge in coming days, and this time Goldman was right because after trading at 4317 just one week ago, spoos are now almost 200 points higher, rising above 4500 this morning after a powerful ramp pushed US equity futures and global markets as an upbeat profit forecast from Johnson & Johnson which boosted (get it “boosted”) its Revenue and EPS guidance, added to the positive momentum in corporate earnings generated by big banks last week and helped counter concerns about elevated inflation. At 715 a.m. ET, Dow e-minis were up 183 points, or 0.52%, S&P 500 e-minis were up 22.75 points, or 0.51%, and Nasdaq 100 e-minis were up 61.75 points, or 0.40%. Treasury yields were unchanged at 1.60% and the dollar slumped to a 4 week low.


VIX futures traded at a low of 15.95 this morning, possibly verifying Friday’s Master Cycle Slingshot low.  Traders often misread the VIX, conflating a low VIX with a rising market.  However, the market rises “best” with a declining VIX.  Once the decline has stopped, the risk of a reversal rises.  In addition, the Cycles propose a possible “slingshot move” that may be aimed at the Head & Shoulders target within 8.6 market days.

Yesterday’s NYSE Hi-Lo closed at 94.00, 81 points beneath Friday’s close.


TNX made a new corrective low, but quickly recovered.  Wave [ii] corrections may go higher than the Wav e[i] high.  The Cycles Model suggests a brief pullback this week, but trending strength may return next week.


USD futures made a low of 93.49, which may complete the corrective pattern.  If not, any further decline may be short-lived, as trending strength may re-emerge early next week.  A Master Cycle high may be due the week of November 8.


Posted in Published | 4 Comments

October 18, 2021

7:50 am

Good Morning!

SPX hit its lesser targer at 4475.00 on Friday, day 259 of the Master cycle.  Friday was calendar day 43 from the all-time high.  Now for the decline.

SPX futures made a low of 4450.10 this morning before a minor bounce.  It renews its sell signal beneath the 50-day Moving Average at 4437.67.  Today’s options expiration still appears to dominate trading.  The Max Pain zone is at 4465.00 with calls dominating above and puts in charge below.  The 50-day Moving Average is at 4437.67 with a second bearish cross in place.

ZeroHedge reports, “US equity futures and world shares drifted lower following poor Chinese macro data which saw the country’s GDP slide to a weaker than expected 4.9%, and as surging energy prices and inflation reinforced bets that central banks will be forced to react to rising inflation and hike rates faster than expected. Calls by China’s President Xi Jinping on Friday to make progress on a long-awaited property tax to help reduce wealth gaps also soured the mood. With WTI crude rising to a seven-year high, and Brent back over $85, investors remain concerned that living costs will be driven higher. The economic recovery also remains uneven with China’s gross domestic product slowing more than expected in the third quarter, increasing aversion to riskier assets. The dollar rose against all of its Group-of-10 peers as concerns about an acceleration in inflation damped risk appetite, while bircoin traded above $61K and just shy of an all time high ahead of the launch of the Proshares Bitcoin ETF on Tuesday.

An MSCI gauge of global stocks was down 0.1% by 0808 GMT as losses in Asia and a weak open in Europe erased part of the gains seen last week on a strong start to the earnings season. U.S. stock futures were also lower with S&P 500 e-minis last down 0.2%, while Dow and Nasdaq e-minis were both down 0.3%.


VIX futures surged to a morning high of 17.70, still beneath the 50-day Moving Average at 18.84.

Friday’s low (day 247) may be part of a “Double Master Cycle” where we see a major high and low in very close proximity, known as a “slingshot move”.  Friday’s Cycle low originated 8.6 months ago as a Master Cycle high on January 29 (day 238).  8.6 market days later and nearly 50% lower, a second Master Cycle was formed on day 250.  We may now anticipate a similar move, in reverse, during the next 8.6 market days.  It may be an interesting trade, for those that can catch it.


TNX has just exceeded it prior Master Cycle high, creating what is known as a “running correction.”  The rally may continue in corrective form over the next two weeks.  Due to the strength of this rally, the new Master Cycle may end at a high at or above its November 2019 high at 19.71.

RealInvestmentAdvice considers, “Investors are slowly waking up to the realization that “stagflation” is a problem. For years, the term “stagflation” has been thrown around and dismissed like a sighting of “Bigfoot.” However, rising inflationary pressures are now colliding with slowing economic growth. This collision presents a challenge for Central Bankers and their monetary policy experiments.

Let’s start with a definition of “stagflation.”

“Stagflation is characterized by slow economic growth and relatively high unemployment—or economic stagnation—which is at the same time accompanied by rising prices (i.e. inflation). Stagflation can be alternatively defined as a period of inflation combined with a decline in the gross domestic product (GDP).” – Investopedia

As stated, many believe stagflation is impossible due to the economic theories that dominate academic and policy-making circles. The construction of the economic models ruled out the possibility that you could have slow economic growth and high inflation simultaneously.”


USD futures appear to be consilidating, although there may be a resumption of the rally.  The Cycles Model shows strength starting early this week and extending through mid-November.


Gold futures made a new low at 1760.35 this morning as it ventures lower to the trigger point of the Broadening Wedge formation at 1750.00.  The Cycles Model suggests that, once beneath the trigger, the decline may strengthen dramatically.  However, there may be yet another bounce at the neckline of the Head and Shoulders formation.


Posted in Published | 2 Comments

October 15, 2021

7:30 am

Good Morning!

My wife and I are leaving for a “destination wedding” at Boyne Falls this weekend.  The colors should be magnificent.

SPX futures rose to an overnight high of 4457.80 where Wave [v] of C is .62 times Wave [i] of C.  Wave [v] of C is often equal to Wave [i] of C at 4475.00.  Generally C Waves are equal to their corresponding A Waves which makes the potential target at 4480.00.  It appears that, while the time target has been made, the distance target may have another probe higher.  Today is day 259 of the current Master Cycle.  Up to a week ago, I could not imagine that this Cycle would end in a high.

In today’s options market, 4435.00 appears to be the Max Pain level, while options become bullish at 4450.00.  Positive gamma becomes irresistable at 4475.00.  In SPY (442.50), the battle rages with open interest at 75,326 at 440.00 calls in todays expiration, while open interest in puts is 84,369 puts at today’s expiration,  That may also be the Max Pain level, although the dealers and hedge funds that sold these option may be like a cat on a hot tin roof.  Which way to jump?

ZeroHedge reports, “One day after the S&P posted its biggest one-day surge since March, index futures extended this week’s gains, helped by a stellar bank earnings, while the latest labor market data and inflation eased stagflation fears for the time being. . The 10-year Treasury yield rose and the dollar was steady. Goldman Sachs reports on Friday. At 715 a.m. ET, Dow e-minis were up 147 points, or 0.42%, S&P 500 e-minis were up 16.5 points, or 0.37%, and Nasdaq 100 e-minis were up 42.75 points, or 0.28%.”


VIX futures made a new low this morning at 16.55.  While this looks like a Master Cycle low, today is only day 247.  It’s not impossible for a Cycle to go from low to high in 8.6 market days.  That puts us at Wednesday October 27 as a potential Master Cycle high.  The Wave structure is winding up for an upward probe that may be a multiple of Wave 1.


The KBW Bank Index has stopped making new highs on Monday, which is a puzzle after blow-out earnings being reported on all but Wells Fargo during the week.  I made comment on it earlier this week that the timing was noteworthy based on the Cycles.  Now we have something else to consider.

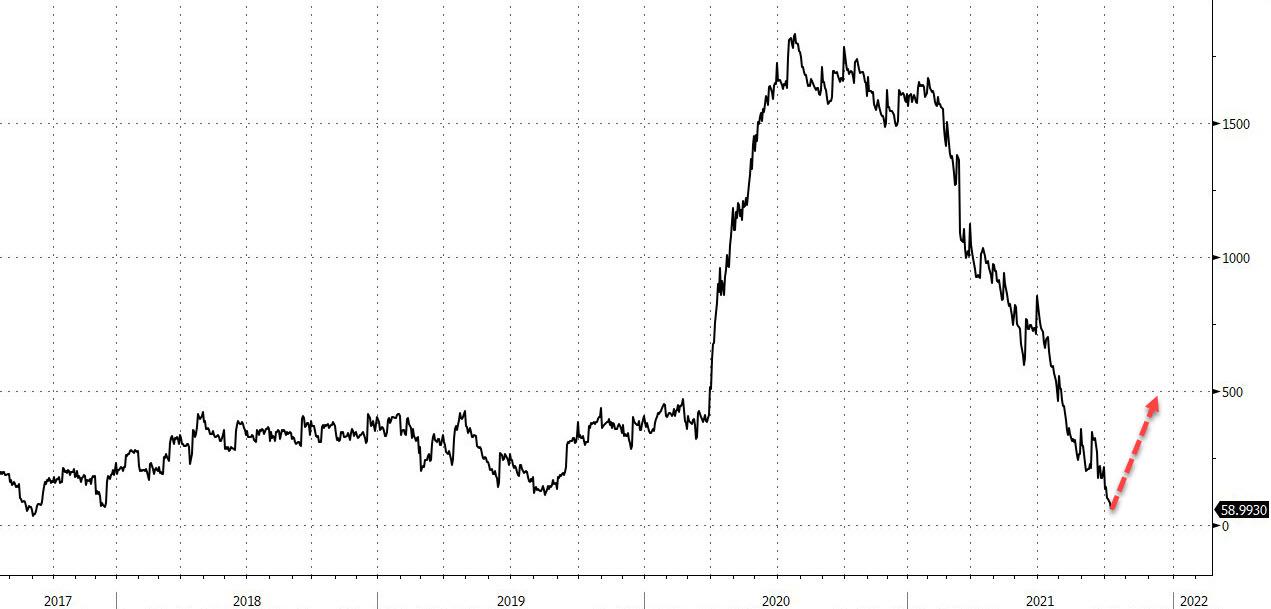
ZeroHedge remarks, “Back in February, when looking at the Treasury’s debt and cash projections, we warned that the market was about to be hit with “Mind-Boggling Liquidity” as the Treasury was about to release some $1.1 trillion in cash from its account at the Fed (the Treasury General Account or TGA), in effect conducting a parallel – and stealth – QE to the Fed’s own $120BN/month liquidity injections.

That’s precisely what happened, and since then, Treasury cash levels collapsed from an all time high of $1.8 trillion down to the previous target of $300 billion, and then continued dropping as the Treasury used up most of its cash to plug holes associated with the ongoing debt ceiling drama.

But that’s now over, at least until December, and with Treasury cash dropping to a 4 year low of $59 billion on Wednesday, the Treasury is now set for a sharp liquidity drain as it seeks to build up some $480 billion in funding through the early December debt ceiling reprieve, which is how much time and capacity Janet Yellen bought herself with the stop-gap debt ceiling deal that passed just in the nick of time last week when Senator McConnell caved to the democrats.”


TNX bounced this morning after the first leg of its correction.  The Cycles Model suggests TNX may ride on trending strength above last week’s high.  It also indicates the corrective phase may last until mid-November.


The GSCI Ag Index appears to have completed a Trading (minor) Cycle low and may break above its resistance area.  The current Master Cycle is due for completion in mid-December.  Don’t let the modest uptrend fool you.  We may see growing trending strength into the end of October.

ZeroHedge remarks, “At least someone is honest when it comes to soaring food inflation:

“Food is too cheap,” Ranjit Boparan, who is known as the “Chicken King” in the UK, was quoted by Reuters 

“In relative terms, a chicken today is cheaper to buy than it was 20 years ago. How can it be right that a whole chicken costs less than a pint of beer? You’re looking at a different world from now on where the shopper pays more,” Boparan said, who produces 33% of all poultry products in the country. ”

TheEpochTimes reports, “Compared with just one month ago, consumers are paying slightly more for most goods and services. Compared with a year ago, however, they’re paying significantly more, according to Labor Department data released this week.

The Labor Department reported that the consumer price index, a key inflation gauge that measures how much Americans pay for goods and services, rose about 0.4 percent in September. The year-over-year prices increased 5.4 percent, which some noted is the largest yearly increase since January 1991.”


Posted in Published | 1 Comment

October 14, 2021

1:30 pm

SPX has reached its target (Max Pain) allowing a minimum payout by the dealers and hedge funds.  By 3:00 pm, it will have completed a half-Trading Cycle  of 30.1 market days and 43 calendar days from the all-time high.  Intermediate Wave (C) is next.

Here is a description of a Wave (C):  Prices move impulsively lower in five waves. Volume picks up, and by the third leg of wave C, almost everyone realizes that a bear market is firmly entrenched. Wave C is typically at least as large as wave A and often extends to 1.618 times wave A or beyond

ZeroHedge warns, “Inverse panic

Here we go again, people selling protection in panic. VIX is down, but the big puke is to be seen in V2X (Eurostoxx 50 “VIX”).

It is now trading below VIX…something not seen in ages.

Our take from yesterday is playing out well:

“As we mentioned earlier, the ideal set up would be another mini rip higher, vols come down further and open up for some attractive hedging/speculation trades.”

The rip has occurred and protection has been puked. Don’t forget; “buy protection when you can, not when you must”.

Time to start executing…”


7:40 am

Good Morning!

SPX futures have surpassed the 61.8% retracement level at 4391.65 in an effort to rise into  the Max Pain level a 4430.00.  That indicates the possibility of a new corrective high, since it may retest the 50-day Moving Average at 4434.11.  Options gamma turns bullish at 4450.00, so this may be a strong spike, but not a runaway market.  Options are increasingly bearish and accident prone, thus it is seeking a higher level just to keep from a forced selling scenario.  A marginal new high today may leave 8.6 days for a potential panic decline immediately following the high.  If the hourly count is correct, we may see a turn at or before the final hour of the day.

ZeroHedge reports, “US equity futures, already sharply higher overnight, jumped this morning as a risk-on mood inspired by stellar bank earnings, overshadowed concern that supply snarls. a China property crunch, a tapering Fed and stagflation will weigh on the global recovery. Nasdaq futures jumped 1%, just ahead of the S&P 500 which was up 0.9%. 10-year Treasury yields ticked lower to about 1.5%, and with the dollar lower as well, oil jumped. Bitcoin and the broader crypto space continued to rise.”


VIX futures made a new low of 17.56, changing the structure of the decline to complete a Wave 2 correction.  This is not the terminus of the Master Cycle.  The Cycles Model hold out October 26-27 as a potential Master Cycle high.


Yesterday’s performance by the NYSE Hi-Lo Index was surprisingly weak, considering itg gains at the end of the day.  however, there is likely to be a spike in the Hi-Lo today (a potential Master Cycle high).  That appears to lead to a mid-December low for the next Master Cycle.


TNX slumped this morning after yesterday’s sharp reversal.  We may yet see a decline to underlying supports before strength swows up again next week.

ZeroHedge reports, “After CPI’s “transitory”-narrative-busting rebound, analysts expected Producer Prices to accelerate even further into record territory and it did – jumping 0.5% MoM to a new record 8.6% YoY. Bothe prints were modestly below the expected levels (+0.6% MoM and +8.7% YoY respectively)…

Source: Bloomberg

Core PPI also rose but less than expected. However, on a year over year basis, it was still a series high…”


USD futures fell to 93.76 this morning as corrective forces take over.  This may be a bumpy decline, but the Cycles Model suggests a low in the second week of November.


Posted in Published | Comments Off on October 14, 2021

October 13, 2021

2:33 pm

While we were watching the SPX, another indicator has turned.  The BKX, a proxy for market liquidity, has reversed down from Monday’s high and the Cycle Top resistance at 140.05.  A Master Cycle reversal may be considered a sell signal, but we await another indicator…the 50-day Moving average at 129.48 for a confirmed sell signal.  The Cycles Model suggests lower liquidity through late November or early December.  This index tells us what is keeping all assets afloat for the past 18.5 months, perfect timing for a Wave (b).  The coming decline may match or exceed the decline from February 2007 to March 2009.

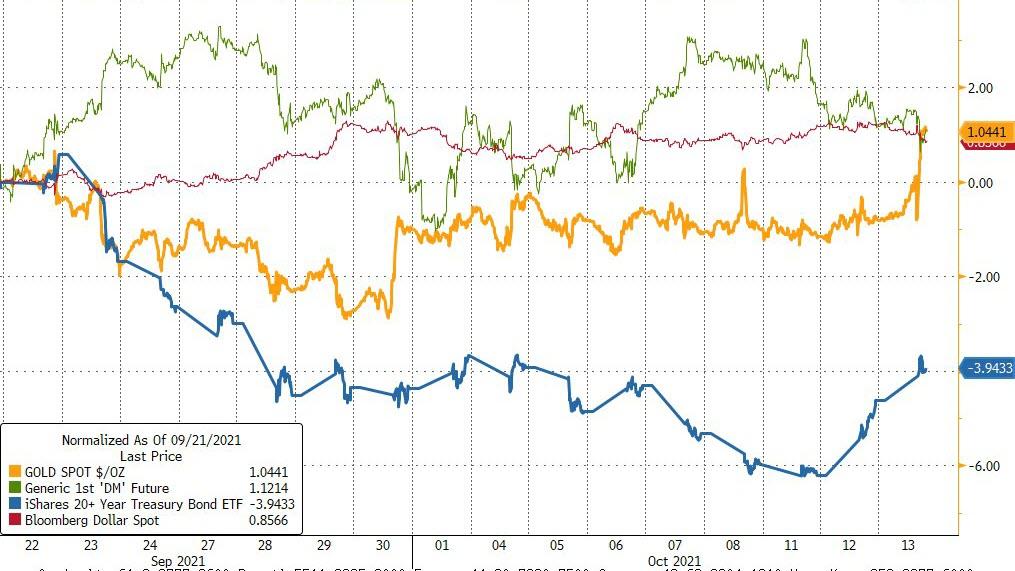
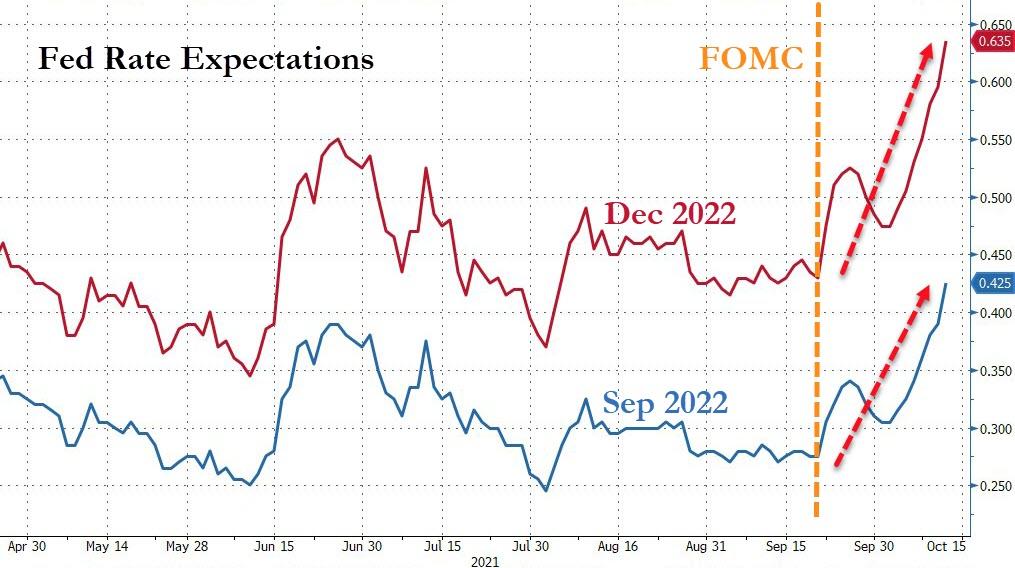
ZeroHedge observes, “Since the last FOMC meeting (September 22nd) – when Chair Powell began to detail the taper and rate-hike traajectory to come – bonds are down (yields higher) but stocks, gold, and the dollar are all up around 1%…

Source: Bloomberg

And even more notably, the trajectory (and initial timing) or rate-hikes has soared…

Source: Bloomberg

But the long-end of the yield curve is signaling that The Fed will once again commit a faux-pass…”


2:23 pm

Today’s action verifies the Master Cycle high put in on Friday.  The Cycles Model suggests lower rated through mid-November.  This doesn’t make sense to many, but the money flows tell all.

ZeroHedge reports, “After an ugly 3Y auction, and a solid 10Y sale yesterday, moments ago the Treasury sold $24BN in a 29 Year-10 month reopening of cusip SZ2 ahead of today’s Fed minutes. But if one thought investors would show any nerves about the coming taper in today’s auction, boy were they in for a surprise.

That’s because the auction was nothing short of spectacular: stopping at 2.049%, the auction stopped through the 2.062% When Issued by 1.3bps, which aside from last month’s 1.8bps stop, was the first non-tailing auction in 5. That said, it was the highest auction for the 30Y tenor since June’s 2.172, even if there was no concession in today’s session as a result of the sharp grind lower in yields on the long end if not the short one.”


2:05 pm

SPX revisited the MAX Pain level at 4375.00, but could not maintain it.  It has also failed at the Short-term support at 4366.75.  The negative gamma may take hold and propel SPX much lower.  The Cycles Model suggest a strong move today, possibly a panic decline.  The Model supports the notion that, once it begins there may be no stopping it this week, just in time for monthly options expiration.

The NYSE Hi-Lo Index opened at 22.00 and rose to 58 tis afternoon.  A reversal may give it a negative number at the close of the day.


8:15 am

Good Morning!

SPX futures rose to test the 100-day Moving Average at 4362.45 this morning.  Should it not be able to rise above it, the next suport is the Lip of the Cup with Handle formation at 4306.00.  The Max Pain zone for today’s options is at 4375.00.  Today’s expiring options become increasingly more bearish down to 4300.00, where there are 6800 net open interest contracts expiring today.  The Cycles Model implies trending strength over the next three days. suggesting a panic decline may be in the making.

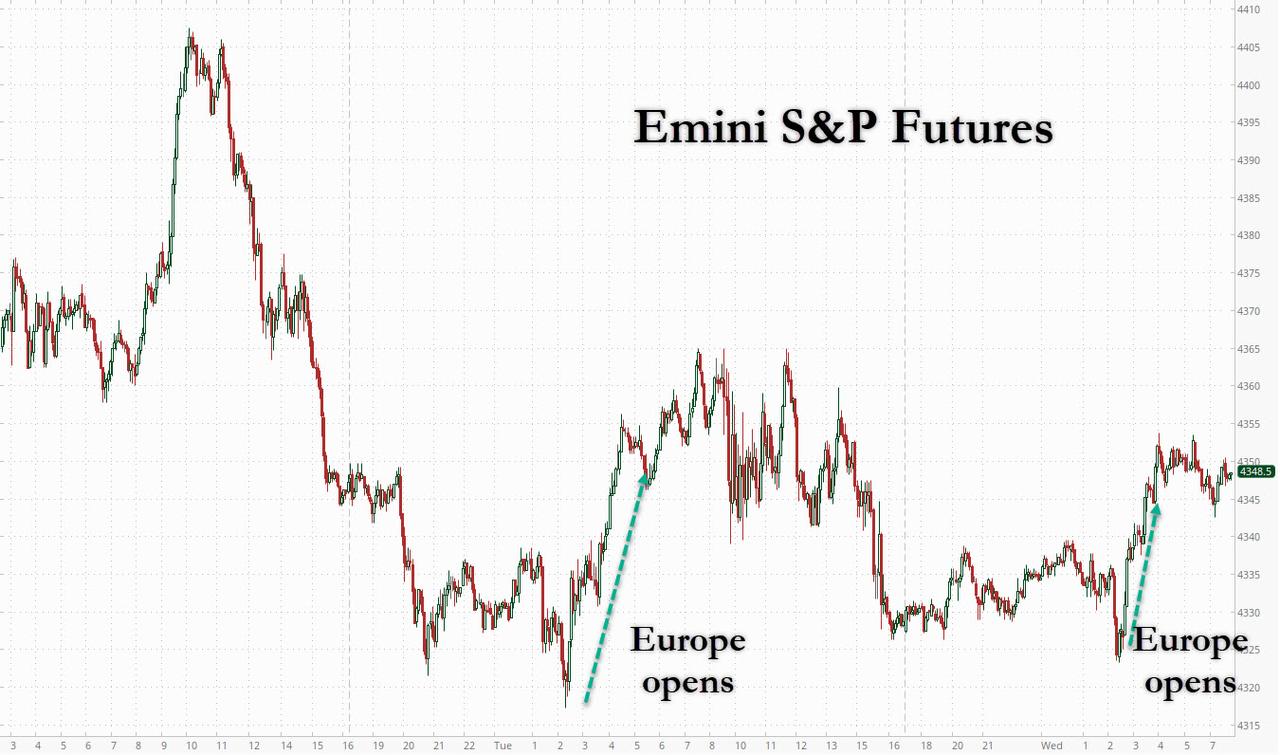
ZeroHedge reports, “For the second day in a row, an overnight slump in equity futures sparked by concerns about iPhone sales (with Bloomberg reporting at the close on Tuesday that iPhone 13 production target may be cut by 10mm units due to chip shortages) and driven be more weakness out of China was rescued thanks to aggressive buying around the European open. At 800 a.m. ET, Dow e-minis were up 35 points, or 0.1%, S&P 500 e-minis were up 10.25 points, or 0.24%, and Nasdaq 100 e-minis were up 58.50 points, or 0.4% ahead of the CPI report due at 830am ET. 10Y yields dipped to 1.566%, the dollar was lower and Brent crude dropped below $83.

JPMorgan rose as much as 0.8% in premarket trading after the firm’s merger advisory business reported its best quarterly profit. On the other end, Apple dropped 1% lower in premarket trading, a day after Bloomberg reported that the technology giant is likely to slash its projected iPhone 13 production targets for 2021 by as many as 10 million units due to prolonged chip shortages. ”


VIX futures are in a consolidation mode, neither going higher nor lower than yesterday’s range.  The Cycles Model calls for a strengthening VIX over the next two weeks.  Today’s expiring options show a preponderance of open interest in puts up to 22.00,, its Max Pain level.  Above that level, today’s expiring options support the longs.


TNX is rising this morning, but no new highs.  Today is day 259 of the old Master Cycle, so there may still be an extension of the old Cycle.

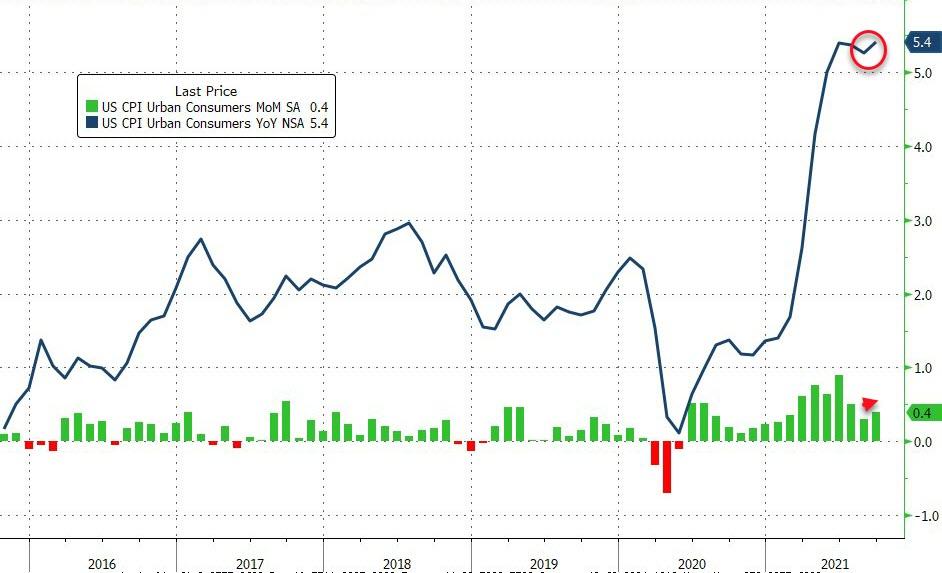
ZeroHedge comments, “Having slowed for two straight months, whisper numbers predicted a slightly hotter than expected September CPI (edging up to 5.4% YoY, slightly above the consensus of 5.3%) on the back of a re-intensification of supply-chain bottlenecks due to a combination of natural disasters and COVID disruptions in the US and Asia kept pressure on manufactured goods in September.

Headline CPI did indeed come hotter than expected  (+0.4% MoM vs +0.3% exp) with the YoY spike edging back up to +5.4%…That is equal to its highest since July 2008.”

Source: Bloomberg


USD futures declined to 94.25 overnight before bouncing to 94.54 this morning.   It appears that a correction may still be in the making with a potential slide down to the 50-day Moving Average at 93.08.  However, the pullback may be transitory, with strength reappearing early next week.


Crude oil futures cotinue to consolidate above the Cycle Top support at 78.92.  The Master Cycle high appears to have been made on Monday with a potential 5-6 week decline.  There may be some incentive to keep crude prices high due to options and futures expiration on Friday.  But the damage has already been done.  A sell signal lies beneath the Cycle Top support.

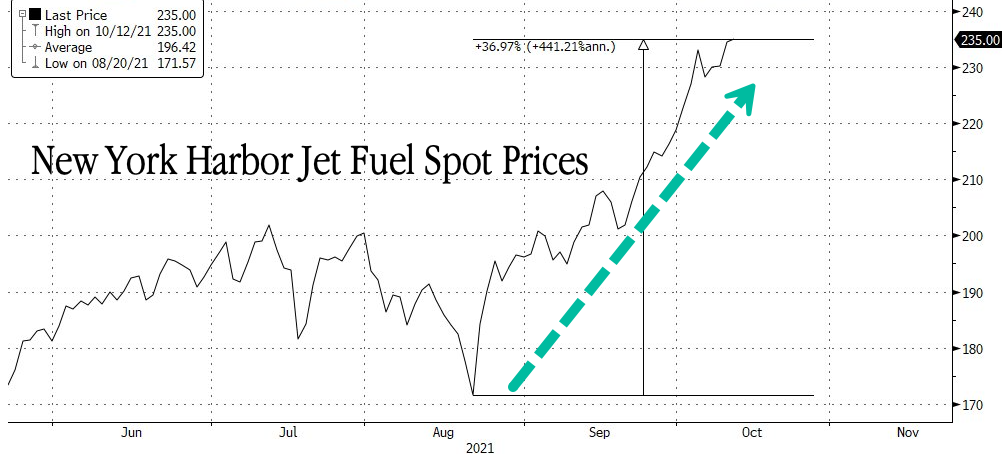
ZeroHedge explains, “Delta Air Lines Inc. delivered a profit in the third quarter but warned soaring jet fuel prices might result in an unprofitable fourth quarter.

Since August, spot prices for New York Harbor Jet Fuel have risen 37%. Delta expects fuel prices between $2.25 and $2.40 a gallon in the quarter, up from $1.94 in the third.

Fuel costs accounted for 20% of Delta’s adjusted operating expenses in the third quarter. Soaring costs are “going to be a limiter on our ability to post a profit in the quarter. At these current fuel levels, it looks like we’ll have a modest loss,” CEO Ed Bastian said. ”


Posted in Published | 1 Comment

October 12, 2021

1:35 pm

Today’s action in the TNX may have confirmed last Friday’s Master Cycle high.  The Cycles Model now suggests a possible 5-week pullback in bonds.  This may be due more to a knee-jerk reaction to a sell-off in stocks rather than a ligtening of inflationary pressures.

ZeroHedge observes, “It appears that sudden drop in indirect demand for today’s 3Y auction 90 minutes ago was a false alarm, because moments ago the Treasury sold $38BN in 10Y paper in what was for lack of a better word, a stellar auction.

Stopping at a high yield of 1.584%, the auction stopped through the When Issued 1.590% by a generous 0.6bps. This was the sixth consecutive 10Y auction that has stopped through. That said, the high yield was also well above last month’s 1.338%, and the auction cleared at the highest yield since May’s 1.684%.

The bid to cover of 2.58 was virtually unchanged from last month’s 2.59 and was above the recent average of 2.50.”


1:17 pm

SPX slipped beneath the 100-day Moving Average (not shown) at 4362.50 today as it gingerly looks for the next level of support.  The Lip of the Cup with Handle is at 4306.00 and the 2-hr. Cycle Bottom at 4292.97 provide the next level from which a bounce may occur, or not.

The NYSE Hi-0Lo opened at 9.00 and rose to 118.00 during the mid-day surge, then fell back to 55 at the current level.  This is not a good sign.  The negative action on the Hi-Lo is telling.  The Cycles Model says something negative is brewing as the VIX comes out of a Trading (minor) Cycle low.  SPX may be entering a panic Cycle lasting until early next week.  Market watchers suggest stocks could go either way, with the worst of all possible outcomes beneath 4300.00.

ZeroHedge remarks, “Another day, another abrupt reversal in stocks which bounced overnight only to slide the moment markets opened for trading, suggesting some latent weakness in technicals. Just how big is this weakness is what bulls want to know.

As we discussed earlier this week, with payrolls in the rearview mirror and the next major catalyst not due until the FOMC meeting next month, technicals have taken over and as SpotGamma writes this morning, “a move back to 4400 is just as easy as a move to 4300″ but the the key factor for today’s trading is waiting for implied volatility (VIX) to tilt and signal market direction (vol down, market up/vol up, market down).”

Until that happens, the market remains trapped between and trying to find “fair value” between the large gamma strikes of 4300 & 4400. According to Spotamma, due to the negative gamma position (zero gamma is currently at 4,427) markets are not sticking to one of those strikes (i.e., no +gamma pin close to spot), “and so markets just bounce back and forth between large options strikes.” Furthermore, “when the market is dominated by puts things are much more volatile due to more frequent hedging adjustments (puts sensitivity to vol).”


8:00 am

Good Morning!

After yesterday’s 61.4% retracement of last week’s sell-off, the decline resumed.  Overnight futures made a low of 4327.60 before an early morning bounce retraced 40%  of yesterday’s decline.  We are now witnessing another bearish cross as the mid-Cycle support/resistance 4438.55 is about to decline beneath the 50-day Moving Average at 4438.04 today.  The Cycles Model also implies that a panic cyle may have begun with three trending strength indicators flashing red between now and Friday.

ZeroHedge reports, “US equity-index futures erased earlier declines, rebounding from a loss of as much as 0.8% helped by the start of the European session and easing mounting concerns about stagflation from rising energy prices, signs of widening regulatory scrutiny by China, and the upcoming third-quarter earnings which is expected to post a sharply slower pace of growth and beats than recent record quarters. At 730am ET, Dow e-minis were up 5 points, or 0.1%, S&P 500 e-minis were up 7.25 points, or 0.16%, and Nasdaq 100 e-minis were up 46.75points, or 0.31%. Oiil rose 0.3% to $83.86/bbl while the dollar dipped and 10Y yield drifted back under 1.60%.

Gains in tech stocks kept Nasdaq futures afloat on Tuesday, while energy names rose as Brent resumed gains, trading around $84/bbl on expectations that a power crisis from Asia to Europe will lift demand and tighten global balances. Higher oil prices and supply chain disruptions have set off alarm bells for businesses and consumers ahead of the third-quarter reporting season that kicks off on Wednesday with JPMorgan results.  “We believe that market participants could stay concerned over high energy prices translating into further acceleration in inflation, and thereby faster tightening by major central banks,” said Charalambos Pissouros, head of research at JFD Group.”


VIX futures rallied to 20.81 before settling back under 20.00.  The short vol trade is losing steam.  Thus an important tool in propping up the SPX is losing ground.  The Cycles Model suggests a fairly steady march to a Master Cycle high during the week of October 25.

ForexLive observes, “The VIX has been hovering around the 20-21 region so far today.

The VIX has been a great shibboleth for testing whether stocks will rise or fall and a quick barometer on the risk tone. If we move, and stay above 21, then expect equities to keep falling. If we move below, and stay below 20, expect stocks to rise.”
TNX appears to be consolidating after Friday’s (day 254) high.   Today is day 258.  There is a good probability of yet another probe higher before the end of this Master Cycle.  However,  the retracement may be brief, as trending strength grows in the next two weeks.  

ZeroHedge observes, “Some that once was in Risk Parity is lost…That balanced equity bond portfolio ain’t what it used to be. The bond sell-off in Q3 due to sticky inflation and more hawkish comments from the Fed and BOE has started to narrow the gap between equities and bonds – the S&P 500 had it’s first 5% draw-down while the usual savior, treasuries, failed to protect as US 10 year yield spiked. While the S&P 500 draw-down still is relatively small, the combined equity and bond sell-off has weighed more on 60/40 portfolios and our beloved Risk Parity. Let’s have a look.”


USD futures made a morning high of 94.52 (thus far), matching the September 30 high.  The rally appears to be corrective, allowing a brief pullback to complete what may be a shallow retracement.  The Weekly chart allows for a considerably higher probe in Primary Wave [2] once the corrective measures are finished.


Crude Oil futures made an overnight low of 79.47 as a new Master Cycle takes hold.  The bounce out of the low did not make it to a breakeven with the close.  Brent oil is still taking a hit, but US futures are easing.  All attention is on Europe where a potential polar vortex may hit the U.K. later this month.

Reuters reports, “Oil rose towards $84 a barrel on Tuesday, within sight of a three-year high, supported by a rebound in global demand that is contributing to energy shortages in big economies such as China.

With demand growing as economies recover from pandemic lows, the Organization of the Petroleum Exporting Countries and allied producers, collectively known as OPEC+, are sticking to plans to restore output gradually rather than boost supply quickly.

“OPEC+ will push ahead with its cautious approach to supply in the year-end period. Set against this backdrop, oil bears will remain in hibernation mode,” said Stephen Brennock of oil broker PVM.”

OilPrice.com observes, “What is happening in Europe—including the UK, by the way, one of the most active energy transitioners—right now is a cautionary tale of magnificent proportions.

  •  Europe was in no particular rush to top up its gas reserves at the time, and neither was Asia.
  • The quick deterioration in the energy situation in Europe should make anyone planning major energy system overhauls think twice before following the exact same scenario that Europe did.


Posted in Published | Comments Off on October 12, 2021

October 11, 2021

11:05 am

Theepochtimes comments on food prices, “Food prices across the world have risen to their highest levels in a decade on the back of tightening supply conditions coupled with robust demand, according to the Food and Agriculture Organization of the United Nations (FAO).

The FAO’s food price index, which measures world food commodity prices, has surged by 32.8 percent in the 12 months through September, coming in at a reading of 130 points, a level not seen since 2011. On a month-over-month basis, the index rose 1.2 percent.

Accounting for the bulk of the rise in the index were higher prices of most cereals and vegetable oils.”


10:50 am

SPX made a 61.4% retracement of Friday’s decline and appears to be stalled.  Normally a Fib rally may be attributed to short covering and not much else.  There seems to be little incentive to go higher.  VIX also tested its low at 18.20 , but did not go beneath it.

ZeroHedge remarks,  “Something’s different this time.

For the first time since the collapse in March 2020, the S&P 500 has failed to rebound back to new highs after testing its key uptrend technical levels…

Source: Bloomberg

So what happened?

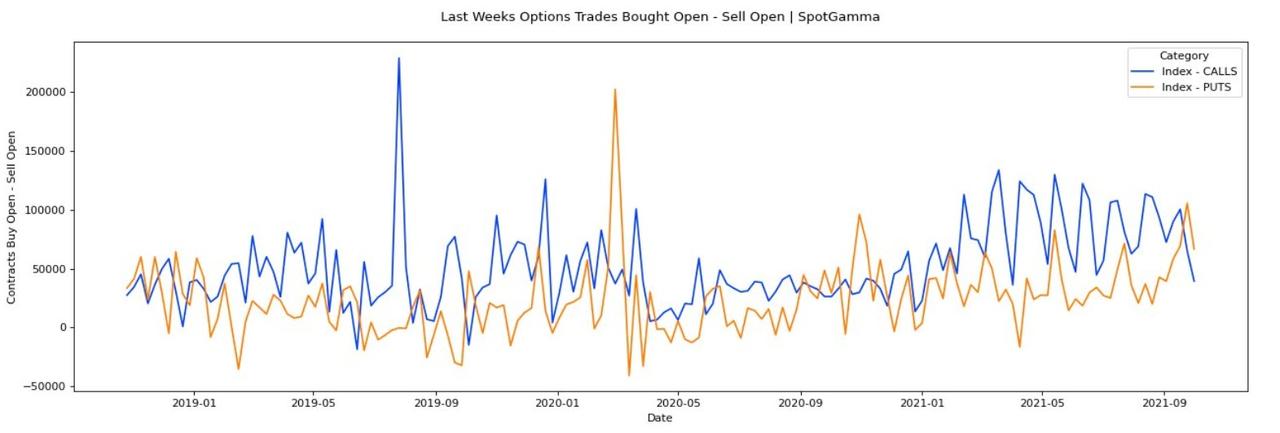
SpotGamma notes that the OCC data we collect offers some insights into what happened last week. According to this data, Index call options were sold to open in pretty strong size (top chart, blue line). Along with that there was some light put options shorted (orange line), but much less aggressively that in months past.

Source: SpotGamma

For months the default reaction to any selloff in markets was to short volatility (with the recovery time of any dip in the market measured in hours).

Off of the debt ceiling punt last week there was a snap-back rally in which very short dated options (1-3 days to expiration) were sold but nothing “real” (ie larger, longer dated) moved.

It seems like traders used Thursdays rally to reposition long volatility/short markets.

The bigger takeaway is this: that reflexive short volatility trade has apparently left the building. We’ve viewed this reflexive vol shorting as a primary driver of markets in the short term. With this mechanism absent, the market seems unable to recover.”

8:20 am

Good Morning!

SPX futures slid beneath Sort-term support at 4381.18 this morning as the weekly options settled in the Max Pain zone.  A quick scan of the options expirations show that Max Pain lies at 4350.00 today, while it moves to 4375.00 on Wednesday and Friday’s monthly expiration.  That information may lead us to believe that the roller coaster in porices may continue this week.  However, the Cup with Handle formation may prove to be a “trap door” should prices fally beneath the Lip at 4306.00.

ZeroHedge reports, “While cash bonds may be closed today for Columbus Day, which may or may not be a holiday – it’s difficult to know anymore with SJW snowflakes opinions changing by the day – US equity futures are open and they are sliding as soaring oil prices add to worries over growing stagflation (Goldman and Morgan Stanley both slashed their GDP estimates over the weekend even as they both see rising inflation), fueling concern that a spreading energy crisis could hamper economic recovery (as a reminder, yesterday we had one, two, three posts on stagflation, showing just how freaked out Wall Street suddenly is).
Rising raw material costs, labor shortages and other supply chain bottlenecks have raised concerns of elevated prices hammering corporate profits while rising rates are suggesting that a tidal wave of inflation is coming. And while cash bonds may be closed, one can easily extrapolate where they would be trading based on TSY futures which are currently trading at a 1.65% equivalent.”


TNX futures are open this morning, but may close at the open of the cash market.  Today is day 257 in the Master Cycle, giving us another day or so of trading before the final high may be in.


VIX futures rose to a weekend high of 20.45, above the Ending Diagonal trendline again after Friday’s brief test of the 50-day Moving Average.  Wave [c] of 3 is projected to be at least double the size of Wave [c] of Wave 1.  The last “buy the dip” opportunity for the VIX may have assed on Friday.

On Friday ZeroHedge commented, “Time to revisit Friday VIX hedges?

The theme of VIX being the relativity more exuberant one continues. Note the gap between the VIX inverted vs Spoos widening further. VIX didn’t “buy” the late day fade yesterday, and is continuing down as the weekend effect kicks in.

VIX isn’t dirt cheap (yet), but given the various cross asset vols all showing huge moves over the past few weeks, we doubt VIX will drift much lower. Our take from yesterday is playing out according to plan:

“So far trusting VIX has been the accurate “bounce” take, but let’s see if they manage puking VIX even more into Friday.”


USD futures continue to consolidate near the Cycle Top resistance at 94.13.  The Current Master Cycle projects a potential low by mid-November.


West Texas Light Crude futures hit a weekend high of 82.17 before easing back.  I had originally put the Master Cycle high on Wednesday (day 266), but we may be seeing an extended high this morning (day 271).  If so, a corrective phase may begin, lasting through mid-November.  The Broadening wedge formation may be triggered in this decline.

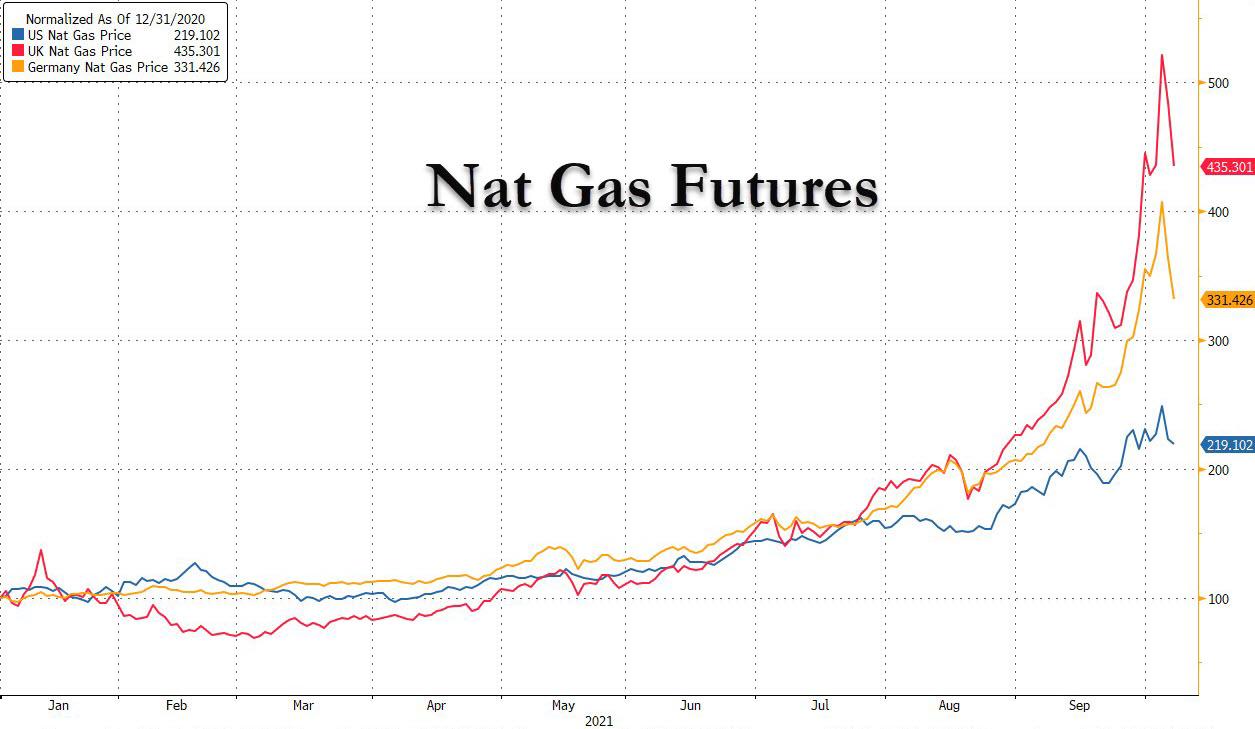
ZeroHedge observes, “The surge in natural gas prices in 2021 has put even crytpocurrencies to shame: US Henry Hub spot prices have been averaging around $6/mmbtu, up about 40% from early in August and a surge of around 200% relative to prices at the start of the year; prices in German and the UK are orders of magnitude higher.
The dramatic price increase has prompted questions how it will impact inflation prints in the near-term, both headline and core, and indeed as JPM economist Daniel Silver writes today, “this recent jump is notable and should boost consumer prices.”

ZeroHedge also worries, “Commodity prices are surging around the globe, so it should come as no surprise: Marine fuel is getting a lot more expensive. That’s bad news for ship operators on the cost side, and, in the container business, yet another headache for cargo shippers.

Marine bunker prices are “soaring,” said Alphatanker on Thursday. “This has not just impacted 3.5% [high-sulfur fuel oil or HSFO] but also 0.5% VLSFO [very low sulfur fuel oil].”

“There are expectations that crude, and therefore marine fuel, could move higher in the coming weeks as oil markets tighten further,” warned Alphatanker, adding, “This will undoubtedly clip gains in tanker earnings.”

All ship categories, not just tankers, are taking a cost hit. On Thursday, the S&P Global Platts T4 index estimated that a Capesize (a dry bulk ship with capacity of around 180,000 deadweight tons) burning VLSFO was spending $24,596 per day on fuel.”


The GSCI Ag Index continues to consolidate above all supports as it relieves its overbought condition.  Thee is a possible Trading (minor) Cycle lw due at the end of the week, but the longer view is for the rally to continue through mid-December.  The following articles give us pause to consider just how far food prices may rise.

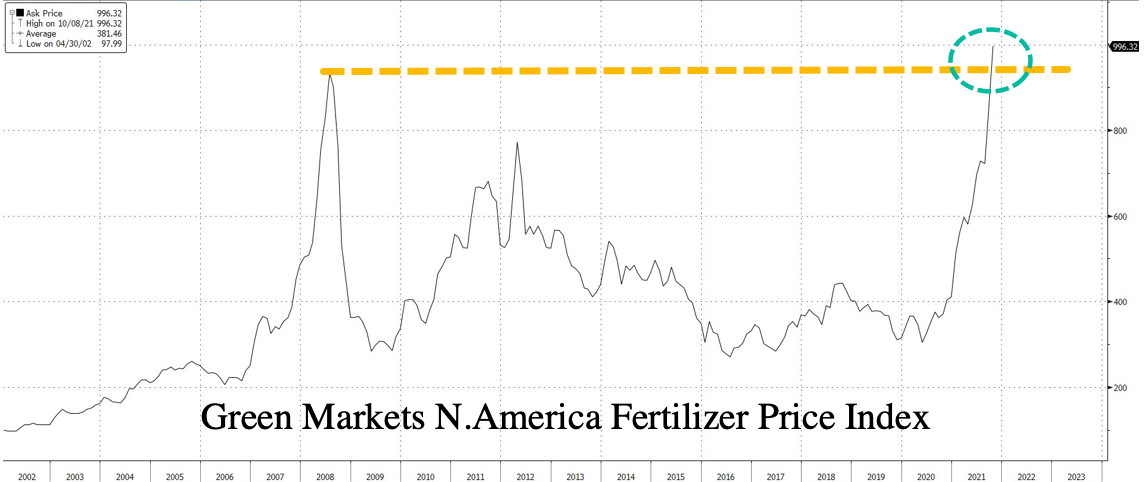
ZeroHedge notes, “Fertilizer prices have risen to a record high in North America, threatening to boost food inflation even higher. Nitrogen products are increasing due to the cost of natural gas, which is used in the manufacturing process.

The Green Markets North America Fertilizer Price Index soared to a record high last week of $996.32 per short ton.

The fertilizer market has been roiled by hurricanes, plant shutdowns, sanctions, and shortages of natural gas in Europe and China, pushing nutrient prices sky-high, which will raise the cost of production for global farmers. Here are global fertilizer prices zooming higher: ”

ZeroHedge also notes, “Americans are accustomed to a bowl of cereal as their go-to breakfast meal is about to experience a price increase because of rapid food inflation.

This year, a devastating drought in North American oat fields has resulted in the lowest harvest for the cereal grain in years, pushing prices to record highs, a warning sign that breakfast inflation is imminent.

Scorching heat waves in Candian oat fields slashed production to an 11-year low. Canada, the world’s biggest exporter, ships most of its oats to the US, its largest consumer.

The result so far has been a new record high in oats futures trading on the CME. The sudden spike in prices has yet to ripple through supply chains to affect consumers, though that will be coming.
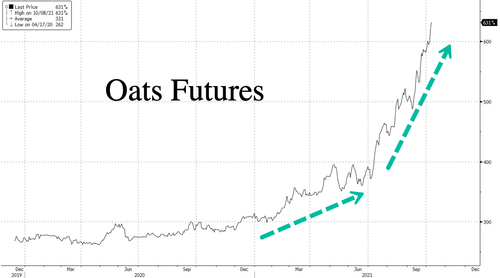
According to Bloomberg, “the situation for North American farmers was so dire in the summer that many cut their losses and harvested damaged plants to be sold as feed for animals.”

What this means for consumers is that dwindling supplies and record-high prices will soon affect foods like cereals, oatmeal, and granola bars, all popular breakfast items.”


Posted in Published | Comments Off on October 11, 2021