November 12, 2021

1:02 pm

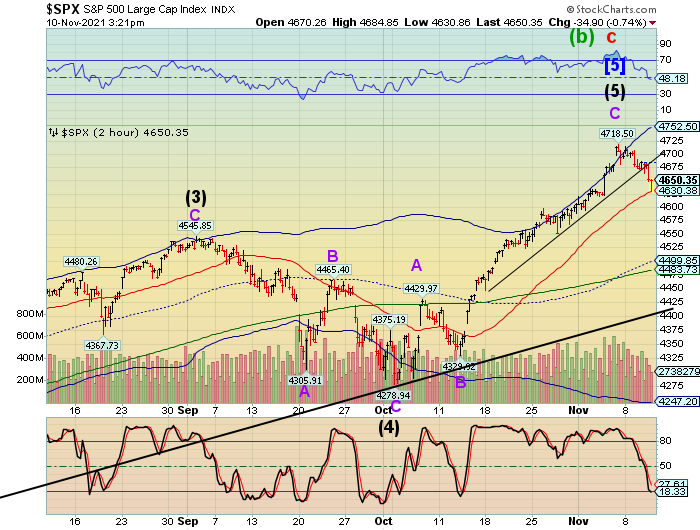
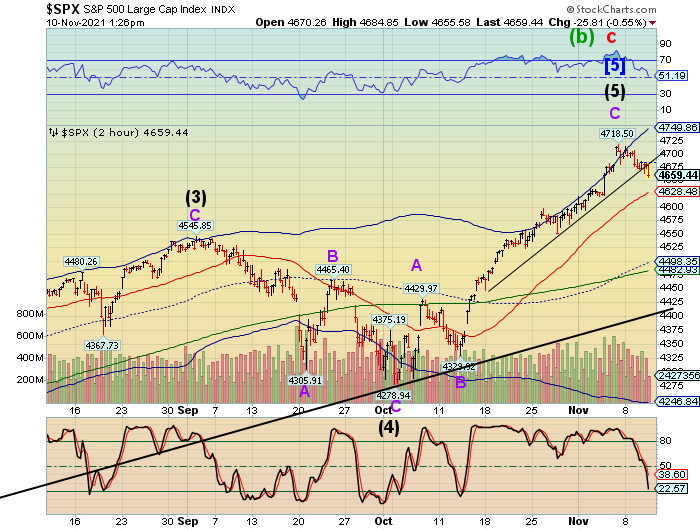
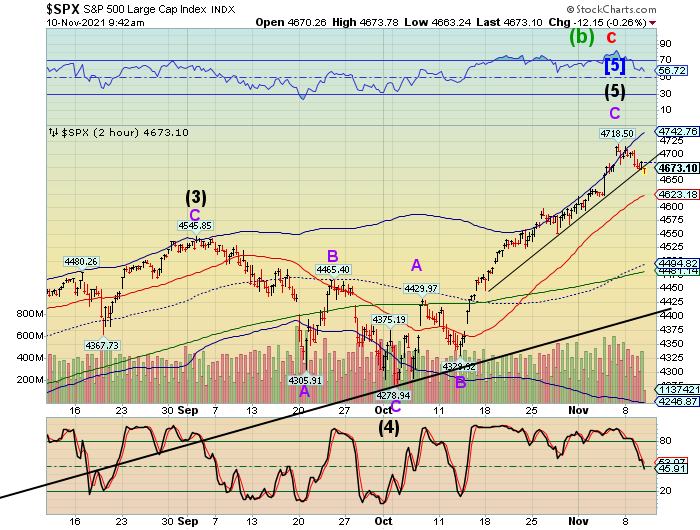
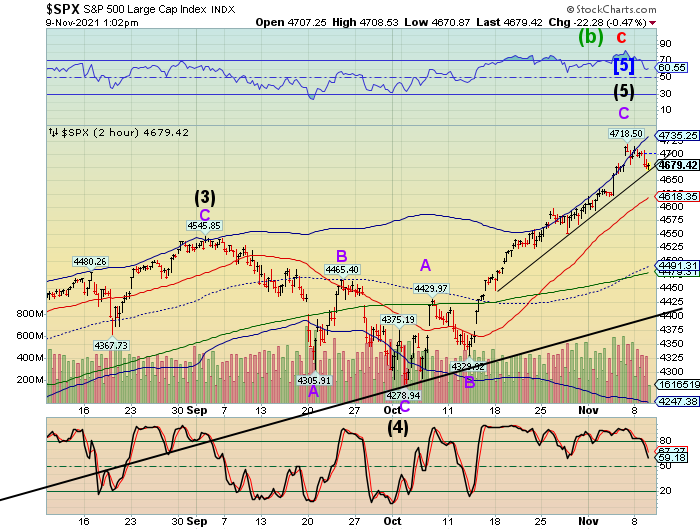
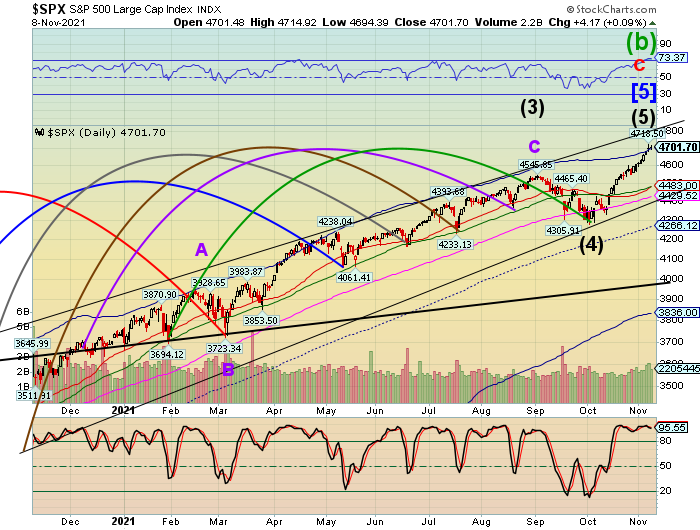
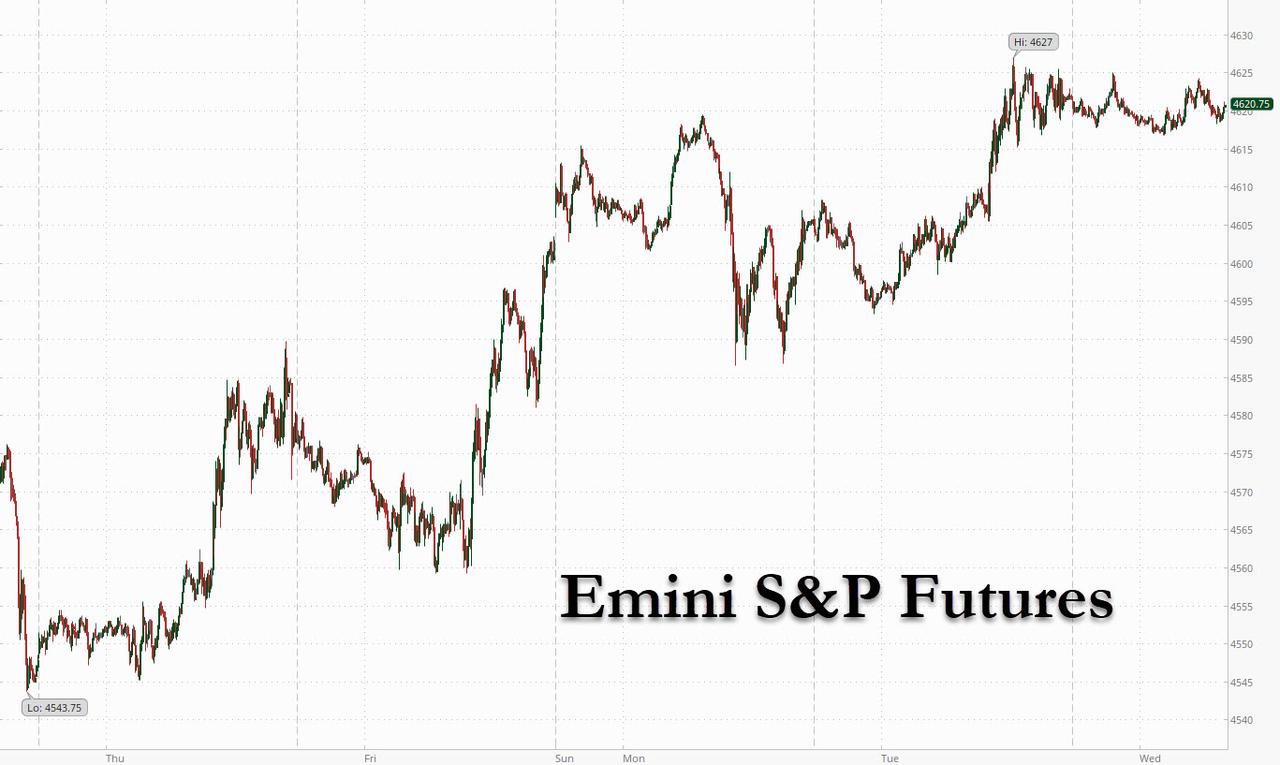
The SPX has reached one of its possible retracement values where Minute Wave [c] is equal to Wave [a] at 483.00.  However, the Elliott Wave structure may not be complete and the 61.8% retracement is at 4685.02.  In addition, Wave (v) of [c] is not yet complete.  That calculation posits a top near 4687.00 sometime before 3:00 pm (hourly Cycle).  The next support appears at the 50-day Moving Average at 4495.00.  Good luck and good selling!

RealInvestmentAdvice observes, “Is cash a good hedge?” It’s a focus of a recent article discussing “fast” versus “slow” risk which examined the financial impact on equities and cash over long-term periods. To wit:

“The simplest analogy to differentiate between fast risk and slow risk is heroin vs. cigarettes. Heroin is a fast risk. Cigarettes are a slow risk. Heroin tends to kill people quickly (especially in the event of an overdose), while cigarettes tend to kill people slowly.

Stocks have lots of fast risks, but little slow risks. The S&P 500 could drop 20% tomorrow, but 30 years from now it’s likely to be much higher than it is today. On the other hand, cash has lots of slow risks, but little fast risks. Next year your dollar should be worth about the same as it is worth today. But 30 years from now? Not so much.” – Nick Maggiulli

The analysis is correct. The probability of being down 5% during a 20-year period is zero.”


7:55 am

Good Morning!

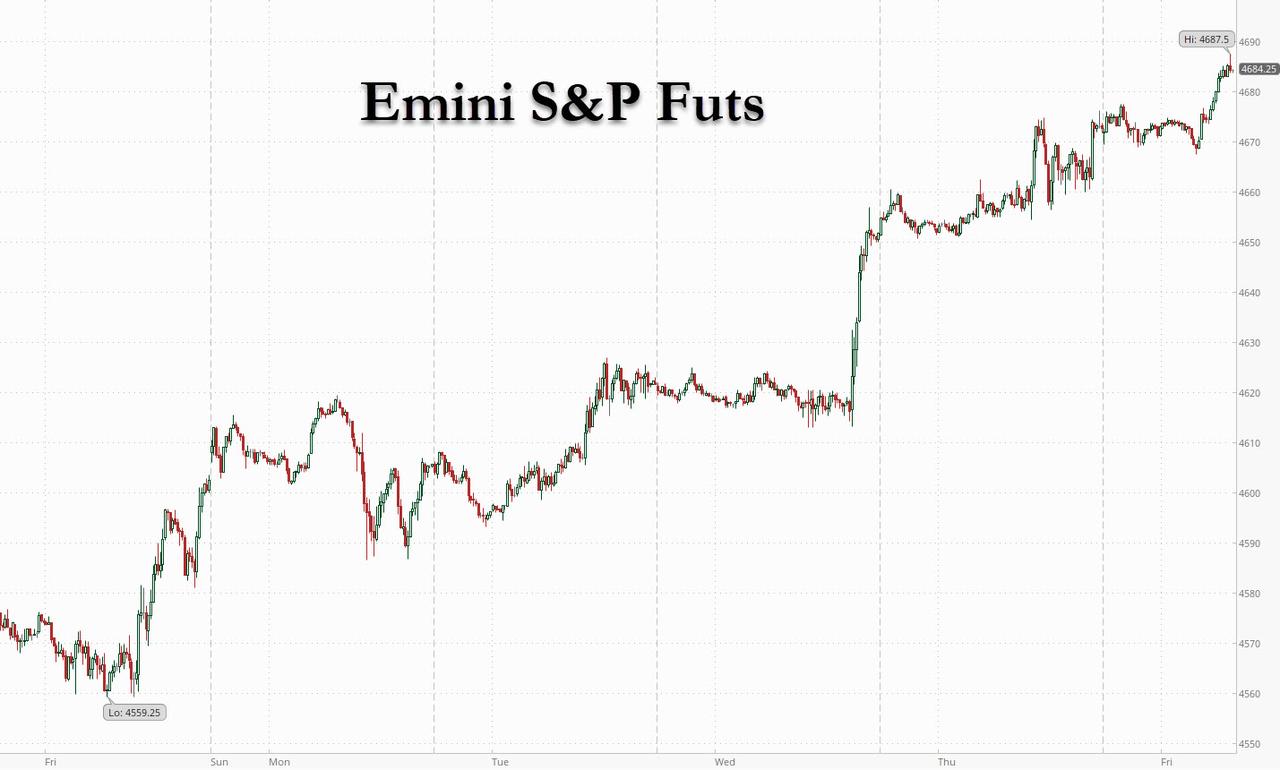
SPX futures ran up to the Max Pain level at 4665.00 in the overnight session.  However, it may not be able to maintain it.  This run-up may have been used by dealers to unload some longs, as there appears to be a drift toward negative gamma in today’s options expiration.   Short-term support is at 4637.00, where open interest in spy  puts (at 464.00) is 29,497 contracts to calls at 8,449.  A breakdown beneath that support may be disastrous.

ZeroHedge reports, “U.S. equity index futures were slightly up at the end of a volatile week, trading in a narrow 20 point range for the second day in a row, while Treasuries resumed declines in response to the recent shock inflation data from the world’s largest economies.

Contracts on the three main U.S. gauges were higher, with Johnson & Johnson rising in premarket trading after saying it will split into two companies, while tech stocks again led gains at the end of a week scarred by deepening concerns over prolonged inflation. All the major U.S. indexes were set for a more than 1% weekly drop, their first since the week ended Oct. 1, as hot inflation numbers sapped investor sentiment and halted an earnings-driven streak of record closing highs. At 7:15 a.m. ET, Dow e-minis were up 106 points, or 0.3%, S&P 500 e-minis were up 8.5 points, or 0.18%, and Nasdaq 100 e-minis were up 40.25points, or 0.25%.”


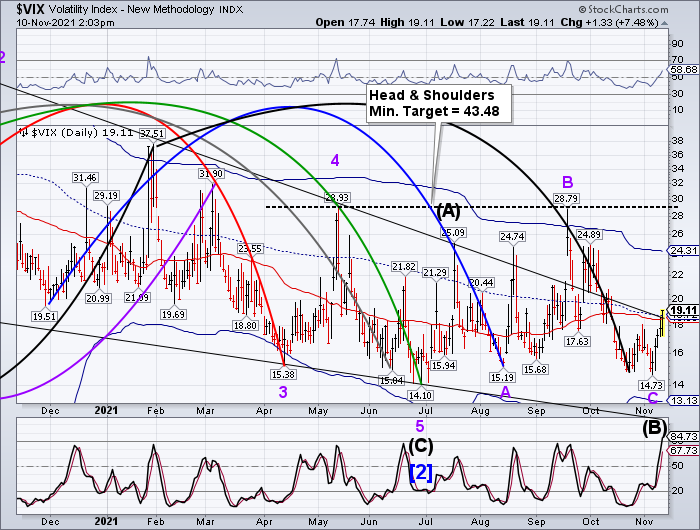
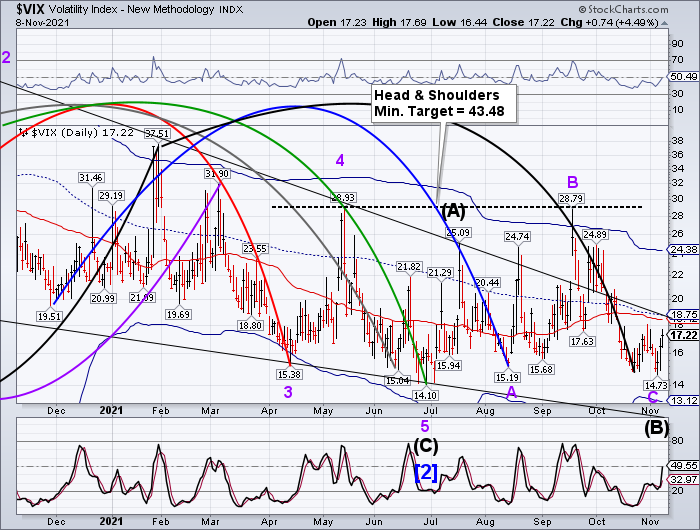
VIX futures remain range-bound beneeath its triple resistance at 18.69.  VIX has made a 52% retracement of its rally from the Master Cycle low.  The next Master Cycle interval appears to arrive during the November options expiration, so this may be a very active month.


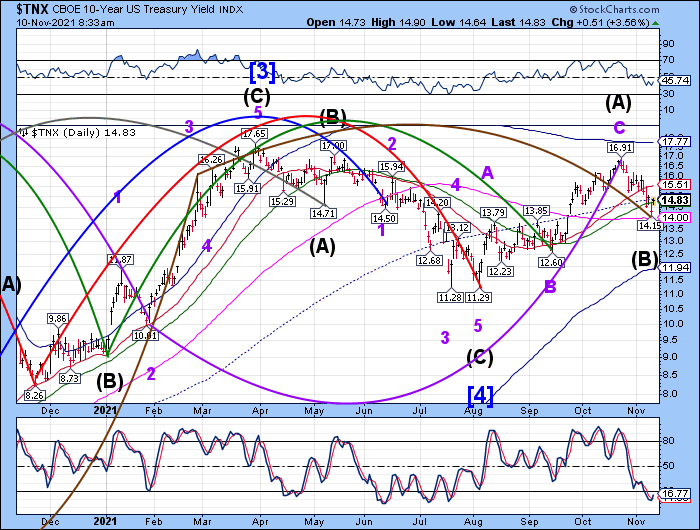
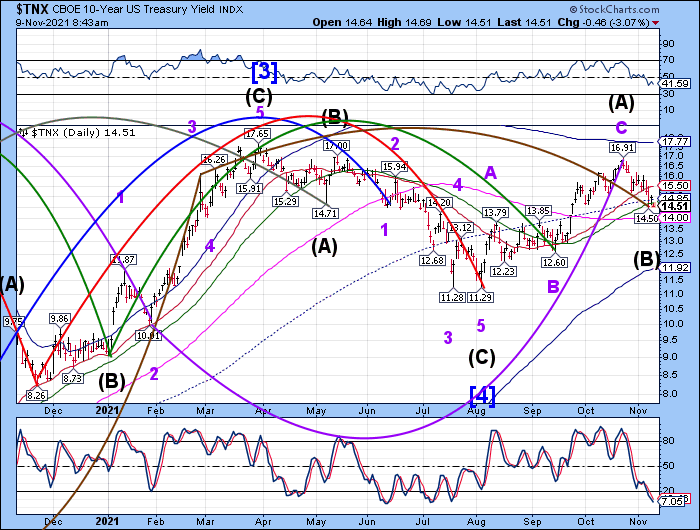
TNX remained above its Intermediate-term support at 15.59 over the Veterans Day break.  The rally is likely to continue with only short pullbacks through the January options expiration.


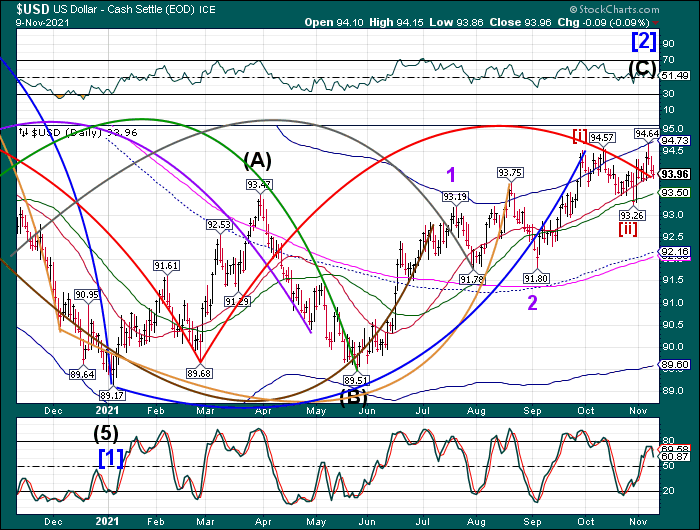
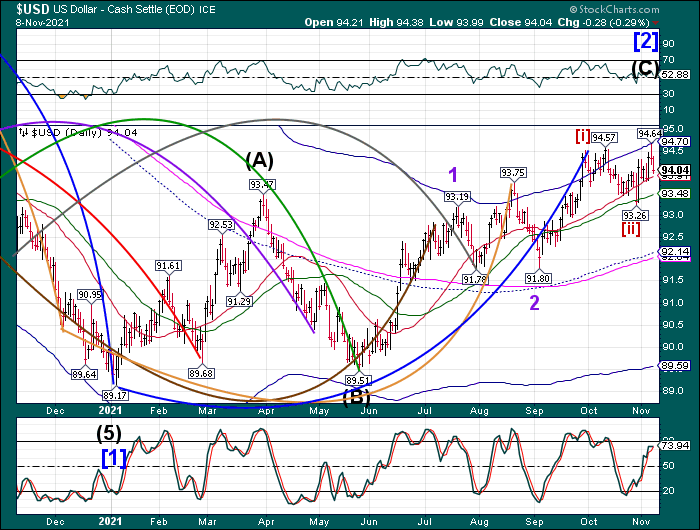
USD futures pulled back to a morning low of 95.09 as it consolidates after two days of gains.  It may pull back to the Cycle Top support at 94.82 before probing higher.    This activity is mirroring a small pullback in TNX, as well.  However, trending strength may return today or over the weekend.  A possible target may be the 61.8% retracement of the decline from the March 2020 high at 103.96 at 98.30.  This Master Cycle may have as long as three months to accomplish this.


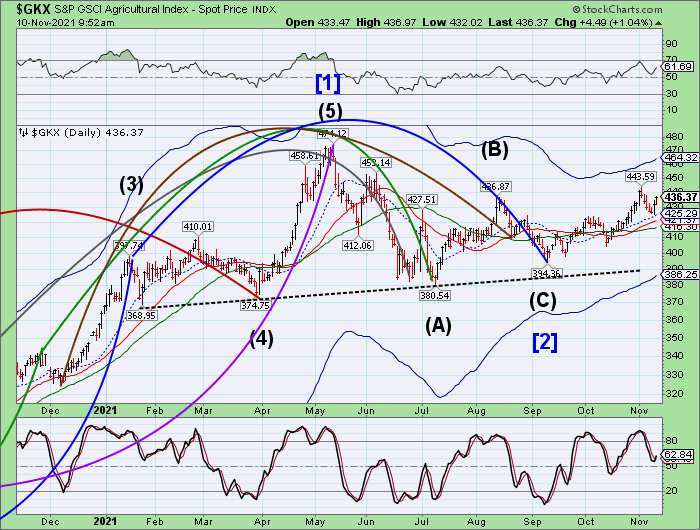
The GSCI Ag Index continues its rally, gaining strength as it approaches November monthly options expiration.  It is on shcedule to continue its rise through mid-December.

ZeroHedge observes, “The latest CPI figures from the U.S. this week showed meat prices are rocketing higher. Consumers are wondering when will rapid food inflation end. The world’s largest meat processor warned that labor shortages are crimping production growth, pushing prices higher, according to Bloomberg.

Brazilian company JBS S.A. has meat processing plants worldwide. One of its challenges is labor shortages in every developed country, resulting in limited production and increasing costs.

On Thursday, Andre Nogueira, head of JBS SA’s U.S. division, said the problem is most severe Stateside as labor shortages are expected to persist into the new year. He said the lack of workers also impacts operations in Europe, Canada, and Australia.

“Labor shortages are holding back production growth,” Nogueira said. “This is a key issue for the industry.” He added the shortages weren’t cutting into current production capacity, but the lack of workers inhibits the company’s ability to expand output if needed.”


Posted in Published | Comments Off on November 12, 2021

November 11, 2021

11:02 am

A curious thing is happening here.  At about noon today, the SPX may complete its first declining Cycle and retracement in 30.1 hours (4.3 days).  It has been stopped at the 38.2% retracement value at 4664.55 and doesn’t seem capable of a further rally thus far.  If the Cycle timing is correct, we may see SPX tumble into negative territory at or shortly after noon today.  That is a sell signal with confirmation on a decline beneath 4630.86.  The aggressive sell signal was made yesterday at 4675.00.  Those of you who took it have been rewarded.  Now is the time to go short, as  the next support for the SPX may be the 50-day Moving Average at 4485.36.

Sadly, ZeroHedge remarks on the departure of a bearish icon of the last 10 years.  Is this a sign of the reversal?  Read on,”It was about four or five years ago that we dubbed Russell Clark (formerly of Horseman Global and more recently of Russell Clark Investment Management) the world’s most bearish hedge fund, and for a good reason: roughly a decade ago, Clark decided to take his fund net short – an unheard of event in an industry where despite the name, the average net exposure is well north of 100% – and while his market bias ebbed and flowed, it remained short for much of the past ten years.”


10:14 am

The NYSE Hi-Lo Index is down to bearish territory, opening at 15.00, but rising to a high of 33.00.  We will monitor this site to determine, if possible, whether a signal may be generated.


9:54 am

Today is day 259 in the Liquidity Master Cycle.  It may have another day to make its final high.  Otherwise, the high at 142.57 on November 3 may count as a truncated Wave 5 of (C).  I hate to discuss truncations, because they do happen, but often need verification before making that call.  this week may be the last chance for me to be wrong.  In the meantime, BKX has hovered beneath its Cycle Top at 140.63 for the past week.  This is the final piece of the puzzle to determine whether the reversal is real.

ZeroHedge warns, “President Biden’s Marxist nominee for Comptroller of the Currency – who said she wants to “end banking as we know it,” has just said the quiet part out loud, again.

Top banking pick Saule Omarova – who was born and educated in the USSR, earned the “Lenin” award, and has refused to turn over her thesis: “Karl Marx’s Economic Analysis and the Theory of Revolution in The Capital” – now wants to put millions of Americans in the energy sector out of a job.”


8:08 am

Good Morning!

SPX futures have risen to the 38.2% retracement value at 4664.34 this morning.  The ultimate retracment may go higher.  The 50% retracement level is 4674.88 and the 61.2% retracement level is at 4686.02.  Today is day 252 in the Master Cycle.  The top occurred on day 246 thus far.  Tomorrow’s options expiration comes into play today.  The Max Pain level is 4665.00 at which the payout to options speculators on both puts and calls is the least.   Negative options gamma starts at 4650.00, so the dealers and hedge funds can ill afford an “accident.”  Positive options gamma starts at 6700.00, with 33,592 calls vs. 7,488 put contracts.  It appears that tomorrow’s options expiration may be very painful for the bulls.

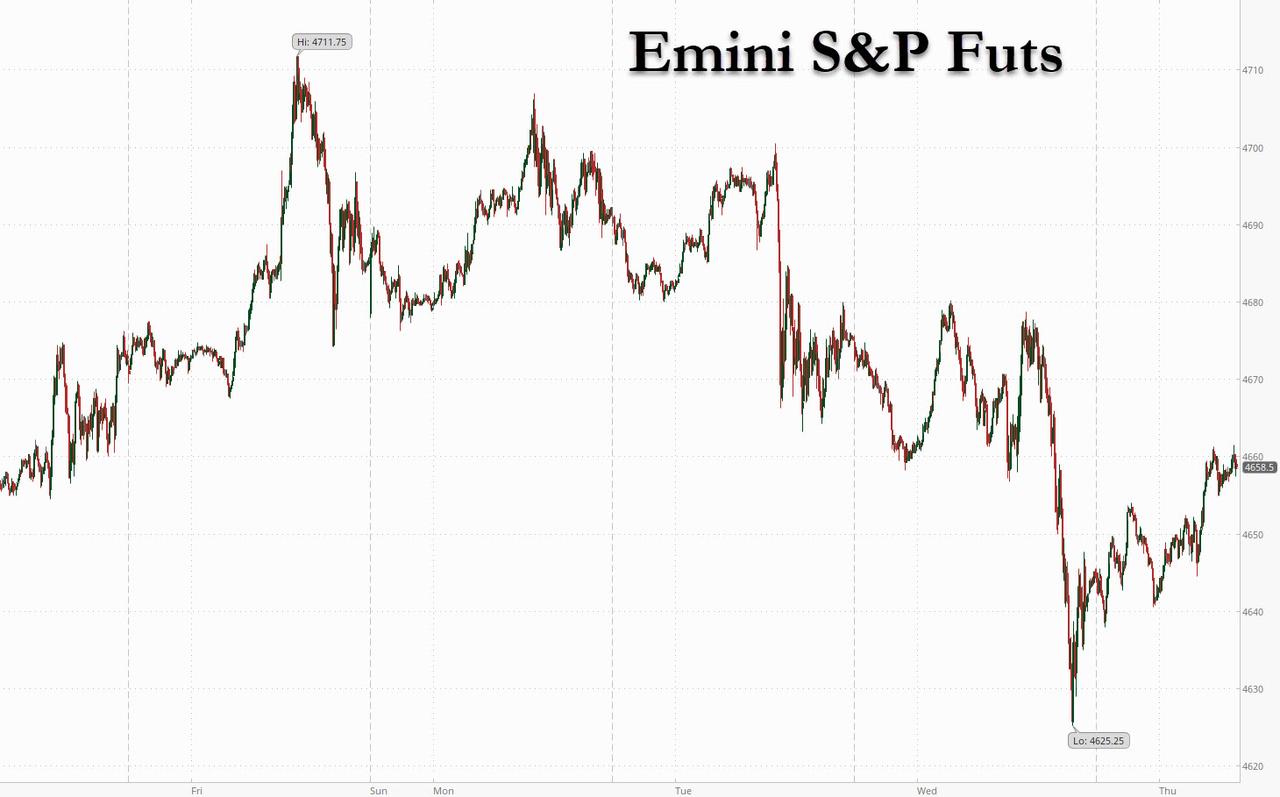
ZeroHedge reports, “US futures rose and European bourses once again rebounded from overnight lows, this time after concerns that scorching US and Chinese CPI and PPI prints will prompt central banks to tighten much sooner than expected. The bounce was aided by a surge in Chinese property developers which booked their best two-day gain in six years, joined by a jump in technology stocks, as investors speculated Beijing may soften regulatory crackdowns on the two industries. At 730am S&P futures were up 16.75 ot 0.36 to 4,658.50, Dow Jones futs were up 40 points or 0.11% and Nasdaq futures were up 97.50 or 0.61%. The dollar index rose and cash Treasurys are closed today for Veterans day.”


VIX futures pulled back to an overnight low of 17.73, losing some bullish support.    The NYSE Hi-Lo Index closed at 105.00, above the 50-day Moving Average at 93.10.  While the VIX has broken out above its resistance levels, the Hi-Lo must decline below 30.00 to give a sell signal.

TNX is closed for Veterans Day, but it had risen another .12 points after the close of the cash market.


The Shanghai Composite Index rose overnight to 3534.20, above the mid-Cycle resistance.  Teh November 10 low appears to be a Master Cycle low, suggesting a rally lasting up to two weeks before resuming its decline.   It is likely to rise to 3625.00 in a “flat” correction.

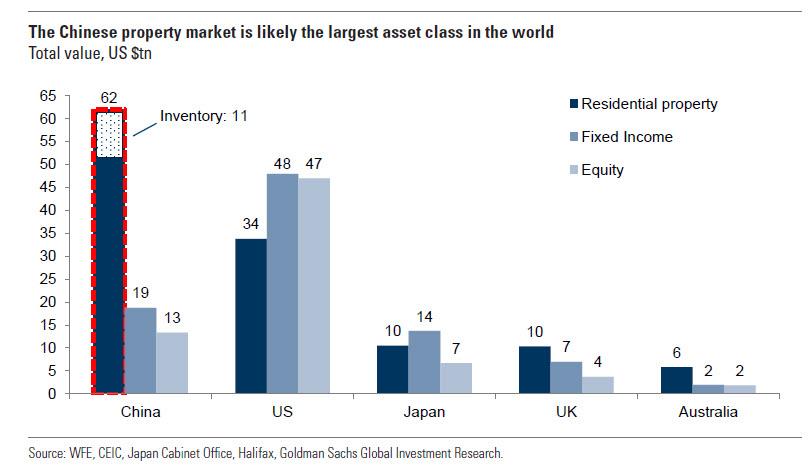
ZeroHedge observes, “Two months ago Wall Street was quick to conveniently ignore China’s property crisis, repeating that not only was the sudden hit to Chinese housing – the world’s largest asset class according to Goldman…

… not a “Lehman moment”, but that any contagion would be limited at best; at the same time central bankers – not just in China but around the globe – were quick to assure investors that a collapse by China Evergrande Group wouldn’t lead to a crash. As usual, Wall Street consensus (especially when coupled with soothing lies from central planners bankers) was dead wrong because now that the bond selloff has spread to China’s entire real estate sector and beyond, including healthy government-backstopped investment grade companies, concern is growing about the potential risk to the global financial system.”


USD futures rose to a new high at 95.10 after breaking above its prior high at 94.57 and its Cycle Top resistance at 94.77.  It has begun a period of “triple strength” as it continues the retracement of its decline from 103.96 in early 2020.


Posted in Published | Comments Off on November 11, 2021

November 10, 2021

4:15 pm

Should have bought those puts…

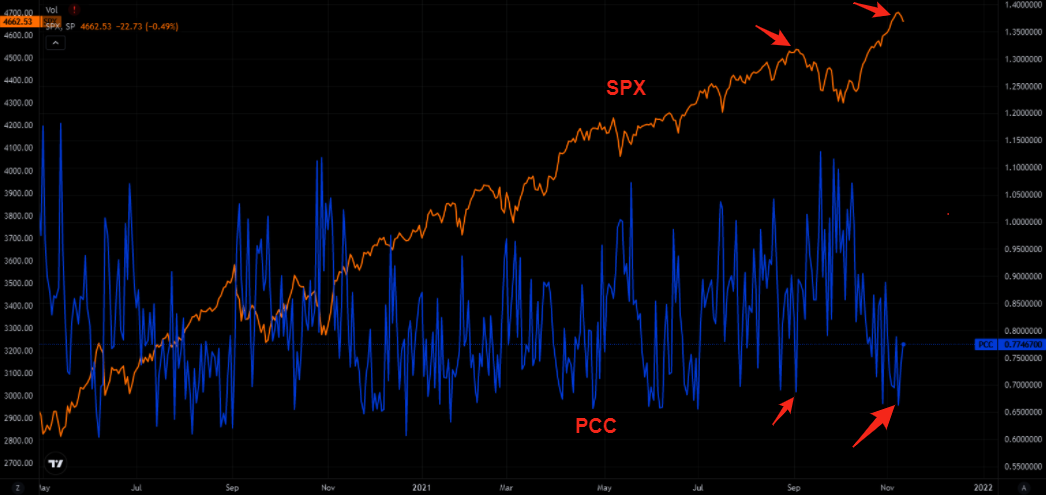
ZeroHedge remarks, “People hated puts when they should have loved them

We saw people puke puts just in time for the reversal.

Nothing new really, but it adds to the complex psychology of this market.

Source: Tradingview

Not only did they hate puts…

…they had to sell them short and load up on calls.

This is just a gentle reminder of one of the most important charts out there, if not the most important.

Greed has become so big, driving people into shorting puts and putting all that premium into calls.

Humans have come a long way, but greed and fear never changes…


3:22 pm

SPX entered negative gamma territory to hit Short-term support at 4630.00, but recovered to the Max Pain level, 4650.00, where the least amount is paid out for expiring options.  Now it’s time for that delayed retracement, possibly tomorrow.  Should it happen, we could see a rebound to the 61.8% retracement level at 4685.00.  However, the tension is on to keep the 4650.00 level through closing today.  Accidents can happen here, since the SPX is on such a tightrope.


2:02 pm

VIX just climbed above all three resistance levels at 18.71.  It may backtest resistance-turned-support and keep going higher.  It had only made a 35% retracement of its first rally off the bottom.


1:38 pm

This Morning I said “Something has to give” egarding TNX.  It may have just launched a “rampaging rally” that may last for the next 10 weeks!  The effort to squeeze the bond shorts may have just backfired.

ZeroHedge reports, “If the ugliest auction so far in 2021 was the disastrous 7Y sale back in February, which sparked a mini market meltdown in both bonds and stocks, then the just concluded sale of $25BN in 30Y paper was almost just as terrible. It was, in a word, catastrophic and since it is at the very end of the curve, one could almost argue it was even worse than the infamous 7Y auction.

Stopping at a high yield of 1.940%, the auction was slightly below last month’s 2.049%, but it was supposed to be far better, because while the When Issued traded at 1.888% the auction tailed by 5.2bps, which was the biggest tail on record for the 30Y tenor!

The bid to cover of 2.202 was far below last month’s 2.360 and below the six auction-average of 2.292. But it was the internals that were ugliest of all, with Indirects taking down just 59.0%, a collapse from last month’s 70.55% and far bleow the recent average of 64.3%. One has to go back to November 2019 to find a lower Indirect takedown. And with Directs also sliding to just 15.8%, the lowest since October 2020, Dealers were left holding on to 25.23%, the most since August 2020.”


1:24 pm

SPX is in the process of a complex decline that still has the probability of a retracement as high as 4700.00.  However, the option gamma turns negative beneath 4650.00.  Should that level hold, we may still see a retracement.  However, beneath 4650.00 all bets are off…

…VIX is still beneath resistance at 18.71.  This is a cautionary note to look for confirmation before getting whipsawed.


8:52 am

The GSCI Ag Index resumed its ascent from the mid-Cycle support at 425.29 yesterday.  Trending strength comes back this weekend and early next week.  This could be a big move.  Remember, the current Master Cycle lasts until mid-December.

EpochTimes reports, “With investors closely eyeing two major data releases this week on inflation—one on producer input costs and the other on consumer prices—Wells Fargo analysts say it’s unlikely sticker-shock-weary consumers will see relief as the persistent supply-side crunch will “keep fanning the flames on inflation in the near term.”

On Tuesday, the Labor Department will release data for October’s producer price index (PPI), which tends to front-run consumer inflation data as at least some production costs get passed on to consumers. Economists expect a year-over-year rise of 8.7 percent in the PPI inflation measure, which would be the highest reading in the history of the series. Last month’s PPI came in at 8.6 percent, a record high.”


8:42 am

SPX completed a declining impulse through the short-term trendline.  It is likely that it may rebound toward 4700.00 before resumig its decline.  This is the place to layer in some aggressive short positions, getting the best positioning you can.  The average investor is not concerned, yet.  He has seen this before and the market “has always gone back up.”  There is still a (diminishing) chance of a higher high, but   TNX has just broken above its final resistance at 14.85.


8:10 am

Good Morning!

SPX futures appear to be challenging the one-month trendline at 4675.00 by declining to 4664.60 this morning.  Since then it has bounced back to the trendline.  In today’s expiring options, the Max Pain (the least payout to options holders) remains at 4675.00.  While attempting to regulate the options payout, dealers and hedge funds may be inadvertently breaking down beneath an important technical support.  Today is day 251 of the Master Cycle.  Should a breakdown not occur in the cash market, the Cycles may allow a new all-time high later this week.

ZeroHedge reports, “For the third day in a row, early weakness in futures – in this case as a result of China’s soaring, record producer price inflation – reversed and spoos rose from session lows but were still down on the session as traders awaited inflation data due later on Wednesday. Treasury yields climbed and the dollar and cryptos rose. At 7:45 a.m. ET, Dow e-minis were down 47 points, or 0.12%, S&P 500 e-minis were down 10.25 points, or 0.22%, and Nasdaq 100 e-minis were down 68 points, or 0.42%.


VIX futures remained range-bound beneath its triple resistance at 18.73 this morning.  It is customary for a retracement to occur after the first impulsive wave from the bottom.  the 61.8% retracement may be as low as 16.20.  For those interested in going long the VIX (options and ETFs), this may present an opportunity to buy the dip.

ZeroHedge comments, “Having previously correctly called the current market meltup not once but twice (a torrid rally which finally took a breather today after matching the longest strecth of all time highs since 1997)…

… only to follow up with some shocked commentary as to the relentless meltup observed in this market over the weekend, on Monday Goldman trader Matt Fleury followed up with some even more hyperbolic (and floral) commentary, writing in a note that “traditional investing rules are being thrown out (NVDA; ~$750bn company going up 12% in a day, TSLA adding $350bn of mkt cap in a couple of weeks, BBBY going up 65% after hours on earnings, CAR 29 sigma move in a day).”

Pointing out the obvious, Fluery cautions that “this is a very difficult tape for market neutral strategies” and he expects that to continue. Meanwhile, right tails – i.e., meltup hedges – are far too cheap.”


TNX has risen above the 50-day Moving Average, but appears to be stopped at the mid-Cycle resistance at 14.85.  Confirmation of a buy signal awaits above the mid-Cycle line.  Today is day 258 of the current (or past) Master Cycle, suggesting yesterday’s low may be the bottom of the Cycle.  The gap between the CPI and the 10-year yield is widening dramatically.  Something has got to give.

ZeroHedge observes, “Following yesterday’s US PPI print at record highs, overnight we saw Chinese producer prices rising at their fastest pace in 26 years, and this morning’s US consumer price data was expected to show yet another non-transitory surge in inflation… but the actual surge was far bigger than expected.

US Consumer prices soared 6.2% YoY in October, way higher than the +5.9% YoY expected and accelerating from September’s 5.4% YoY – that is the highest since June 1982…”


USD futures rose to 94.43 this morning beginning a new Master Cycle after bottoming on day 257.   This rally has a distance to go.  For example, a 61.8% retracement of the decline from the March 2020 high at 103.96 would be 98.30.


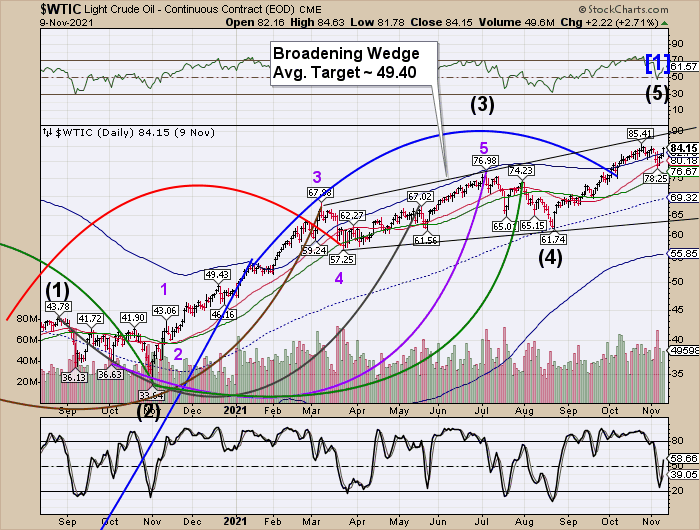
Crude oil futures are consolidating above the Cycle Top support at 82.79 as it gathers strength for its final probe to 90.00 or higher by the November options expiration.  The calls for $100.00 oil may be premature as the liquidity system may be breaking down.

OiPrice.com maintains, ”

  • OPEC+ will be very happy with where oil prices currently are and is unlikely to change its course anytime soon
  • The U.S. does have the ability to increase production, but U.S. shale does not have support from either the government or shareholders to boost production significantly
  • The two bearish variables that could drag prices down in the near term are a strong dollar and the continuation of inventory builds”


Posted in Published | Comments Off on November 10, 2021

November 9, 2021

1:13 pm

VIX is challenging its 50-day Moving Average at 18.46.  However, there is a triple resistance in very close range (18.74) that must be overcome to confirm the buy signal.   A breakout here would be nice, but there is usually a pullback from which a successful attack on resistance may be launched.  We are very close, but a pullback to 16.00 may be warranted.


1:00 pm

SPX is testing the trendline, currently at 4670.00.  Unfortunately, the structure may allow a probe higher, should the trendline not be broken.   Be aware that the decline in TNX may be a tool to push stocks higher as a last ditch effort to keep the markets liquid.  Remember, this is day 250 in the Master Cycle.  There may yet be some life in this rally.

ZeroHedge observes, “Until this morning’s little interruption, markets over the past week are evidencing a scramble for upside (created by single-name “Growth” stocks i.e. TSLA), as the persistent “wall of worry” of the past 1.5 yrs is again being hurdled and leading us to fresh Index all-time-highs.

As many freshly-minted stock trading gurus look on speechless as TSLA craters (finally) – which , rhymes a bit with last August’s broad Retail “gamma squeeze / Nasdaq Whale” phenomenon into the September “Delta unwind” crash thereafter (as “Gamma cuts both ways”) – Nomura’s Charlie McElligott has some thoughts on the current risk environment…”


12:54 pm

TNX has nearly gone the limit by mid-day.  Be prepared for a reversal.  Today is 257 of the Master Cycle, so the reversal may happen momentarily.

1:15 pm

ZeroHedge may have pointed out the turn, “With 10Y yields sliding all day, and painfully squeezing near-record duration shorts, as the market aggressively prices in the Fed’s upcoming policy error, today’s 10Y auction provided a brief respite for duration bears as the sale of $39BN in ten year paper was plain and simple ugly.

One day after a solid 3Y auction, the high yield on today’s benchmark auction stopped at 1.444%, well below October’s 1.584%, however it also tailed the When Issued by 1.2bps, which was the first tail since April.

The bid to cover was also ugly, dropping from 2.58 in October to 2.35, the worst print of 2021 (the lowest since Dec 2020), and well below th six-auction average of 2.54.

The internals, like yesterday, were a bit better with Indirects taking 71.0%, virtually unchanged from yesterday’s 71.1%, and with Directs taking down 13.8%, the lowest since August, Dealers were left holding 15.2%, or the most since July.”


8:00 am

Good Morning!

SPX closed again above the Cycle Top support at 4696.24.  However, the SPX futures appear to be challenging that support with a decline to 4687.60.   There is a minute trendline (shown in the 2-hour chart) under the last three weeks of rally ay 4675.00.   Should that trendline be crossed, the outcome may be a swift decline to the October 4 low.  That would be our aggressive sell signal, sinve the decline may be likely to also cross the larger, one year trendline.

Tomorrow’s options expiration are positive down to 4680.00, verifying the short-term trendline.  Friday’s options expiration is also positive at 4680.00 with 26,709 net call contracts at 4700.00.  Today is day 250 of the Master Cycle, leaving us in the reversal window.

ZeroHedge reports, “For the second session in a row, S&P 500 futures reversed earlier losses and traded flat after falling as much as 0.3% earlier in the run-up to today’s PPI report – the first of a couple of readings on inflation this week – as investors weighed the Federal Reserve’s warning that stock prices are “vulnerable to significant declines should investor risk sentiment deteriorate, progress on containing the virus disappoint, or the economic recovery stall.” US Treasury yields fell and the dollar index slipped for a third consecutive day following a late Monday report that Joe Biden interviewed uber-dove and Hillary Clinton fan Lael Brainard for the central bank’s top job, although prediction markets were not impressed. European stocks advanced for a ninth day, the longest streak since June while Asian shares drifted.”


VIX futures remained range-bound after a positive day yesterday.  The Cycles Model suggests growing strength with a possible “slingshot move” over the next 8 days.

RealInvestmentAdvice counsels, “As investors rush to pile into the stock market, there are 5-signs they may be getting too bullish. Such was a point we touched on in this past weekend’s newsletter:

“Every week it feels like we get a new headline about financial markets doing something unusual. Just this week we’ve had:“

  • A “squid game” crypto token falling 99.99% in a few minutes.
  • Tesla adding hundreds of billions of dollars in value over a deal with Hertz that hasn’t even been signed.
  • US stock markets hitting fresh all-time-highs.

“All of which begs the question: are we in a bubble?”

TNX is threatening Friday’s low at 14.50 this morning.  The Cycles Model suggests it may go as low as the 100-day Moving Average at 14.00.  Today is day 257 of the Master Cycle, suggesting the low may come in within the next two days.  Stay on the alert, as the reversal may be sudden and strong.

9:08 am

ZeroHedge reports, “US Treasury yields are tumbling across the curve this morning (despite a record high PPI print) with the long-end outperforming (30Y -6bps, 2Y -2.5bps)


ZeroHedge reported yesterday, “Unlike recent fireworks in the 2Y repo market which, pushed the note super special as traders scrambled to obtain physical cash against which they could deliver their shorts, and which led to an absolute blockbuster 2Y auction if for all the wrong reasons (as traders rush to cover their shorts into the auction) there was no such repeat action into today’s $56 billion sale of 3Y paper, and as a result today’s auction represented a far more accurate representation of demand on the short-end.

Here’s what we got: the 3Y auction priced at a high yield of 0.75%, the highest since Feb 2020, more than 10bps above the 0.635% last month and a 1 basis point tail, the biggest since April 2020.

The Bid to Cover was also disappointing, sliding from 2.356 last month to just 2.326, the lowest since April and well below the 2.441 six-auction average.


USD futures made an overnight low of 93.87, testing Intermediate-term support at 93.81.  However, it may go lower.  Today is also day 257 in the Master Cycle, which suggests the coming reversal in Treasury yields may also have the same affect on the USD.


Posted in Published | Comments Off on November 9, 2021

November 8, 2021

7:50 am

Good Morning!

SPX futures are positive, but no new high was made this weekend.   SPX closed Friday above its Cycle Top support at 4690.03, leaving it capable of going higher.  Today is day 249 of the Master Cycle which began at the March 4 l0w.  While the SPX is in the turn window, there may yet be time for another high this week.

ZeroHedge reports, “US futures rebounded from a modest overnight selloff as big industrial firms were supported by Friday’s passage of a $1 trillion infrastructure bill, while Tesla fell on Elon Musk’s plan to sell about a tenth of his stake after an impromptu Twitter poll suggested he “should” do what he likely already planned to do anyway. Oil, Bitcoin and treasury yields all rose while the dollar fell. At 745 a.m. ET, Dow e-minis were up 64 points, or 0.2%, S&P 500 e-minis were up 1.50 points, or 0.03%, and Nasdaq 100 e-minis were down 1.25 points, or 0.01%.”

ZeroHedge observes, “Thinking about options…

We are experiencing a “gamification” of options trading by retail. Few of the new “punters” understand derivatives, but they understand that things move quickly.

So far so good, but things could get nasty from an aggregate risk point of view. With options trading exploding again, there will be a lot of unmanageable options risks to consider, irrespective if the market moves higher or lower.

Poor liquidity and “gamma holes” could become a problem for dealers trying to manage “the other side” of the retail options trade.

Below are some of our recent posts on the current options (calls) trading mania.

Options mania is real

Retail is extremely active, and they love punting options. Below are a few stunning facts via Goldman’s Scott Rubner:

1. single stock option notional (140%) now exceeds single stock shares notional

2. over 70% of options traded have an expiry of two weeks or less (more in the 2,3,4 day range)

3. $904bn (Thursday stock option notional). This is largest single stock option notional traded of all time.”


Today is also day 249 for the VIX.  VIX futures probed to a weekend high of 17.28 and remains mildly positive.  The 50-day Moving Average may be coming within range at 18.40, with yet the mid-Cycle resistance at 18.78 to be overcome.  Virtually no one is buying puts, keeping the VIX at very low levels, so the VIX may be seen at lower levels this week.

ZeroHedge remarks, “Three weeks ago, when stocks were holding on to dear life – and key support levels – amid a wave of bearish sentiment which threatened to drag risk below its July lows, Goldman took the other side of the trade and said it expected a huge market meltup in the coming weeks, a call which it doubled down on one week later. In retrospect, the vampire squid was absolutely correct, with the S&P soaring by 400 points in the past month…

… in the process demolishing the wall of worry, even if the meltup was widely missed by professional speculators – many of them crushed by the turmoil in bond markets – who according to Bloomberg, were going risk-off in stocks, cutting leverage at the fastest pace in months as many bearish bets backfired.”


TNX ventured beneath the mid-Cycle support at 14.83 and the 50-day Moving Average at 14.65.  The next support appears to be the 100-day Moving Average at 14.00.  I have identified this move as an Intermediate Wave (B), often known as rogue waves.  Today is day 256 of the current Master Cycle.  This suggests that the 10-year yield may be rising again by the end of the week.


Posted in Published | 1 Comment

November 5, 2021

10:00 am

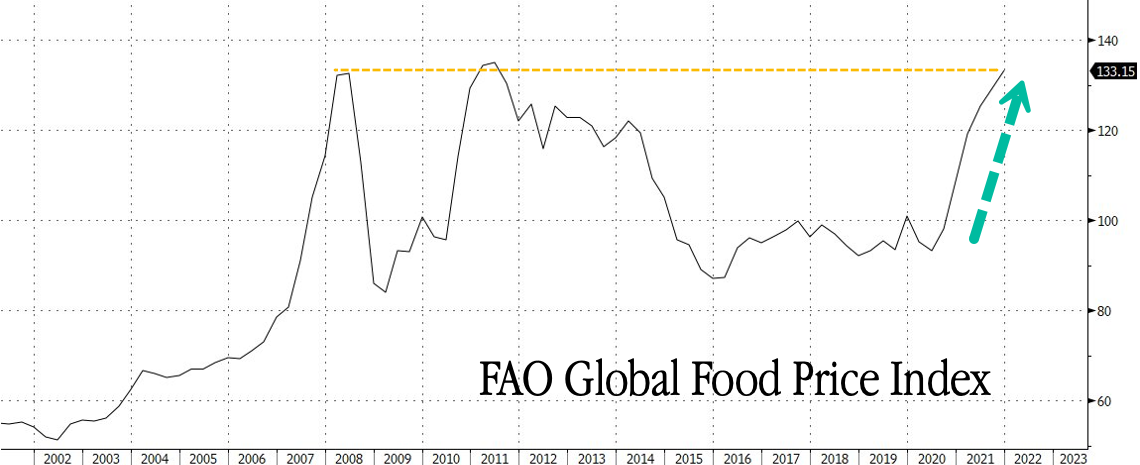
The GSCI Ag Index is in a pullback, which is counter-intuitive while equities are melting up.  The 43-week Moving Average at 410.55 puts a baseline under the uptrend, limiting potential pullbacks.  The 50-day Moving Average is at 417.17, giving intermediate-term support.  The chart is telling us that we could see food prices doubling in the next year.

ZeroHedge remarks, “In October, global food prices continued climbing higher for the third straight month, hitting fresh decade highs, led by vegetable oils and cereals. Higher food costs contribute to more inflationary pressures for the working poor, central banks, and governments.

The UN’s Food and Agriculture Organization’s food price index, which tracks a basket of food commodities, averaged 133.2 in October, up 3.9 points (3%) from September and 31.8 points (31.3%) from October 2020. The index has risen three consecutive months and is now at a new decade high (could hit record highs in 2022).

World vegetable oil and cereal prices were the two biggest movers in the index. Edible oils jumped 9.6% on the month to set a record high. Cereal prices rose 3.2%, within the basket, wheat jumped 5%. ”


9:40 am

BKX, our liquidity proxy, is also in its final stage of Primary Wave [5].  The Cycle Top is at 147.33 which may be reached imminently.  In the daily chart, it will have the appearance of a throw-over, a final panic rally for those who have waited for the “sure thing.”


8:30 am

Good MOrning!

Sometimes the big picture is helpful in determining where we really are in the markets.  The Weekly chart shows several items.  First, we are now within reach of the weekly Cycle Top at 4736.00.  One of the Cycle rules is that the index always reaches for the Cycle Top in its final probe.  The daily chart shows a throw-over due to the steep final rally, so I went to the weekly chart to gain perspective.  Second, the weekly chart illustrates the magnitude of the rally.  This is a Primary Wave [5] that can only fit on a weekly chart.  Third, the Orthodox Broadening Top formation shows that the markets have a long way to decline.

SPX futures reached a morning high of 4703.40.  Keep in mind the weekly Cycle Top should you be tempted to go long this morning.  Today is day 246 in the current Master Cycle.  A bit early but within the parameters of a reversal.

ZeroHedge reports, “US index futures continued their relentless meltup on the last day of the week, before today’s jobs report which is expected to bounce strongly from last month’s disappointing print (exp. 450K, up from 194K), and could set the pace for the Fed’s taper into 2022 if it is too much of an outlier in either direction. At 730am, e-mini S&P futures were up 8.25 or 0.18% to 4,681.5, a new all time high; Nasdaq futures rose 48 points or 0.29% and Dow futures were up 35 or 0.1%. 10Y yields were flat at 1.53% and the dollar index jumped, while Brent traded just above $80 after yesterday’s rout.”


VIX futures remained range-bound just above its three-year trendline.  A back-of-the-napkin calculation shows that it may go to the vicinity of 14.50 before reversing.  An Intermediate Wave (C) of a Primary Wave [3] will be a powerful Wave that may reach as high as 175.00 in the next 4-6 months.  Your eyes aren’t deceiving you…175.00.  At that point, the powers that be are likely to declare the VIX broken.  The VIX isn’t broken.  The system is.


TNX is now challenging Intermediate-term resistance at 15.43.  Today it is capable of a breakout to new highs as we begin the final two weeks of its Master Cycle.  It is noteworthy that I mentioned that this retracement should approach the October 11 low at 15.07.  Although the treasury shorts have had their weaker hands taken out, those that remain may be vindicated.  The current Master Cycle runs through November options expiration.

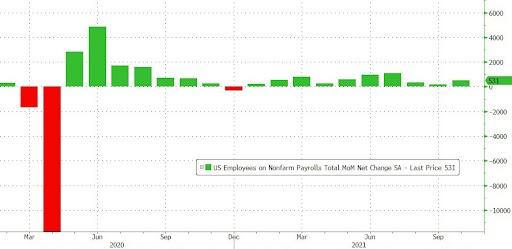
ZeroHedge observes, “After two months of dismal job reports, the BLS finally redeemed itself when moments ago it reported that in October the US gained some 531K jobs, well above the 450K consensus exp and above the 500K whisper number. The gain in payrolls was also bigger than all but 10 of the 75 forecasts in Bloomberg’s survey.

Remarkably, the private payrolls print was a stellar 604K, with government jobs shrinking by 73K in October. Just as importantly, the Sept print was revised solidly higher, from 194K to 312K, as was August, up from 366K to 483K. With these revisions, employment in August and September combined is 235,000 higher than previously reported.”


USD futures ran up to 94.64 this morning, just short of a second breakout above the Cycle Top.  This is the mark of a Wave 3.  The current Master Cycle has a week to go and may show unusual strength.


Posted in Published | Comments Off on November 5, 2021

November 4, 2021

8:15 am

Good Morning!

Just when the market reaches its upper trendline (Cycle Top) it has a throw-over.  SPX futures hit a new all-time high of 4667.70 this morning.  Today is 31 calendar days from the October 4 low.  The market is due for a “rest” very soon.  There are two possible outcomes for a decline.  Should it stay above the trendline at 4475.00, the SPX may soar to new all-time highs ending at the next Cycle interval in late January/early February.  A decline beneath the trendline opens the possibility of a major Cycle low at that time.  I have marked the chart as if the November Master cycle low will remain above the trendline.  The last turn interval was September 2 at 17.2 months.  The next turning point may be 21.5 months from the 2020 low.

ZeroHedge reports, “US equity futures plowed on to record-er highs overnight, propped up by a slew of stellar earnings reports and as investors shrugged off the Federal Reserve’s first steps to begin paring its pandemic-era support as Powell reiterated that the central bank can be patient on raising interest rates (even if rate hikes odds pricing in lliftoff in July were virtually unchanged after Powell’s announcement). The Fed Chair announced Wednesday that the central bank will start reducing bond purchases, adding that officials won’t flinch from action if warranted by inflation. The U.S. dollar and Treasuries advanced. “There was no dramatic Hulk-like metamorphosis from the Fed last night as they kept close to expectation,” DB’s Jim Reid said in a note. At 730 a.m. ET, Dow e-minis were down 7 points, or 0.02%, S&P 500 e-minis were up 6.75 points, or 0.15%, having earlier tagged a record high 4,662.5, and Nasdaq 100 e-minis were up 61.25 points, or 0.39%. The U.S. dollar and Treasuries advanced.”


VIX futures declined to an overnight low of 14.87, nearly taking out the October 22 low of 14.84.  Unfortunately, the VIX may make a new low today, as it would be day 267 of the Master Cycle.  Cycles are organic and may be stretched or shorteened, depending on their inputs.  We are all aware of the Fed and its liquidity pump.  However, there are other inputs that we may be lwss aware of.  For example, I warned on Sepember 20 that the new volcanic eruption at Las Palmas in the Canary Islands offers a very different kind of threat.

ZeroHedge reports, “Lava flows from Cumbre Vieja volcano on the Spanish island of La Palma have been ongoing for the seventh week, which began around Sept. 19. The volcano is now spewing what scientists call “lava bombs.”

At the end of October, geochemist Harri Geiger visited Cumbre Vieja and captured a video of a large molten rock known as a “lava bomb. These molten rocks are rare and don’t occur with every volcano. According to the USGS, molten rocks only develop during an explosive eruption.

The one Geiger found measures 3.2 feet across with an estimated weight of half a ton. Once ejected from the volcano, these projectiles can be extremely dangerous. ”


TNX has pulled back from yesterday’s high.  It may be testing Intermediate-term support at 115.38.  However, it is due for a breakout and possible new highs by November monthly options expiration.

ZeroHedge reports, “As noted earlier, today’s FOMC meeting did not surprise and announced the start of tapering. Balance sheet expansion will slow to USD 105BN as of mid-November and USD 90BN as of mid-December, and – absent material changes – is expected to end mid-June at which point the market sees the Fed beginning a rate hike cycle (odds of a July rate hike were virtually unchanged today at 0.946%, barely down from 0.97% before the FOMC) even thought Powell today tried to characterize inflation as more persistent than expected, but still transitory.


As Curvature’s Scott Skyrm notes, the tapering announcement was generally as expected, but at the same time, a little different: “Yes, the FOMC announced the Fed will purchase $15 billion fewer securities beginning in November. Basically, as expected. However, here’s the interesting part. The Fed pre-announced a second tapering of $15 billion in December. That means that beginning in January, tapering is still a “wild card.” We will expect another cutback of $15 billion in January, however, it’s not guaranteed. Theoretically, they could stop tapering in January or they could increase the pace of tapering. Overall, it looks like the December FOMC meeting will be important for the markets.”


USD futures are on the move higher, hitting 94.33 this morning.  The USD Cycle currently matches the TNX Cycle, within days.  The Cycles Model shows exceptional strength rising into options expiration.


Posted in Published | Comments Off on November 4, 2021

November 3, 2021

10:50 am

Crude Oil futures slipped beneath the Cycle Top support at 81.93 this morning.  This would be considered an aggressive sell signal.   The Cyclse Model projects a possible low occurring the week after options expiration.

ZeroHedge reports, “Oil prices have plunged overight after a bigger than expected crude build reported by API and further pressure from The White House on OPEC+ to start spewing more deadly, poisonous, existentially-threatening fossil fuels into the world to bring down gas prices for Americans.

Despite the pressure from the U.S. and other importers, the cartel is expected to stick to a plan to raise output by a modest 400,000 barrels a day at its meeting.

“OPEC+ staying the course is largely baked in, but the market will watch out for surprises,” said Vandana Hari, founder of energy consultancy Vanda Insights.

Oil is likely weaker today ahead of The Fed’s anticipated policy-tightening today.”


8:38 am

Good Morning!

SPX peaked precisely at the 21.5-market-day marker, possibly completing a Minor Cycle A.  SPX futures are flat near the high.  The Model suggests a possible 13-day decline into the week of November 15.  The anticipated decline is likely to stay above the lower trendline currently at 4360.00.  The September 2 high had all the signs of a major top, but was superceded by the continued liquidity flush through the system.  The next major Cyclical turning point may be between mid-January and early February.

ZeroHedge reports, “US stock futures were flat ahead of today’s Fed meeting, where the central bank is widely expected to announce the reduction of asset purchases with a majority of analysts expecting the Fed reducing its monthly purchases of Treasuries by $10 billion and mortgage- backed securities by $5 billion. Nasdaq 100 futures climbed 0.1% while S&P 500 and Dow Jones futures were little changed. Oil fell as the U.S. ramped up pressure on OPEC+ to boost supplies (which will bear zero results). The two-year Treasury yield was steady, while the 30-year rate shed two basis points. European stocks struggled for direction and the dollar fell less than 0.1%.


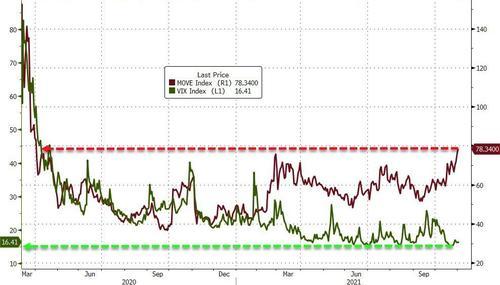
Despite turmoil in the bond market which sent the MOVE (or bond VIX) index to post-covid highs…

… stocks remain complacent and are likely not under stress “because we all think we know what will come out from today’s meeting: a gradual start of the tapering of the bond purchases program,” said Ipek Ozkardeskaya, senior analyst at Swissquote. A “taper announcement will likely be seamless, what may be less seamless is the rate discussion,” she wrote in a note.”


VIX futures remain range-bound as investors wait for the taper announcement.  A rally above 19.00 will clear all of the resistance points overhead.

ZeroHedge remarks, “Key Macro Week – Equity Vol Ignoring Rates Vol

As we have been pointing out lately, the MOVE vs VIX gap continues to trade very wide levels. BofA shows that the divergence is trading at unusual levels vs history:

“…equity vol and rates vol have decoupled recently is without precedent over the past 10 years”.

Will equity people, as they have so many times, chase VIX post the Fed?”


TNX futures challenged the revious low, but the cash market does not reflect it.  There is a possibility of a lower low today as the Cycles Model indicates a possible Trading Cycle low in the making.  However, the reversal to higher yelds is just around the corner.  This has all the earmarks of a classic short squeeze that may erupt into a breakout by mid-month.

ZeroHedge observes, “Heading into today’s Treasury refunding announcement, consensus expected Janet Yellen to trim the size of the coming quarterly debt sale by roughly $2 billion per tenor, the first such cut in long-term debt sales since Feb 2016. And, with the Fed set to announce a taper later today, its joint-venture partner in Helicopter Money, the US Treasury did precisely as expected (and precisely as one would expect in a time of tapering), when it said it would sell $120 billion of long-term securities at auctions next week, down $6 billion from the record $126 billion level seen over the past three so-called quarterly refundings, as it plans to reduce coupon auction sizes across all maturities.

Specifically, the Treasury will sell:

  • $56BN of 3-year notes on Nov. 8, down from $58BN
  • $39BN of 10-year notes on Nov. 9, down from $41BN
  • $25BN of 30-year bonds on Nov. 10, down frrom $27BN.

The Treasury said the auctions will raise about $44.1BN in new cash.”


USD futures are edging higher this morning as the Master Cycle may run hot into new high next week.


Posted in Published | 8 Comments

November 2, 2021

9:20 am

Good Morning!

SPX futures reached an overnight high of 4617.70, not wanting to giv up its perch near Monday’s high.  Wednesday’s options are very light, but bullish above 4595.00.  Options gamma may not influence the SPX as strongly until monthly options expiration in November.

As to the Cycles, it appears that the Master Cycle came early, on October 4.  I have been preoccupied with my mother’s death and missed the signs of the early ending.  On Friday I mentioned that the door slams shut for the old Master Cycle.  Since a new high was made on Monday, I have to recognize that I missed the turn in early October, day 248.

The new Cycle has a possible termination date of November 17, two days before the monthly options expiration.  We may be anticipating a shallow low at that time.

ZeroHedge reports, “US futures and European bourses retreated slightly from record highs as investors weighed the ever worsening supply crunch and virus curbs in China against strong earnings with all eyes turning to the conclusion of the Fed’s 2-day meeting tomorrow, when Powell will announce the launch of a $15BN/month taper. At 7:20 a.m. ET, Dow e-minis were up 7 points, or 0.02%, S&P 500 e-minis were down 0.50 points, or 0.01%, and Nasdaq 100 e-minis were down 28.75 points, or 0.18%. Iron-ore futures tumbled on shrinking steal output in China. Tesla led premarket losses in New York.

Investors paused to reflect on a rally that’s taken U.S. and European stocks to record highs. With a post-pandemic supply crunch stoking inflation and pushing central banks to tighten monetary policy, they have begun to question valuations. Economic recovery is also under strain as countries from China to Bulgaria report rising Covid cases. Both the S&P 500 Index and the Dow have been scaling new peaks as U.S. companies post another stellar quarter for earnings. Of the 295 companies in the equity benchmark that have reported results, 87% have either met or surpassed estimates.”


Posted in Published | Comments Off on November 2, 2021

October 29, 2021

7:30 am

I will not be blogging on Monday, November 1.  I will be attending my mother’s funeral.

Good Morning!

SPX futures came down to a morning low of 4567.50.  Today is day 275 in the Master Cycle, after which the door my be shut to new highs.  MAx Pain in today’s expiring options appears to lie at 4575.00, so the dealers and hedge funds are doing their best to pay out the least.  In SPY (closed yesterday at 458.32) options, Max Pain appears to lie at 455.00.  Should SPY go beneath that level, a gamma storm may ensue.

ZeroHedge reports, “US equity futures fell along with European and Asian stocks on Friday after tech giants Amazon and Apple and Starbucks sank in premarket trading after their earnings missed expectations, signaling a possible drop of around $180 billion in combined market value when the U.S. reopens, while dizzying bond-market gyrations sparked by surprise central bank announcements amid concerns over inflation and monetary tightening left investors scrambling to guess what happens next. A failure by Biden and the Democrats to pass their massive Build Back Better stimulus package added to the bearish sentiment. At 7:15 a.m. ET, Dow e-minis were down 45 points, or 0.12%, S&P 500 e-minis were down 22 points, or 0.5%, and Nasdaq 100 e-minis were down 138 points, or 0.88%. 10Y yields rose 3bps to 1.61%; the dollar rose while bitcoin was flat at $61,000.”


NDX futures sold off to a morning low at 15607.50 before a small bounce.  Yesterday’s new all-time high in the NDX brought in more retail investors, confident of a never-ending bull market.  It doesn’t appea that NDX will pull another rabbit out of the hat as the curtain closes for this Master Ccle.

Zerohedge observes, “With the bulk of the FAAMG stocks – which is now GAMMA following Facebook’s rebranding to Meta – reporting solid results, investors were keenly looking to Amazon earnings, where the biggest question for Amazon is how sustainable are the growth trends that boosted its performance during the pandemic. The Internet giant was one of the biggest beneficiaries of shifts in consumer and business behavior last year while continuing to grab market share in cloud.

Many consumers flocked to buy things online as they wanted to avoid infection at physical stores, with the recent Delta wave scare likely providing a further boost to Amazon. Further, Amazon Web Services revenue soared on back of rising usage from Internet digital services – including remote-working software, videostreaming and gaming. But with the wider availability of vaccines and as employees start to return to physical offices, the risk is some of these trends may start to reverse. Investors will be also looking for any commentary on the future prospects for regulation and antitrust legislation.

That said, Amazon is lapping last year’s blockbuster pandemic boost, and investors are aware it can’t match last year’s growth. Analyst estimate third-quarter sales growth of 16.3% to $112 billion – the high end of the company’s own guidance for Q3 of $106-$112BN – less than half the pace of growth of the same period a year ago. While slowing growth is anticipated, 16.3% for a company the size of Amazon is still remarkable.”

ZeroHedge further comments, “Moments after a very ugly quarter from Amazon, which missed on the top and bottom line and guided far lower than consensus, investors held on to hope that at least the world’s largest company, Apple, would somehow pull a rabbit out of its magic hat of tricks and report solid earnings pulling the Nasdaq out of its after hours slump. Alas, it did not and after reporting a miss on the top line (and matching the EPS), AAPL is also tumbling after hours and dragging Nasdaq futures down with it.

Here are the ugly details from the just concluded Q4:

  • Rev. $83.36B, missing est. $84.69B, this was the first revenue miss since 2017!
  • EPS $1.24, matching est. $1.24″


VIX futures leaped to a new Cycle high at 18.06 this morning.  There is a triple resistance to overcome at 18.95.  Once accomplished, the VIX Model appears to have growing strength to mid-November where a potential Master Cycle high awaits.

Investing.com informs us, “I have been trading options and coaching / mentoring other new options traders for years. I have seen new traders who were lucky and ended up with some winning trades and others who were so frustrated and on the verge of giving up. I have seen it all. One of the things I have noticed is that very few people understand the CBOE Volatility Index, the fear gauge to the markets.

Many know that it is a measure of fear but they don’t really understand what it is and how it is constructed. If you are an options trader, I would argue it is very important that you as a trader understand what the VIX is and how it works.”


TNX futures soared to an overnight high at 16.17 before easing back at the open.  As mentioned earlier this week, TNX  is now in a period of strength.  This may kick off a new rally that may extend until November monthly options expiration.

Zerohedge remarks, “Ahead of today’s sale of $62BN in 7Y paper, we tweeted that unlike this week’s previous absolutely stellar 2Y and 5Y auction which were only superb because traders were short cash bonds heading into the auction and needed paper to satisfy their short obligations, today’s auction was not at all special in repo suggesting the short overhang was far less which in turn meant that the auction would proceed purely on its fundamental, inflationary merits. I.e., it would be ugly.

We were right, and while it wasn’t nearly as ugly as the infamous February 2021 7Y auction which sparked the March market swoon and the surge in yields, it was still far uglier than this week’s previous coupon sales both of which stopped impressively through their When Issue,”


USD futures are higher this morning, testing Intermediate-term resistance at 93.66.  The Cycles Model calls for the next two weeks of rally with growing strength in Wave [iii], usually the strongest in the series of motive Waves.

ZeroHedge observes, “Americans’ income was expected to drop modestly (-0.3% MoM) in September and, of course, spending rise (+0.6% MoM) but incomes actually fell significantly more than expected, dropping 1.0% MoM (while spending rose 0.6% MoM as expected).

Source: Bloomberg

On the income side, wages for private workers dropped from 10.8% to 1.7%, the lowest since March 2021, while, wages for government workers rose to 7.2% from 6.8%.”


Posted in Published | Comments Off on October 29, 2021