March 18, 2022

1:47 pm

SPX is approaching its 50-day Moving Average at 4444.31.  It may overshoot, but the rally is very extended.  Prepare to go short.  Pick your spot and hang on!

ZeroHedge comments, “In late 2021 we noted a gaping divergence in one of Wall Street’s most closely watched surveys, the BofA Fund Manager Survey: while the number of respondents seeing a stronger economy had collapsed with the majority now expecting a contraction, the allocation to stocks remained near record high levels, resulting in what we called a “historic divergence“.
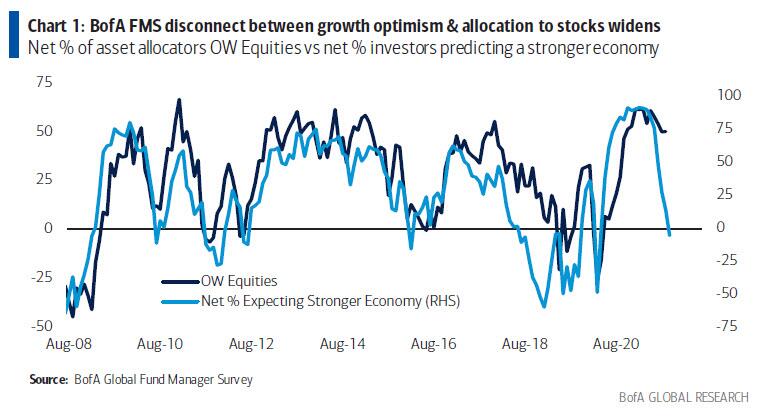
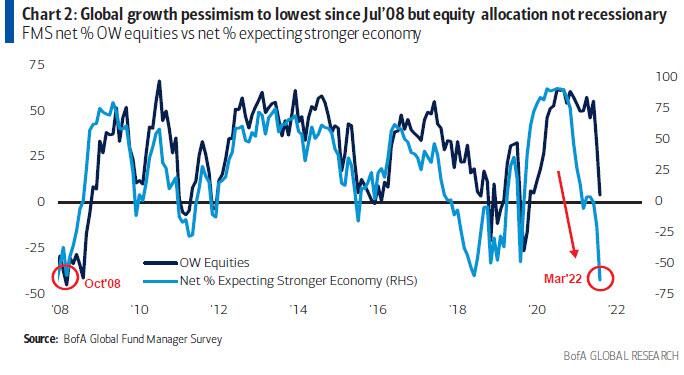
Well, earlier this week we learned that this bizarre divergence had largely collapsed: after several months of tentative declines, Wall Street sentiment in March finally hit rock bottom and according to the latest BofA Fund Manager Survey published on Tuesday (which polled some 341 panelists with $1 trillion in AUM were polled, the full survey is available to ZH pro subs in the usual place) global growth optimism has crashed to the lowest since July 08, two months before Lehman crashed.”
 

11:25 am

Today’s rally exceeding the March 3 high altered both the Elliott Wave structure and the Master Cycle date.  It turns out that the Master Cycle made a low on February 24 (day 251) instead of the March 3 high (day 258), which was too convenient to argue with until today.  It also simplifies things tremendously.  In Summary, Wave (1) took 51.5 calendar days and Wave (2) is on its 22nd day today (21.5), which may bring the correction to an end.  The current Master Cycle may end on or near April 4, giving the SPX a potential 17.2 calendar days of decline.


8:45 am

Good Morning!

SPX futures declined back to the mid-Cycle support at 4375.99 as it finishes its short squeeze into options expiration.  This morning’s expiring options are long at 4400.00 and above, so it is back in neutral territory.  The options tree is heavily laden with both puts and calls with puts dominating below 4300.00.  There is every reason to believe that the longs have exhausted their liquidity and the shorts may soon dominate again.  The next Master Cycle (low) is due on April 5, 12.9 market days from now.

ZeroHedge reports, “After a torrid three days which pushed US stocks up almost 6%, the best 3-day run since the Nov 2020 election..

… U.S. index futures finally dropped on Friday one day after JPMorgan again said to BTFD, as traders were concerned Washington may take a tougher stance on China for its muted response to Russia’s invasion of Ukraine during a phone call between Xi and Biden set for Friday morning, while bracing for volatility on quad-witching day where $3.5 trillion in options and derivatives are set to expire…

… as the concurrent rebalancing of benchmark indexes including the S&P 500 sill send volumes soaring. Contracts on the S&P 500 and the Nasdaq 100 both ticked lower about 0.6%. Oil dropped after yesterday’s remarkable surge with WTI trading around $102, while Treasuries and the dollar rose and bitcoin traded just above $40,000. ”

ZeroHedge further warns, “While index options are the key focus ahead of today’s huge quarterly expiration, there is still a sizable $610bn of single stock options are set to expire today.

And, as we have touched upon during all previous quad-witches, today’s expiry could be important for stocks with large open interest in at-the-money (ATM) option, and market makers delta-hedging large options portfolios will be active.  As Goldman so helpfully puts it, “this flow is likely to dampen volatility in some names while exacerbating stock price moves in others.”


VIX futures rose to a morning high of 26.82 as it recovers from its extended Master Cycle low.  Yesterday I mentioned the setup for a slingshot move and the trendline is an ideal mechanism to launch it.  In addition, it has crossed above the 50-day Moving Average at 26.50, giving it a buy signal.


TNX is consolidating after a very strong move higher.  The consolidation may not last, as the Cycles Model indicates trending strength returning by this weekend.  It appears that TNX may continue to rally in srength for the next four weeks.

RealInvestmentAdvice observes, “Recession risk is rising rapidly. In fact, it is possible that we may already be in one.

While such a claim may sound impossible, given that Q4-GDP was above 5% in terms of annualized growth, such would not be the first time such a turn occurred.

As I discussed in “Shortest Recession In History,” the 2020 recession lasted just two months. However, during those two months, the economy fell by 31.4% (GDP), and the financial markets plunged by 33%. Both of those declines, as shown in the table below, are within historical norms.”


USD futures rose above the Cycle Top resistance at 98.37 and is aiming for the upper trendline near 100.00.  There are only three market days left to the Master Cycle high due by mid-week.  The Cycles Model shows a triple burst of strength, so we may see the final stretch in the USD rally boosted by a very large inflow, possibly from Europe, which is destabilizing.

ZeroHedge comments, “It was just a couple of weeks ago that I wrote an article arguing that the economic sanctions we have cast upon in Russia, due to its invasion of Ukraine, likely mark the beginning of a period where China and Russia would bifurcate the global monetary system, leading them to eventually challenge the U.S. dollar’s reserve status.

Now, Saudi Arabia is joining the fray, further threatening to tip the balance of the global monetary scales that have kept the U.S. dollar afloat for decades.

The fact that predictions of a “new economy” and “new monetary system” only exist on fringe blogs like mine and haven’t gone mainstream given the current economic situation with Russia (even amidst our abuses of printing the dollar over the last several decades) is baffling to me.”


Posted in Published | Comments Off on March 18, 2022

March 17, 2022

8:30 am

The Shanghai Composite Index rallied to 3260.17 before easing back, closing the gap.  With six weeks to go to the next Master Cycle Pivot, there is little or no chance of recovery.  While the bounce looks impressive, it is primarily short covering based on Xi Jinping’s jawboning.

ZeroHedge comments, “Calming words from Chinese President Xi Jinping’s right-hand man Liu He helped spur one of the most-dramatic turnarounds of Chinese and Hong Kong stock markets in history. The verbal intervention, coupled with possible follow-up policy support, may mark a market bottom, if history is any guide. Beijing’s policy put is still alive. “


SPX closed yesterday exactly at its options expiration Max Pain zone. (I wonder how they do that?)  Futures have since declined to 4329.70 before a small bounce.   Friday’s expiring options turn negative at 4330.00 and gamma goes short beneath 4250.00.  There are $3 trillion in nominal options expiring tomorrow which are pretty evenly divided between puts and calls.  Today may mark the top of a 4.3-day decline aiming for the Cup with Handle formation target.

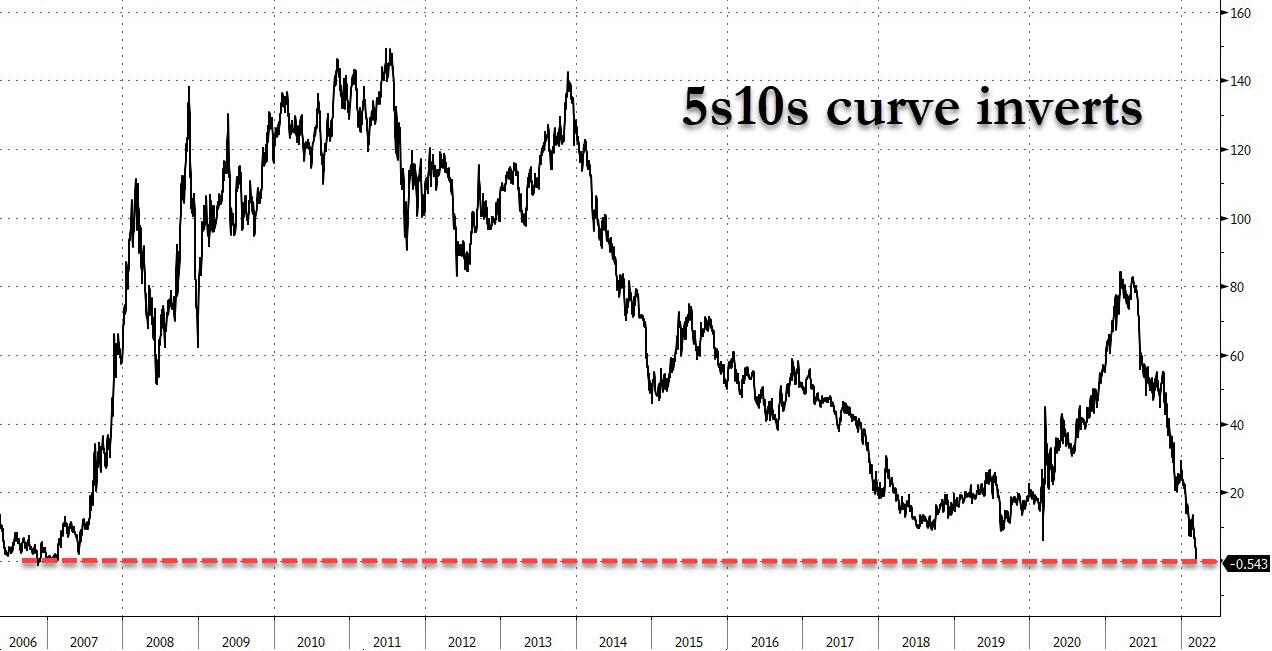
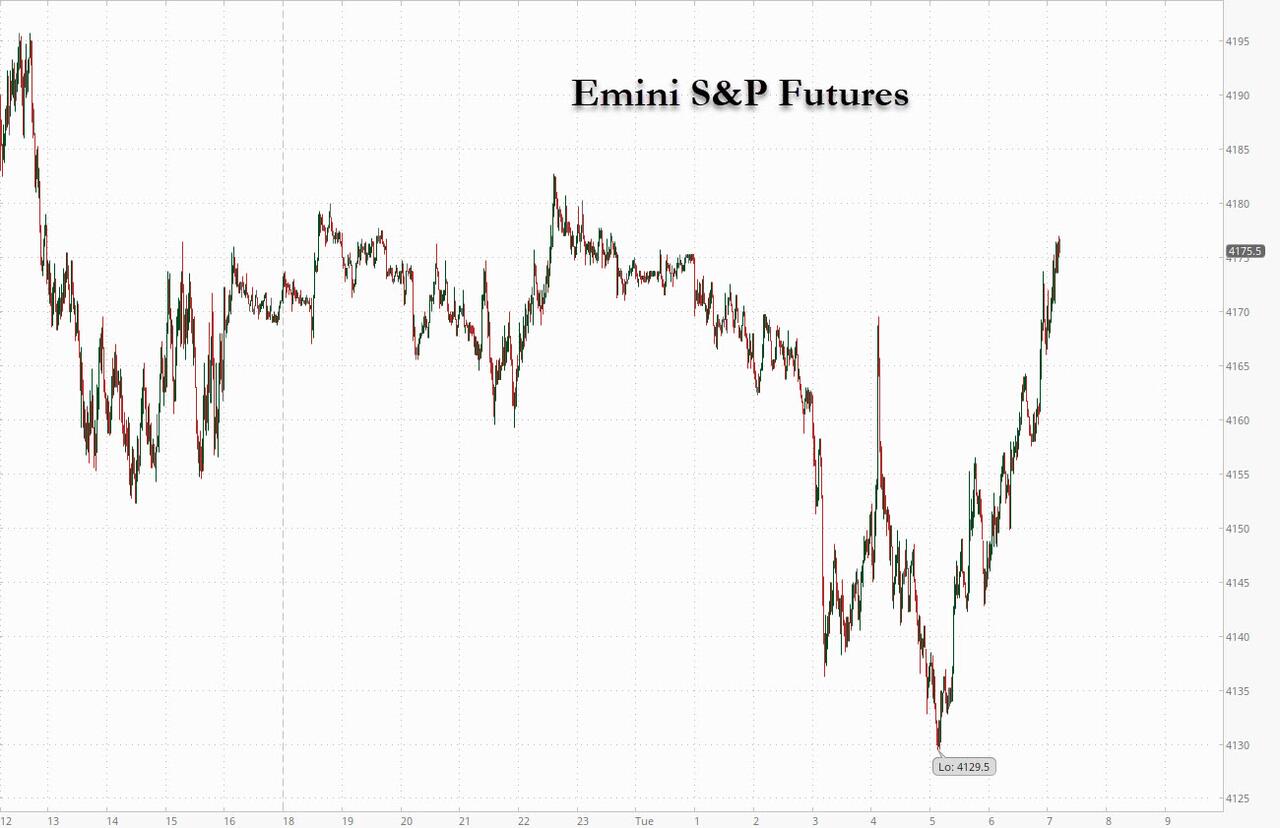
ZeroHedge reports, “After yesterday’s explosive session, which saw stocks trade in violent kneejerk response to conflicting headlines out of Ukraine at first, only to post the biggest ever post FOMC reversal, as markets realized that the Fed’s overly hawkish ambitions are too great and doom the rapidly slowing economy to an accelerated recession, overnight trading has been positively subdued with emini S&P futs trading in a tight 20 point range between 4,340 and 4,360 until 6 am ET, when European stocks turned negative and US equity futures suddenly dropped as much as 0.5%, after the Kremlin said reports of major progress in Ukraine talks are “wrong” and Kremlin spokesman Dmitry Peskov dismissed reports that the warring parties are moving toward a settlement, blaming Kyiv for slowing the negotiations, crippling any hope for a quick ceasefire deal and adding to worries about the outlook for economic growth as the Federal Reserve’s campaign against inflation gets underway. Futures were already wavering as the bond market flagged a growing risk that the Fed’s efforts to rein in prices could trigger an economic downturn with the 5s10s curve inverting. Ominously, Brent jumped more than $5/bbl after tumbling below $100 yesterday.

Contracts on the Nasdaq 100 dipped 0.4% by 7:30 a.m. in New York, while S&P 500 futures were 0.34% lower. The benchmark S&P 500 on Wednesday posted its best two-day rally since April 2020 as the Fed hiked interest rates by a quarter point and Chair Jerome Powell signaled the economy could weather tighter monetary policy. Gold and 10Y yields dropped to session lows, and bitcoin was modestly lower on the session. Europe was slightly green while Asia stocks closed higher, led by the Hang Seng which rose 7%”


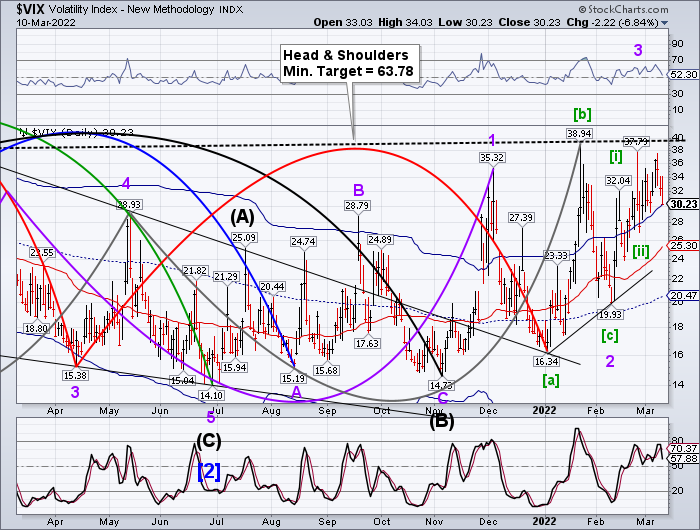
VIX futures rose to an overnight high of 27.47 after reaching support at the 50-day Moving Average at 26.32.  The Master Cycle appears complete on day 260.00.  This is the setup for a slingshot move that may fulfil the required distance for the Head & Shoulders formation.


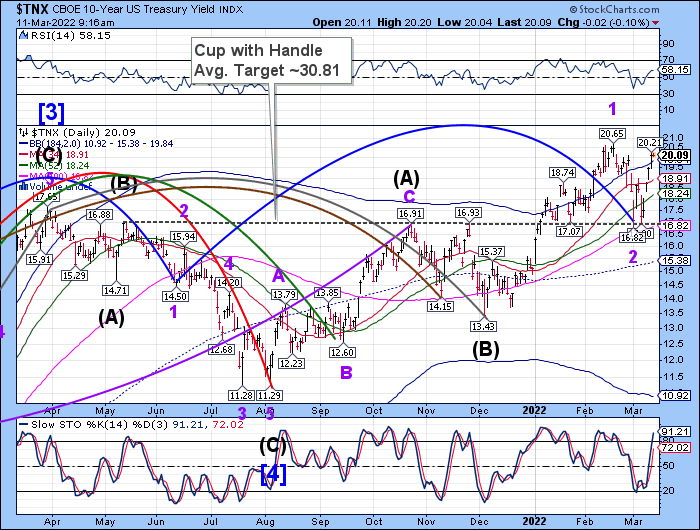
TNX pulled back from yesterday’s high, but only for a day, as trending strength comes roaring back over the weekend.  It may find support at the Cycle Top at 20.33 before resuming its uptrend.

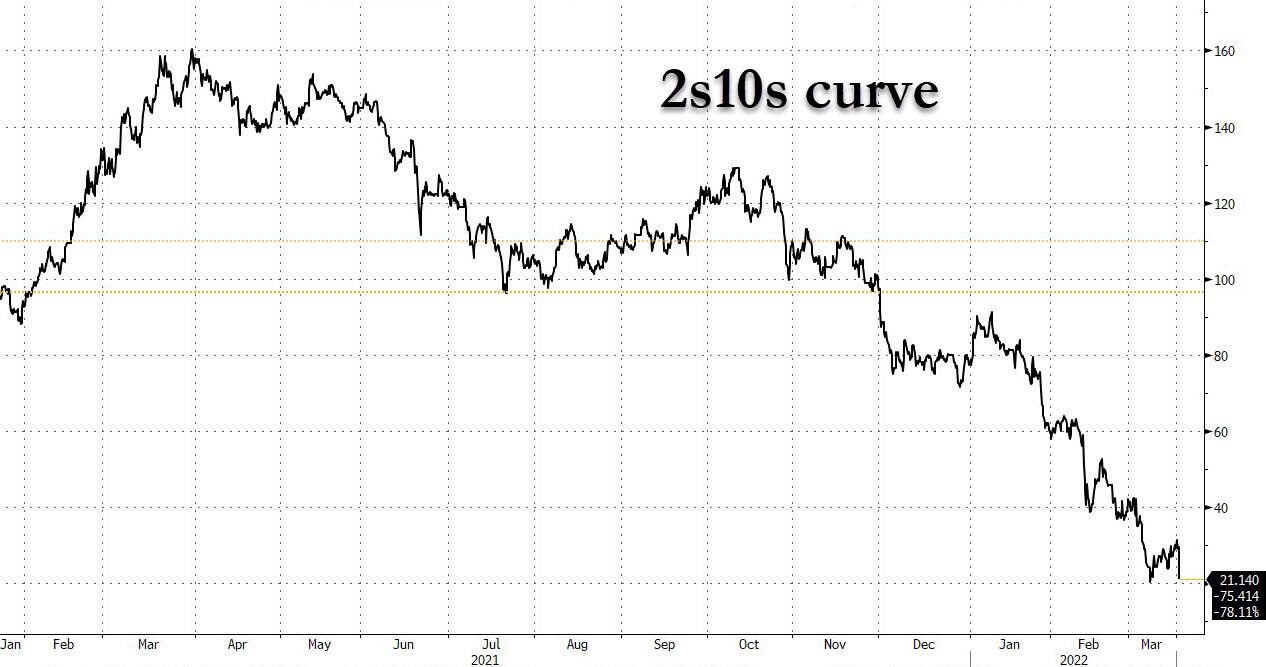
ZeroHedge remarks just how far behind the Fed really is with rates.  “Echoing our earlier thoughts that the Fed officially started the countdown to the next recession (and rate cuts) when it inverted the 5s10s moments after Powell starting speaking, DB’s Jim Reid writes that while not every Fed hiking cycle leads to a recession, all hiking cycles that invert the curve have led to recessions within 1 to 3 years. And the problem with the Fed hiking cycle that starts today, he adds with a ZH-esque does of skepticism, is that “there is a decent likelihood that the curve inverts relatively early on. 2s10s peaked at +157.6bps last March and traded as low as +21.9bps last week before settling at around +30bps as we go to print.”

As a reminder, while not as popular as the 2s10s, the 5s10s is also a harbinger of recessions, and usually precedes the 2s10s inversion by weeks. It is this curve that inverted today.


Crude oil is challenging its Cycle Top and trendline at 10.68, but may have a few more days of decline before the Master Cycle is complete.  Today is day 254, so the bottom appears to be anticipated on Monday or Tuesday.


Posted in Published | Comments Off on March 17, 2022

March 16, 2022

1:15 pm


12:38 pm

SPX has paused beneath the mid-Cycle resistance at4378.65 that has stopped the last two Cycle tops.  The rally appears complete, but may be subject to a whipsaw at the FOMC announcement.  There really is no consensus about what happens next, so analysts attempt to baffle with BS.  The EW structure calls for a slingshot move down over the next 4.3 days.  The Cup with Handle target is still valid, while most analysts have been using the Head & Shoulders  methodology.  Point 6 of the massive Orthodox Broadening top is 2104.00.   The Cycles suggest it may be reached by June.


12:30 pm

Crude oil futures are consolidating beneath the Cycle Top/trendline at 100.45.  It has another possible 3-4 days of decline to the next Master Cycle terminus (low).  Possible targets range from the mid-Cycle support at 78.67 and the lower Broadening Wedge trendline at 70.00, depending on market liquidity.  A liquidity crisis may bring it down to the Cycle Bottom at 56.89.  Stay on alert for developments.

ZeroHedge observes, “With traders expecting a drop Crude inventories in the latest week, moments ago the DOE surprise the oil market when, in an echo of last night’s API report, it said that crude stocks actually grew by an unexpectedly large 4.345MM barrels, just shy of the highest weekly build of 2022 (it rose 4.5mm in the week of Feb 18), and printed far higher than the expected -1.8MM drop. It was not immediately clear how such a large crude build was possible unless demand destruction has already struck.”

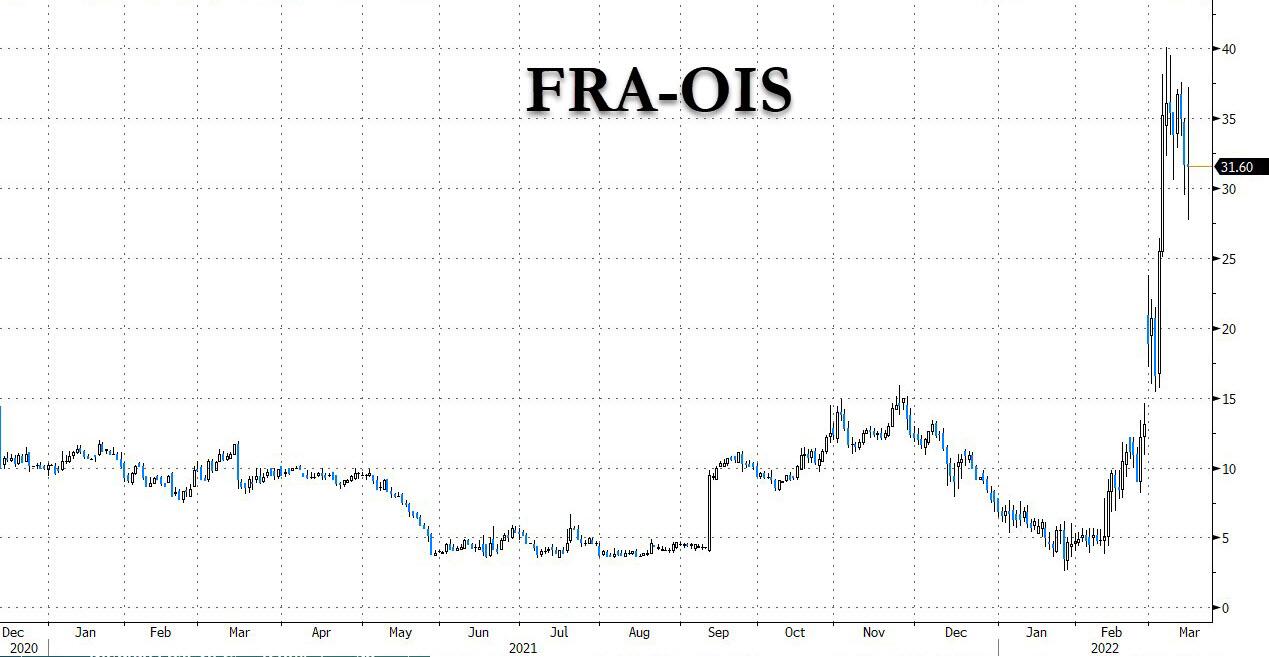
ZeroHedge updates, “Yesterday, we reported that the Bloomberg news that one of the world’s largest independent energy merchants – the secretive Trafigura which trades hundreds of billion in commodities every year – was facing “margin calls in the billions of dollars” which meant that the commodity “margin call doom loop” idea floated by repo guru Zoltan Pozsar was finally coming true, and despite Barclays’ earnest attempts to minimize its impact, could threaten broader financial stability and was manifesting itself in broad liquidity squeezes which could be observed in the surge in such unsecured funding markets as the FRA-OIS.


8:30 am

Good Morning!

The Shanghai Composite Index rallied to 3177.79 in a short-covering episode.  Don’t be fooled by the size of the rally.  Instead, look at how little it has recovered compared to the losses.  The Cycles Model suggests another six weeks of decline from here.  The Cup with Handle formation gives us a potential target for this decline that matches that time frame.  The bottom of a bear market is not marked by dealers urging their clients to buy…

ZeroHedge observes, “Yesterday, we had a feeling that China would finally do something to arrest the collapse in its local stocks…

… and little did we know that just a few hours later we would see the biggest surge in Hong Kong stock history, coupled with a furious surge in China’s CSI300.

Two days after we said that JPM’s call that Chinese internet stock are uninvestable and that the bank’s wholesale downgrade of Chinese tech would mark the bottom…”


SPX futures roared back to 4300.00, removing one of the iterations in the Wave structure and suggesting the market may stay pumped at least until the FOMC announcement.  I had anticipated that the decline might resume yesterday, but the Cycles are still working on 5-day intervals (not 4.3-days) which may be complete this afternoon.

This is likely due to options expiration today.  SPX closed at Max Pain at 4260.00 yesterday.  It is now attempting to go bullish.  Today’s expiring options go appreciably long above 4300.00, but it is difficult to say where gamma turns long.  Friday’s options expiration appear evenly matched all the way to 4400.00 with $3 trillion of expiring options.  A failure today may bring a bloodbath among the dealers and hedge funds selling both sides of the options market.  It is no wonder the SPX is being propelled higher.

ZeroHedge reports, “Normally, the first rate hike in more than four years meant to spark a “shallow” recession and destroy commodity demand would not be viewed positively by markets (unless it leads to another mega QE, which it will), but today is an exception with global stocks and US futures surging after the Kremlin hinted at progress in peace talks with Ukraine, adding to positive sentiment stoked by China’s vow to stabilize its battered markets which sent Hong Kong stocks soaring by the most on record.

At 730am, S&P futures are up 1.3%, with Nasdaq futs +1.8% outperforming amid overnight tech action, influencing European sectors, on the back of China’s jawboning stocks higher and constructive commentary from Ukraine’s Zelensky and Russia’s Lavrov. European bourses are also firmer across the board, Euro Stoxx 50 +3.3%, after a firmer handover from the Asia session and on geopolitical optimism.  Treasuries were steady and the dollar slipped ahead of the Federal Reserve rates decision. In FX, DXY reels amid support for EUR on yield action ahead of noted EUR/USD option interest at the NY cut. Core debt is depressed, with yields continuing to climb and the German 10yr through 38bps. WTI and Brent are consolidating and have most recently dipped into negative territory as premia unwinds.”


VIX futures made a new low at 28.34, extending Wave (ii) and the Master Cycle to day 260.  This is an acceptable stretch and further sets up the VIX for a “slingshot move” that may propel the VIX over 65.00.  This appears to be a confirmation of the Head & Shoulders target.  There may be turmoil under the surface that becomes evident today.

ZeroHedge comments, “The Volmageddon event of February 2020 is back, only this time instead of destroying the XIV inverse ETF, it is now targeting the VXX

Yesterday we said that we had a feeling the market would break today, and one look at the VXX volatility-tracking ETN, confirms just that.

As a reminder, on Monday morning Barclays announced – to the shock and dismay of millions of VXX investors on both the long and short side – that it would suspend any further sales from inventory and any further issuances of the VXX VIX Short-Term Futures ETN, claiming that “Barclays does not currently have sufficient issuance capacity to support further sales from inventory and any further issuances of the ETNs.” As some humorously put it, a volatility ETN just broke because of… volatility.”


TNX futures made an overnight high of 22.04, whereas the cash market merely rose to 21.83.  This may have completed an impulse (five waves) which suggest a more modest pullback than the one illustrated in the past couple of days.  In any event, there is often a knee-jerk reaction to buy bonds when stocks decline.  This may occur as early as this afternoon.

Zerohedge comments, “Central banks face a challenging trade-off: do they react to the labor market close to full employment and near record jump in inflation visible even before the latest energy price moves to prevent a further unanchoring of inflation expectations to the upside, or do they react to the considerable downside risks to the economic outlook from a massive geopolitical and energy price shock, preferring not to add volatility to the current market environment. The ECB opted for the former, and the Fed is expected to follow suit.

Tomorrow the Fed will hike 25bps – its first rate hike since Dec 2018 and the first liftoff (from zero) since Dec. 2015. In his recent testimony to Congress, Chair Powell summed up the compromise that the FOMC appears to have reached by noting in his recent testimony to Congress that he will support a 25bp hike at the March meeting, but is open to hiking by more than 25bp at a future meeting if inflation surprises to the upside or remains persistently high.”


USD futures sagged toward the Cycle Top at 98.26, making a low of 98.41.  USD has another week to go to make its Master Cycle high near 100.00.

ZeroHedge observes, “One of the core staples of the past 40 years, and an anchor propping up the dollar’s reserve status, was a global financial system based on the petrodollar – this was a world in which oil producers would sell their product to the US (and the rest of the world) for dollars, which they would then recycle the proceeds in dollar-denominated assets and while investing in dollar-denominated markets, explicitly prop up the USD as the world reserve currency, and in the process backstop the standing of the US as the world’s undisputed financial superpower.

Those days are coming to an end.”


Posted in Published | Comments Off on March 16, 2022

March 15, 2022 – The Ides Of March

1:48 pm

Exactly 8.6 market days have elapsed from the March 3 high at 4416.78.  I had originally considered this to be a low, but it turns out to be the final bounce before the decline beneath the Lip/Neckline at 4200.00.  It would be no surprise to see a lower close from yesterday.  Since the Cycle is indicating a continuation, we may expect another 4.3 days of decline into the afternoon of March 21.

ZeroHedge observes, “In late 2021 we noted a gaping divergence in one of Wall Street’s most closely watched surveys, the BofA Fund Manager Survey: while the number of respondents seeing a stronger economy had collapsed, the allocation to stocks remained near record high levels, resulting in what we called a “historic divergence“.

Well, the divergence is no more: after several months of tentative declines, Wall Street sentiment in March has finally hit rock bottom and according to the latest BofA Fund Manager Survey conducted by Chief Investment Strategist Michael Hartnett in which some 341 panelists with $1 trillion in AUM were polled, global growth optimism has crashed to the lowest since July 08, two months before Lehman crashed.”


8:10 am

We have not paid a lot of attention to China recently, to my regret, since the Shanghai Composite Index is nearing a bear market with a 17.7% decline from it’s September high.  I had previously mentioned that, as the Tech-heavy China stocks go, go goes the NDX.


In reality, the Chinese indices may have followed the NDX, which is down over 22% from its November high, but did not beak support until today.  NDX futures declined to a low of 12944.10, clearly piercing the Lip/Neckline of the doubly bearish formation.  The futures have bounced to 3140.50 this morning, but are losing their upward impetus.  What we are witnessing is a probable Phase-shift, where the trendline acts as a dam, holding back the rising water until it is breached.  Today may be such a day.  Despite the bounce, the technical damage is already done.

ZeroHedge reports, “Welcome to another rollercoaster session where US equity futures first tumbled alongside the second consecutive day of stocks plunging in China, which also dragged Europe lower, only to hit a U-turn around 5am at which point sentiment reversed higher, ahead of tomorrow’s expected Federal Reserve rate hike and amid mounting risks from the war in Ukraine and a Chinese equity rout. Nasdaq 100 contracts trade 0.5% higher at 7:15 a.m. after earlier slumping as much as 0.8% following the first bear-market close for the first time since March 2020. S&P 500 futures also turned 0.3% green, as did Dow futures.


VIX futures made a new overnight high at 33.83 before easing back.  It is likely that Friday’s low on day 255 of the Master Cycle may have been the bottom.  It is not always the highest or lowest reading that finishes a Master Cycle.  In this case, it announces a potential Phase-shift into high gear, as it may be launching Wave (iii) of [iii] of 3 of Intermediate Wave (C) of Primary Wave [3] of Cycle Wave 3 of Super Cycle Wave (c).  This seven-degree Wave may denote a panic developing with tremendous strength, possibly not seen since the Great Depression.  Wave 3s and Cs are never the smallest and often the strongest of the series.


The NYSE Hi-Lo Index has been problematic in the last three months, partially due to the wide-ranging swings from highs to lows in short periods of time.  In this case, it may be providing a warning of what’s to come.  The Orthodox Broadening Top offers a target for this particular decline which may not be ignored.  The targeting methodology suggests a deeper low than the March 2020 low at -2375.00.  In fact, it may rival the October 2008 low at -2891.00.


TNX is rapidly declining, suggesting a possible decline to the trendline at 17.00 before snapping back.  This may cause huge liquidity issues that may spill over to equities.  I am having difficulties with my charts that don’t seem to have a solution yet.  Thus, the change to a 2-hour chart in TNX.


Posted in Published | Comments Off on March 15, 2022 – The Ides Of March

March 14, 2022

9:45 am

The Ag Index is in a correction/consolidation that may only last about two more weeks.  This may be the last chance to buy shares of a commodity that may double in the next six months.  As they say, buy the dip.

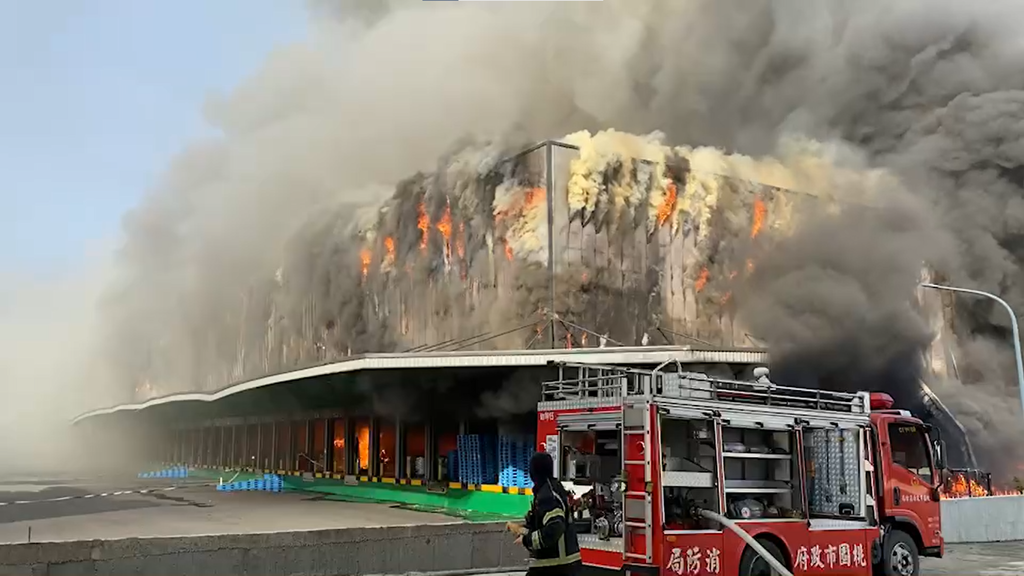
ZeroHedge reports, “A massive fire has broken out at a northern Taiwan logistics center for the 8th largest retailer in the world.

According to Taiwan News (citing CNA), officials in the northern Taiwan city of Taoyuan received a report early Monday of a massive blaze at the warehouse in the city’s Yangmei District at the Carrefour Logistics Center.

73 firefighters, 23 fire trucks, 8 tanker trucks and 4 ambulances were dispatched to the scene, where according to reports, nobody has been trapped in the facility.

According to the fire department, the fire appears to have started on the first floor of the two-story structure. There are no hazardous items believed to be inside.

The entire facility is currently engulfed in flames, and smoke can be seen billowing into the sky from several kilometers away. An investigation into the cause of the fire and damage assessment are currently underway. –Taiwan News


Further, ZeroHedge observes, “Two weeks after the Russia-Ukraine crisis began, the world is quickly moving toward a food crisis that could affect millions of people. A spillover of the crisis could soon spark agricultural mayhem in the US.

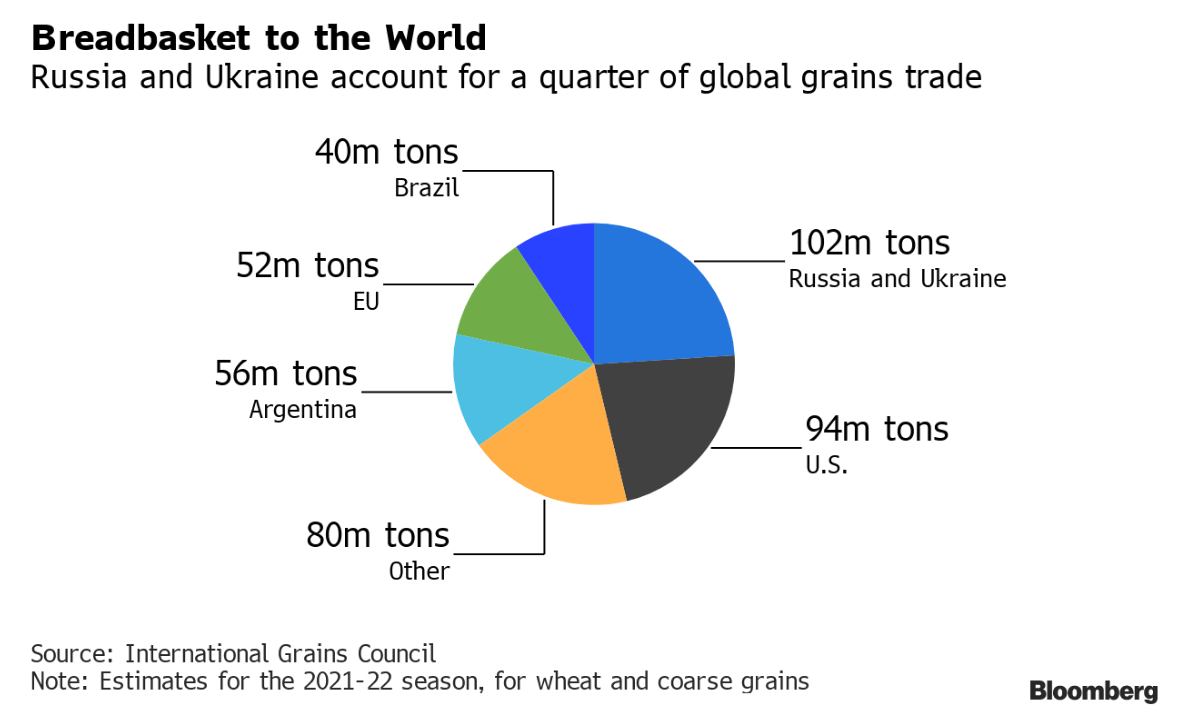
The curtailment of agricultural exports from Russia and Ukraine will have dramatic knock-on effects on global food supplies. Both countries are known as the ‘breadbasket of the world’ and are responsible for a quarter of the international wheat trade, about a fifth of corn, and 12% of all calories traded globally. Another major problem is access to fertilizers, as Russia has banned exports of the nutrients.

It’s not whether or not there will be a food crisis. It’s how big that crisis will be.”

Adding insult to injury, ZeroHedge tells us, “On top of everything else, now a highly pathogenic avian influenza pandemic is ripping across the United States, and it has already resulted in the deaths of almost 2.8 million birds.  Most of the birds that have died have been chickens or turkeys.  And since this was just in the very first month of the pandemic, there is no telling how bad it could eventually become.  What will the eventual death toll look like?  Will it be in the tens of millions?  That is definitely a possibility.  And what would happen if the bird flu mutates into a version that spreads easily among humans?  We might want to start thinking about that, because that is possible too.

I knew that the bird flu outbreak was bad, but I didn’t know that it had gotten this bad.  The following comes from a prominent farming website…

With new outbreaks in Iowa and Missouri, nearly 2.8 million birds — almost entirely chickens and turkeys — have died in one month due to highly pathogenic avian influenza (HPAI), the Agriculture Department said on Monday. The viral disease has been identified in 23 poultry farms and backyard flocks in a dozen states since February 8, when the first report of “high path” bird flu in a domestic flock was reported.

2.8 million dead birds in just one month.

Will next month be even worse?


8:45 am

Good Morning!

SPX futures rose to a weekend high of 4254.20, then declined to the flat line this morning.  Today’s expiring options are negative beneath 4250.00 and gamma turns short beneath 4200.00.  SPX has closed above 4200 for the past seven weeks, but the Cycles Model says the break should be conclusive today or tomorrow.

ZeroHedge reports, “US equity futures held on to modest gains overnight as the market desperately clung on to hope that the latest ceasefire talks between Russia and Ukraine which started on Monday, may yield results (clearly forgetting how the rug was pulled from under the market on Friday in an identical setup), which initially sent stocks higher especially in Europe, despite a surge in 10Y TSY yields to 2.10%, the highest since July 2019, two days ahead of the first Fed rate hike, and a complete collapse in Chinese stocks. And while U.S. index futures were still pointing to a positive open around 8am ET this gain is fading fast, with spoos now up just 0.5% after rising 1% earlier…

… as headlines from the Kremlin suggested that a ceasefire is the last thing on Putin’s mind.

  • *KREMLIN: RUSSIA WILL REALIZE ALL ITS PLANS IN UKRAINE OPERATION
  • *KREMLIN: UKRAINE OPERATION WILL BE COMPLETED ON SCHEDULE
  • *KREMLIN: RUSSIA DIDN’T REQUEST CHINA MILITARY AID FOR OPERATION *KREMLIN: RUSSIA HAS RESOURCES NEEDED TO COMPLETE UKRAINE ACTION

And while futures would normally be deep in the red by now, and will be shortly now that AAPL is at LOD…

  • APPLE FALLS TO SESSION LOW, DROPS 1.6% IN PREMARKET TRADING”


VIX futures rose to a morning high of 31.45 as it closed above its Cycle Top on Friday.  There has een an effort to keep markets in a narrow range ahead of the FOMC announcement and options expiration on Wednesday (VIX) and Friday.

ZeroHedge observes, “As Goldman’s head of FX sales Tony Pasquariello said on Friday, “next week is a huge one, featuring the FOMC on Wednesday and a major derivatives expiry on Friday.”

While much digital ink will be spilled in the next 48 hours dissecting the Fed’s next move which will most likely be the first 25bps hike in over two years, instead we will focus on next Friday’s March options expiration, which sees a massive $3.3tln of derivative notional expiring, not only right after the FOMC decision but also in the midst of a complex geopolitical situation.

Overall, some 30% of S&P open interest expires on March 18.”


TNX broke out above its February 15 high at 20.65 this morning.  The Cycles Model calls for 5 more weeks of levitation into the next Master Cycle (high).  This may be a rally with exceptional strength, as the Cup with Handle formation implies.


USD futures pulled back to 98.74 as it consolidates prior to its final push higher.  This week may gather strength as USD may actually make a throw-over above the upper trading channel trendline at 100.00.  This panic move into the USD may meet with a sudden reversal late next week, so don’t be fooled.  This may be the final surge before a massive decline.


Crude oil futures have come down to 102.56 this morning as WTIC may test the upper trendline of its Broadening Wedge formation.  The Cycles Model suggests a quick decline beneath its trendline and Cycle Top at 98.73 in the next week.  This implies a sudden decline in liquidity over that same period.


Posted in Published | 1 Comment

March 11, 2022

1:40 am

The range of the SPX appears to be defined by the Lip/Neckline at 4200.00 on the bottom and Short-term resistance at 4292.88 at the top (Max Pain zone is at 4280.00).  Today’s options go negative at 4250.00, so there is not a lot of wriggle room.  The Fed may be concerned about the bullishness that seems to underlie the market with massive stock buybacks, keeping the SPX buoyant.  Most speculators simply don’t know what to make of our current predicament, so they have become day traders in options, trying to front-run the next move.  The turnover is nearly triple the underlying positions.   There is no need to explain the consequences of a serious breakdown.

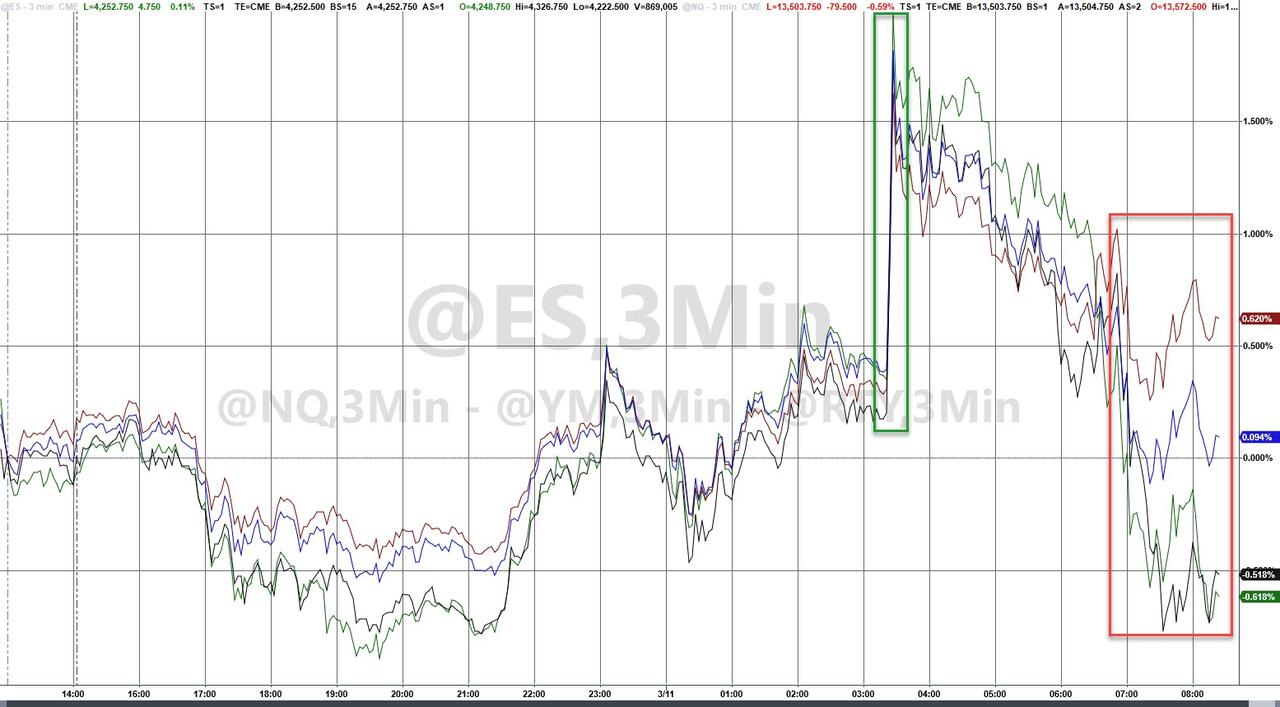
ZeroHedge explains, ” The earlier spike in US futures – following somewhat optimistic tones from Putin – have all been erased by actual events and the reality of significantly more unhappy America than expected (from UMich)…

However, as Nomura’s Charlie McElligott details below, there is a much stronger dynamic at play that is driving the daily roller-coaster in stocks – and may well continue through the FOMC next week (and the massive $3.3 trillion options expiration next Friday).”


8:55 am

Good Morning!

SPX futures are are testing Short-term resistance at 4296.30 this morning as dealers look for an excuse to bull up the SPX out of the put-heavy zone beneath 4275.00.  Now they must maintain this level throughout the day as options expire at the close.

ZeroHedge reports, “Here comes another rollercoaster of a day for markets.

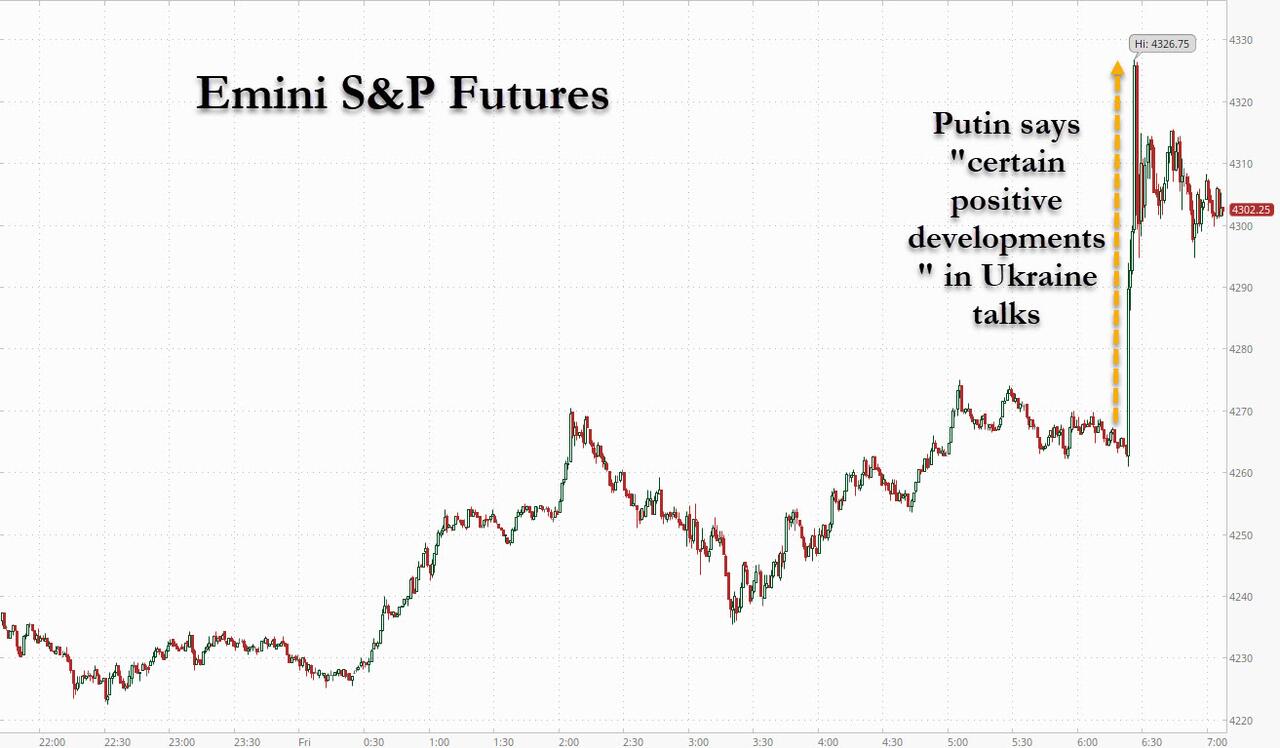
In a rerurn of last week’s (transitory) Ukraine war “ceasefire” euphoria which fizzled almost as fast as it emerged, a little after 6am ET on Friday morning, futures which had been trading rangebound for much of the overnight session, soared 60 points in seconds after Interfax reported that according Putin told his Belarusian counterpart Alexander Lukashenko that “there are certain positive developments, as far as negotiators from our side informed me” adding that “Talks are happening almost daily.”


VIX futures were pushed down to a morning low of 28.84 as options play an important part of the VIX, as well.  Calls dominate the March 15 expiration at 30 and above, so todays smash-down may have been an effort to manage market sentiment and smooth out volatility.

ZeroHedge comments, “We were wondering when we would see a Jerome Kerviel-inspired prop trading blow up as a result of the recent market turmoil, and this morning we got it. According to Bloomberg, Morgan Stanley derivatives trader Hamza El Hassani, is leaving the firm after racking up tens of millions of dollars in losses following the recent burst of market volatility.

El Hassani, who traded dividends in the New York-based bank’s equities division, is leaving the bank after his trading book blew up racking up losses “less than $50 million”, Bloomberg reports citing people with knowledge of the matter.”


TNX opened above the Cycle Top support/resistance at 19.84 and may trade above this support for the duration of Wave 3.  The current Master Cycle may continue through the week of April 18, according to the Cycles Model.


Posted in Published | 1 Comment

March 10, 2022 – Wash, Rinse, Repeat

8:00 am

Good Morning!

SPX futures have declined to a low of 4229.80 as I write, giving back nearly half of yesterday’s bounce before the open.  This attests to the grip that the dealers and hedge funds have on the market, as the SPX closed at Max Pain again.  Note that the rally closed in the correction zone, about 89% of the top in January and the 50% Fibonacci retracement was 4287.32.  The vast majority of options buyers are buying short-dated options that can whipsaw investors.  The dealers may soon have their comeuppance.  We will know the time has arrived when they start crying for a bailout.

ZeroHedge reports, “After yesterday’s optimism-inspired, negative-delta triggered melt up in stocks, futures have slid significantly overnight as lack of options market ‘rampage’ collateral (until the cash open) combined with a material lack of progress in the first high-level peace-talks between Russia and Ukraine stole the jam from the market’s donut.


VIX futures staged a comeback, rising to 34.02 this morning.  Commentators observe that the market may be near peak capitulation and a recovery may be around the corner.  A true capitulation (bear market bottom) would see none of this malarkey.

Zerohedge comments, “If you are short and want to feel really stressed

The move yesterday was brutal. Shorts were carried out on stretchers. It sure looks like we are “past peak” capitulation in terms of hedge fund flows. AND there is a wall of money that will support equities. AND you can make a case that valuations are attractive. AND maybe mega-cap tech is waking up again as proper bull market generals. OR maybe this was just a classic bear market squeeze and we should once again sell the rip very soon.

Closer to the end than the beginning of the discretionary de-risking

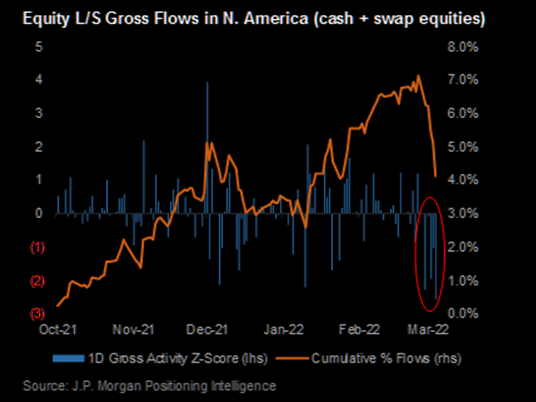
JPM loves the smell of capitulation among hedge funds. JPM Position Intelligence team: “Among Equity L/S funds, we’ve seen 7 consecutive days of active de-grossing as longs have been sold and short covered. Looking back over the past few years, the level of active de-grossing is the biggest aside from Mar ’20 (Covid) and Jan ’21 (Retail Squeeze). Furthermore, the duration of the de-grossing is nearing the duration of past big events, which lasted from 8-12 days)”


NDX futures dropped to a morning low of 13510.00, brutalizing the longs taking the plunge at the end of the day.


TNX is challenging the Cycle Top resistance at 19.75 this morning.  This move may be spent, as there is no indication of strength left in the Cycles Model.  In addition,   the EW structure suggests a pullback.

ZeroHedge reports on yesterday’s auction, “After yesterday’s disappointing 3Y auction, which was rocked by the rollercoaster swing in markets on a day-old AFP report, moments ago the US Treasury just sold $34BN in 10Y paper (in a reopening of Cusip CDY4) which came just as the FT was sending out fake news that the UAE had reached out to OPEC+ to urge a production boost, which sparked a flash crash in oil and unleashed a new volatility shockwave across assets.

And, just like yesterday, today’s auction left a lot to be desired, with the bond stopping at 1.92%, tailing 0.3bps to the 1.917% When Issued, and just above last month’s 1.904% high yield.This was the highest yield on a 10Y auction since July 2019.

The Bid to Cover predictably dipped from 2.68 to 2.47, the lowest since December, and  below the 6-auction average of 2.53.”


USD futures made an overnight low of 97.70 and bounced.  It may be due for a (minor) Trading Cycle low in the next couple of days, followed by the final probe to 100.00 during the week of March 21.


Crude oil bounced to 114.84 this morning, raising hopes of investors of a resumption of the bull market.   Crude is on day 247 today leaving another 1-2 weeks for a final push higher.  The EW structure appears complete, but the top may be extended in the corrective phase (Wave B).  On the other hand, should WTIC decline beneath the Cycle Top support at 98.48, a significant decline may follow.

ZeroHedge observes, “It was just last June when we asked if “ESG will trigger energy hyperinflation“, explaining that the progressives’ ESG agenda, “is unwinding the shale oil revolution. As recent events at Exxon and Shell have shown, the pressure on oil companies to reduce oil and gas exploration and adapt their business models has increased significantly over the past few months” (incidentally the answer to our rhetorical question was “yes”).

We added that “ESG is a negative supply shock that internalizes the climate cost of the production of goods and services. This negative supply shock will be inflationary until technological progress absorbs these costs. That could take years.  Moreover in Europe, it could garner enough of political support to justify a more aggressive fiscal policy despite the constraints at the German or EU levels.”

Meanwhile, the impact of ESG on oil companies has been to depress Capex spending to the lowest level in decades, leaving the energy sector entirely unprepared for any energy price spike, as it simply did not have the capacity to pump as much oil as may be needed.”


Gold futures bounced to 2015.00 as a brief period of strength ends the week.  However, a consolidation may have begun.  Gold may have begun a 6-week correction period before resuming its uptrend.  A correction this long suggests a possible triangle formation that ma frustrate investors.  Support is at the Cycle Top support at 1905.50.

ZeroHedge remarks, “Gold – everybody sucked in?

The “easy” trade in gold is long gone (outlined here on Feb 11). Now comes the “frustrating” part for most that have missed buying at decent levels and/or sell at recent euphoria levels. Gold needs to consolidate before anything meaningful can occur again according to us. If you are running “must be longs” here but think we are due for a consolidation, we see overwriting as interesting set ups. Gold volatility has exploded higher and offers great yield enhancement plays.”


Posted in Published | Comments Off on March 10, 2022 – Wash, Rinse, Repeat

March 9, 2022

12:32 pm

SPX may have stalled near the 50% retracement level at 4287.32 at the 4.3-day mark from the Wave 2 high.  The dealers and hedge funds may have quit covering their shorts (buy high and sell low).  The main issue for the rest of the day is to keep the SPX out of short gamma territory.

ZeroHedge explains, “Why such a violent equity squeeze on such ‘meh’ Ukraine / Russia headlines?

Nomura’s Charlie McElligott summarizes the long and the short of it succinctly below (Spoiler alert – Same shit, different day!)

As we’ve repeated numerous times, stocks are so deeply-immersed in Negative Gamma and critically, EXTREME “Short Delta” location for Options Dealers from all that downside hedging (after yesterday’s session, $Delta for SPX / SPY 0.2%ile, 0.0%ile for QQQ, 0.4%ile for HYG, 4.1%ile for IWM) that this means violent rallies which have to be “bot into” as Dealers cover shorts in futures.

Accordingly, McElligott has noted that any rally would have potent kindling for a short-squeeze from said “negative Delta,” as all those downside Puts are torched as we rally away from lower strikes, and the coupled “short hedges” from Dealers in futures will be bot back / covered.”


9:45 am

GKX may have made its Master Cycle high yesterday, on day 257.  This may be a case of the lack of liquidity in the market trumping supply and demand, at least temporarily.  Should that be the case, we may see GKX correcting down to the mid-Cycle support at 514.65 by the week of March 21.

ZeroHedge remarks, “The world is heading for a “catastrophic” global food crisis as a result of the war in Ukraine, which will cause “hell on earth” for food prices, according to experts.

“Half the world’s population gets food as a result of fertilisers… and if that’s removed from the field for some crops, [the yield] will drop by 50%,” Svein Tore Holsether, head of agri company Yara International, told the BBC.

Known as “the breadbasket of Europe,” Russia and Ukraine export around a quarter of the world’s wheat and half of its sunflower products, such as seeds and oil.

“For me, it’s not whether we are moving into a global food crisis – it’s how large the crisis will be,” said Holsether, noting that increasing gas prices were causing a steep rise in the cost of fertiliser.”


8:10 am

Good Moring!

SPX futures have rallied to a morning high of 4251.70, a strong 77.5% retracement of the decline from yesterday’s high.  Today’s options expiration is in short gamma beneath 4250.00.  Dealers and hedge funds are attempting to gain elevation above that level, so as to cause the least damage to their book.  Never mind the investors.

Equities are near the half-way point of a minimum 8.6-day decline potentially ending on March 15.  The next 4.3 days are the most intense, giving way to multiple probabilities of limit down days.  The key is the final and decisive decline beneath the neckline/Lip of the doubly bearish formation.

ZeroHedge reports, “After two days of sheer market insanity, including Monday’s furious plunge and Tuesday’s rollercoaster session, U.S. equity futures jumped after 4 straight days of losses, following European equities higher, as Ukraine optimism won, at least initially, over fears about high inflation and global stagflation as a result of soaring commodity prices, sparking a furious Delta squeeze (as we will show shortly in a subsequent post).

At 730am ET, Nasdaq 100 contracts were up 2.1% while S&P 500 futures gained 1.6%. The underlying benchmark fell for a fourth straight session on Tuesday to close at its lowest since June 2021. Dow futures rose 1.5%.  A bond selloff extended as investor focus turned to upcoming central-bank rate decisions, while oil prices reversed a rally driven by President Joe Biden’s ban on fossil-fuel imports from Russia. . The dollar weakened for the first time in five days, as haven demand waned. Bitcoin soared more than 10% over $42,000 spurred by optimism about an impending U.S. overhaul of crypto oversight that Treasury Secretary Janet Yellen called “historic.”


VIX futures made an overnight ow at 32.38, stepping back from a steady march upward.  It may be suing Short-term support (not shown) at 31.33 as a base for its continued advance.  The Model suggests a high likelihood of testing the neckline in the next 24 hours.

The NYSE Hi-Lo Index made a deeper low at -392.00 at the close.

ZeroHedge comments, “What if the world survives – the VIX guy is back

We haven’t heard from the VIX guy in a while, but he called us earlier today. He hasn’t sounded this bearish pretty much ever. When you hear about nuclear wars from the VIX guy you really start thinking about whether or not fear has gone ahead of itself? To summarize: he sees all commodities surging further, the geopolitical situation spiraling out of control, Europe basically going back to stone age etc. His biggest take is that VIX and the European version, V2X, are going to the moon. We strongly disagree. It is time for a thread on fear…

What fear is the market pricing here?

Regular readers of TME know that the crowd tends to load up on protection too late and at way too rich levels as they tend to confuse direction with pace. Don’t forget that a 1% daily move translates to 16% implied volatility (approx). People have been paying very high premiums for protection lately. We find selling premium interesting plays here, both for overwriting positions, adding longs or simply selling people some rich fear. One example is the SX5E 3500/3800 strangle going for just above 200. That is collecting around 5.5% premium with “happy” to buy more at 3300 and happy to sell at 4000. We find this strategy extra interesting for people that want to add to longs, but are happy to sell a rip…”


TNX continues to make new highs off the Master Cycle low.  It may be due for a pullback over the next week, especially when stocks resume their decline.  However, the appears to strengthen over time, especially in April, as Wave 3 develops.

ZeroHedge comments, “The Federal Reserve has all but cemented expectations for a 25bps rate hike next week. But, events have changed a lot in the last couple weeks that raise a faint hint that the Fed may not hike, despite elevated, persistent inflation.

What makes us question whether the Fed achieves lift-off next week? Three things: 1) deterioration of growth expectations for 2022, 2) the VIX, and 3) fed funds futures.

Since the peak in September of 2021, expectations for real GDP growth for 2022 has been steadily getting marked down. This helps explain the slide in the average stock this year—as measured by the Valueline equal weighted index. Does the Fed tighten into slowing growth?


USD futures retreated to an overnight low of 98.39 as it forms Wave [iv].  We may see USD decline further to its Cycle Top at 97.94 before its final push to 100.00 during the week of March 21.


Crude oil futures declined to 115.53 this morning, confirming the Master Cycle high on Monday.  This may be an excellent entry point for a short position.  However, the chart does not offer any support levels until the Cycle Top at 97.79.  Pick our best level or wait for a bounce to place you order.

OilPrice.com reports, “IEA Chief Fatih Birol: Our members are ready to release more crude from their SPR’s to tame surging crude prices.

  • Birol: “We are ready to [release] as much oil as is needed,”.
  • Last week’s announcement of the oil release failed to stop rallying oil prices.

The members of the International Energy Agency are ready to release more oil from their strategic emergency reserves to tame the surging oil prices, the IEA’s Executive Director Fatih Birol told the Financial Times on Tuesday.


Gold may have made its belated Master Cycle high at day 280 yesterday, as suggested.  Gold futures dropped to an overnight low of 1981.20, potentially confirming that event.  Spike highs such as this are hard to negotiate at the turn, especially after being late.  However, the Master Cycle immediately preceding this was 250 days, yielding an average at 265 days for the two Master Cycles.  The probable target for a Wave (4) correction appears to lie near the Cycle Top at 1901.37.


Posted in Published | 1 Comment

March 8, 2022

12:21 pm

SPX opened lower, but formed a corrective bounce that has come within points of a 38.2% retracement at 4256.77.  The 50% retracement is at 4287.32, but I wouldn’t count on it.  The decline may soon be re-established after dealers finish unwinding their shorts…only to pick them up again at the end of the day.  Gamma remains short beneath 4350.00.  Selling pressure may soon pick up.

ZeroHedge comments, “Picking up where he left of with his “stuff is beginning to break” magnum opus yesterday, this morning Nomura’s Charlie McElligott writes that on top of the already well-established macro supply-demand “inflation shock” catalysts of the past 2 year period, the Ukraine-linked Commodities price/collateral/dollar funding squeeze -> “margin-call exercise” (which left a prominent Chinese trading tycoon significantly poorer after billions in margin calls), further amplifies the recent price-action in pockets of Energy, Metals and Ags.”


11:30 am

It appears that my “itchy trigger finger” on the sell button (GKX) last Friday wasn’t such a bad call after all.  GKX has now declined beneath the Cycle Top support at 579.25 and a massive Head & Shoulders neckline at 570.50 that appears on the monthly chart.  It appears that the loss of liquidity overrides the growing food crisis temporarily.  The next Master Cycle (low?) comes up during the week of March 21, only two weeks away.  GKX is now on a sell signal with the potential target at the mid-Cycle support at 509.36.

I have been an avid gardener all of my life, so the following missive from ZeroHedge comes as no surprise, “Spring in the northern hemisphere is two weeks away, and interest in planting gardens could rise as the breadbasket of Europe was choked off by the Russian invasions of Ukraine, jeopardizing global food exports resulting in skyrocketing prices.

Even before the turmoil in Ukraine, American households were under pressure due to soaring food and gas prices. The invasion just made things a lot worse as commodity prices jumped the most last week since the stagflationary period of the mid-1970s.

New UN global food price, released on Friday, showed global food prices in February surpassed a previous record set in 2011. About a quarter of the international wheat trade, about a fifth of corn, and 12% of all calories traded globally come from Ukraine and Russia. Food exports in the region have been halted due to conflict and sanctions.

This leaves us with a shrinking global food supply that may further price increases. Since spring is just weeks away, Americans will be in for a shock at the supermarket as the latest round of food inflation makes it to the store shelves. To mitigate the impact of grocery bills tearing apart household finances — interest in farming and planting gardens could take off and help expand the food supply.”


7:30 am

Good Morning!

Those of you who woke up this morning to see the SPX futures higher missed an exciting night.  The roller coaster went down to 4142.80 before bouncing back to 4235.40.  The breadth of these moves is staggering.  Within 24 hours, the SPX declined 4.3%, then rallied 2.2%.  That completes Wave [i] of 3 of (3).  The next decline is a   triple play Wave [iii] of 3 of (3).  Wave threes are never the smallest, suggesting a high probability of a limit down in the next few days.

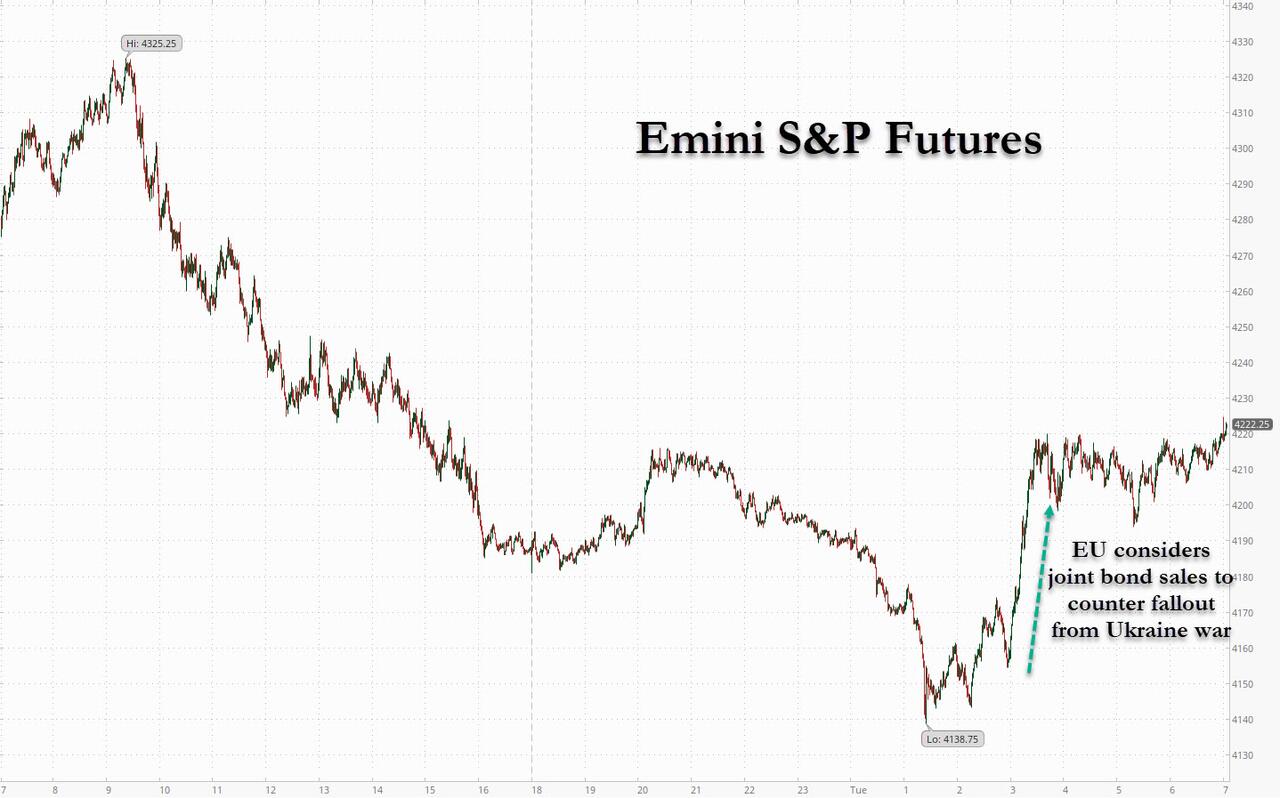
ZeroHedge reports, “Futures rebounded from yesterday huge loss, and after touching a session low of 4,138, S&P futures bounced shortly after the European when Bloomberg reported that the European Union was set to reveal a quasi “Marshall Plan” this week to issue issue “potentially massive” joint bonds to fund energy and defense and help counter the fiscal fallout from Russia’s invasion of Ukraine (how Europe will do that at a time when QE is ending and buyers for global debt are shrinking fast amid surging rates remains unclear). S&P 500 futures gained 0.7% following the benchmark index’s biggest loss since October 2020, while Dow futures rose 0.6%.  Contracts on the Nasdaq 100 were up 0.6% at 7:15 a.m. Bonds and the dollar dropped, and the euro strengthened. The commodity melt up continued: nickel was halted on the LME after soaring 250%, oil traded just shy of $130 and gold was above $2000.”


VIX futures retreated to a low of 34.40, remaining within yesterday’s trading range, the highest close since the week of October 26, 2020.  Tis now has traders concerned, being the eighth close over 30.00 since February 23.  This is no longer being viewed as a one-off event.   The target for Wave 3 has become imminent.

The NYSE Hi-Lo Index closed at -300.00.  The Hi-Lo has awakened to a new plunge with a possible target of -2450.00.


NDX futures declined to an overnight low of 13107.20.  It did not take out the trendline at 13065.40.  However, it only bounced to 13420.40, unable to reach the 2-hour Cycle Bottom resistance at 13483.25.  The decline appears to have resumed.

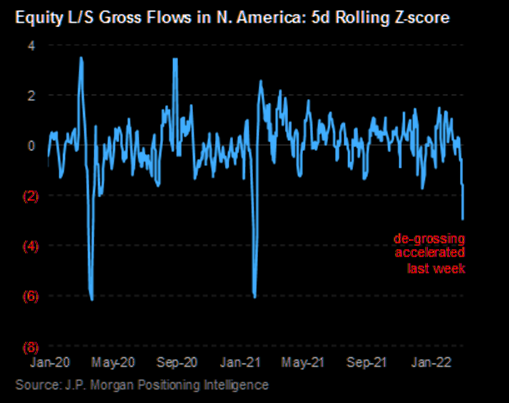
ZeroHedge observes, “Hedge Fund Panic selling (#1)

Equity L/S Flows: de-grossing accelerated last week and net selling also picked up

Source: JPM

Hedge Fund Panic selling (#2)

The L/S de-grossing in N. Am. last week was about a 3z event and the largest of the past 2 years aside from late January 2021 and mid-March 2020 (which were about 2x the current magnitude). Net flows were also negative throughout last week for this strategy—the 5-day net selling was >1.5z and the largest since the week ending December 17, 2021. Alongside the selling, net leverage for Equity L/S funds fell almost 3% last week to put it back in line with mid-December lows and the lowest since 3Q20.


USD futures pulled back to 98.88, still within yesterday’s trading range.  The Cycles Model suggests a steady rally until the week of March 21, where it may make a final burst before its reversal.  Depending on the strength of the final probe, the target appears to be near 100.00.


TNX gapped higher this morning, confirming yesterday’s buy signal.  TNX is showing unusually large moves due to its high level of trending strength in the Cycle.  This may last for the balance of the week.  The rally may last until the week of April 18, leaving plenty of time for new highs.


West Texas Intermediate Crude pulled back from a high of 130.50 to an overnight low of 117.25 on the news of the prospective energy bond being floated by the EU.  This has all the marks of a trend reversal on day 244 of the Master Cycle.  While this is two weeks early from the average length of a Master Cycle, consider this; The Master Cycle immediately prior to this was 277 days long.  The average of the two is 260.5 days, which falls in line with the Cycles Model.

ZeroHedge reports, “Confirming yesterday’s speculation that a ban on Russian oil imports is imminent, moments ago Bloomberg reported that the Biden administration is set to impose a ban on U.S. imports of Russian energy as soon as Tuesday without the participation of European allies, who as we discussed yesterday have been vocally – especially in the case of Germany – against such a blanket ban (because the import much more Russian oil and gas than the US).

The ban will include Russian oil, liquefied natural gas and coal, according to two Bloomberg sources who noted that the decision was made in consultation with European allies, who rely more heavily than the U.S. on Russian energy. In other words, the allies agreed to disagree on how important Russian oil is to them.

ZeroHedge observes, “Canada’s oil could replace American imports of Russian crude, the top officials of the oil-producing province Alberta said this weekend.

As talks about banning Russian oil imports in the United States and its European allies intensify, reports have started to emerge that the U.S. Administration could be looking to persuade Saudi Arabia to pump more oil or lift some sanctions on Venezuela to help fill the gap that a Russian oil embargo would open.

On Sunday, U.S. Secretary of State Antony Blinken said that the United States and its European allies were in “very active discussions” about banning the import of Russian oil over Putin’s war in Ukraine.

Even without sanctions on Russian oil, some of the biggest U.S. importers of Russian crude oil have started suspending their purchases of the commodity.”


Gold futures made a new panic high of 2027.80.  This may indeed be the Master Cycle high, as the next one isn’t due for two months.  I will keep you posted.  In the meantime, the EW pattern appears complete.  Consider taking profits in gold at this time.


Posted in Published | 1 Comment

March 7, 2022

3:23 pm

Liquidity is leaving equities quickly as BKX indicates today.  It crossed the neckline on Friday and is now on its way to a minimum 20% decline from the neckline.  The 2-year Ending Diagonal formation and the Orthodox Broadening Top both suggest s probable target nearer to 50.00 by June.


3:13 pm

NDX is beneath its 2-hour Cycle Bottom at 13496.13 and SPX is beneath its Cycle Bottom  at 4220.00, increasing the probability of a melt-down going into options expiration today.  SPX breaks at 4200.00, its Lip/Neckline.

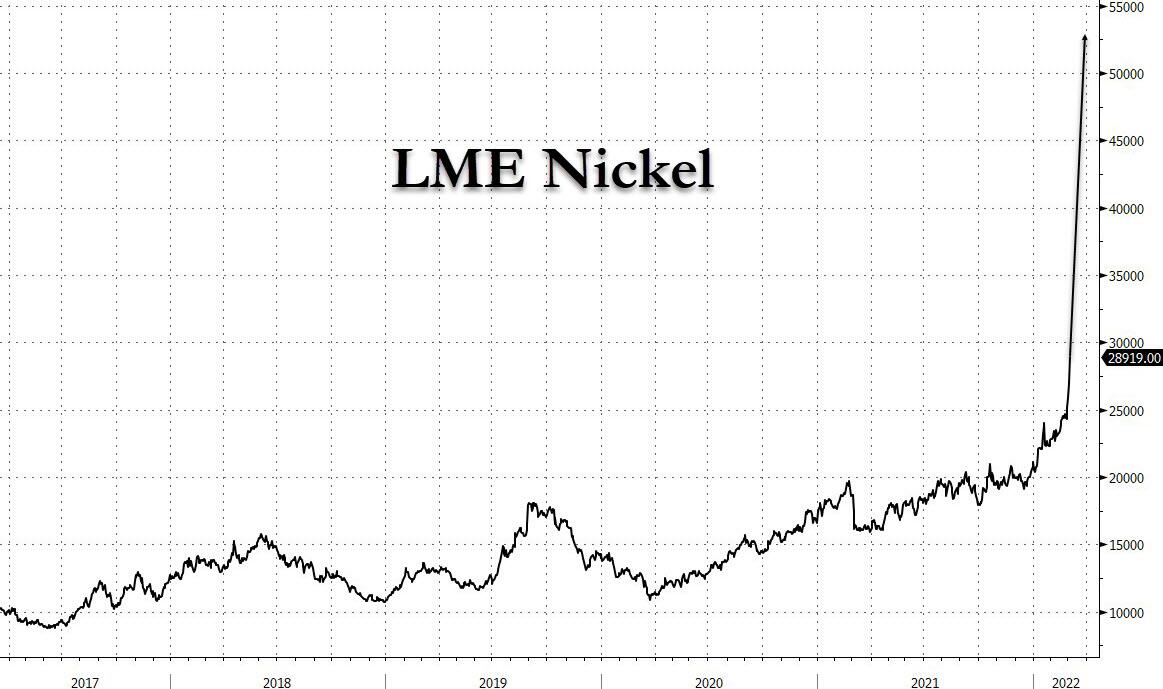
ZeroHedge observes, “One look at today’s absolutely bananas explosion in LME Nickel prices which soared  82% in one day to a record $52,700…

… shows that commodities inflation panic was in full-swing earlier overnight, where war-related price-shocks are trading through what Nomura’s Charlie McElligott writes was “escape velocity” on likely stop-outs from “Shorts” (think commodity producers and traders who were short futures to hedge prices, similar to the margin call experienced by Peabody), and with the market seemingly realizing there is little that CB monetary policy can do to control it.”


12:56 pm

Last Friday I suggested taking early profits as GKX stumbled after appearing to have completed its rally.  That was day 253.  Today is day 256.  I don’t have anything to add, other than the possibility of reaching 600.00 in the next couple of days.  A correction here is likely to take GKX down to its mid-Cycle support at 504.69.

ZeroHedge reports, “The condition of China’s winter wheat crop could be the “worst in history,” the agriculture minister said on Saturday according to Reuters, raising concerns about grain supplies in the world’s biggest wheat consumer. Speaking to reporters on the sidelines of the Chinese regime’s annual political meetings, Minister of Agriculture and Rural Affairs Tang Renjian said that heavy rainfall last year delayed the planting of about one-third of the normal wheat acreage.

A survey of the winter wheat crop taken before the start of winter found that the amount of first- and second-grade crop was down by more than 20 percentage points, Tang said.

“Not long ago we went to the grassroots to do a survey and many farming experts and technicians told us that crop conditions this year could be the worst in history,” he said. “This year’s grain production indeed faces huge difficulties.”


12:45 pm

SPX may be primed for a bounce off the 2-hour Cycle Bottom at 4220.00 and the Lip of the Cup with Handle at 4200.00.  The bounce may last until tomorrow’s open.  The only visible resistance is Short-term resistance at 4341.16.  The SPX is in short gamma beneath 4250.00.  Should it continue to decline beneath the trendline, we may see a panic decline that may last up to a week.

ZeroHedge remarks, “Unlike the Trump Administration, where even the smallest dip in stocks was met with a furious barrage from the now-banned presidential twitter account urging Americans to BTFD, the Biden administration has been silent on the recent tumble in risk assets, which is understandable since it is far more preoccupied with containing soaring inflation. However that changed today, when Nellie Liang, Under Secretary for Domestic Finance, delivered remarks to the Institute of International Bankers’ Annual Washington Conference, in which among broad remarks about the state of the US financial system including stablecoins and climate change, and she touched upon the growing strain in the financial system, to wit:

  • markets showing some signs of strain
  • investors are meeting elevated margin calls without delay
  • investors are showing little concern about solvency or liquidity stresses at domestic financial institutions”


8:30 am

Good Morning!

SPX futures declined to a low of 4240.80 before bouncing on news of a possible cease-fire in the Ukraine.  It has rallied above 4300.00 where there are 4404 put contracts expiring today.

ZeroHedge reports, “ot much has changed since our market update last night which saw all risk assets collapse and in many cases set to open in bear markets, amid a soaring panic that the US will impose a unilateral oil embargo on Russia leading to an energy supply shock and global stagflation, while safe havens such as gold, treasuries, and the dollar are exploding higher not to mention crude which was last trading at $125 after briefly rising above $139 at the start of the session. Commodities from grains, metals have also surged on concerns of chaos in raw-material flows due to the invasion and sanctions on Russia that are turning the resources powerhouse into a global pariah. Commodity-linked currencies strengthened.

S&P 500 e-mini futures were down as much as 2.1% earlier before trading 1% lower 7am in New York after a faint glimmer of hope of de-escalation when the following headlines hit Reuters:

  • KREMLIN SPOKESMAN SAYS UKRAINE MUST AMEND CONSTITUTION AND REJECT CLAIMS TO ENTER ANY BLOC
  • UKRAINE MUST RECOGNISE CRIMEA AS RUSSIAN, AND DONETSK AND LUGANSK AS INDEPENDENT STATES
  • IF THESE CONDITIONS ARE MET, THEN RUSSIAN MILITARY ACTION WILL ‘STOP IN A MOMENT’ – SPOKESMAN

And now we wait for the latest Ukranian refusal of these conditions. Meanwhile Nasdaq futures retreated 1.7%. Brent oil was up as much as 18% today, trading around $125 a barrel as the Biden administration is considering whether to prohibit Russian oil imports into the U.S. without participation of allies in Europe, at least initially, according to a Bloomberg report.

Update:  ZeroHedge reports, “Belarusian state TV has said the Russian delegation has arrived at the location where on Monday at about 14:00GMT/09:00EST the third round of talks with the Ukrainian side are set to begin. So far the ongoing talks have been focused on establishing and maintaining humanitarian corridors for the safe evacuation of civilians still trapped in cities under siege by Russian forces. But these have been erected and collapsed in various locations with limited effectiveness, given Kiev has accused Russia of breaking the temporary ceasefire pauses through the resumption of shelling, something which Russia’s military has rejected.

Just ahead of the meeting, the Kremlin issued a list of demands to be accomplished if Ukraine wants the Russian invasion to be halted immediately. These includes, according to the Kremlin spokesman, the recognition of Crimea as part of sovereign Russian territory, as well as Donetsk and Lugansk as independent states. ”


VIX futures rose to a high of 36.52 this morning before scaling back on the latest Ukrainian development.  The Cycles Model shows growing trending strength this week with a possible Master Cycle peak next week.

ZeroHedge comments, “When VIX at 35 looks tiny…

Our long term take of Europe being the “always sucker” remains intact. You don’t need much explanations, but when VIX at 35 looks “tiny” compared to Eurostoxx 50 “VIX”, V2X, you know things are not fine. V2X at 57.5 as of writing is very extreme. Sure we are far from the corona panic highs, but back then the world was ending. This is pure panic. The question is: “enough blood on the streets here”?”


TNX futures have risen to a morning high of 17.97 this morning and threaten higher  levels as trending strength returns.  It has exceeded the 50-day Moving Average at 17.88 and is on a buy signal.


NDX futures declined to 13532.60 this morning before bouncing back above the Cycle Bottom support at 13763.00.   The bounce may be fully resolved in the next 24 hours as the decline resumes.

ZeroHedge observes, “Last week, some on Wall Street were quietly gloating when the “Lehman Weekend” consequences predicted by repo guru Zoltan Pozsar failed to materialize and central banks did not flood global markets with a torrent of liquidity, in a repeat of what happened in September 2008.

In his latest not published late on Friday, the Credit Suisse strategist admits that “Yes, we got central banks’ need to step in to calm funding market pressures this week wrong (still no need yet)” but he counters that “we got the direction of spreads right – on February 24th we warned about an imminent sentiment shift in funding markets. There was no premium last week but there is some funding premium now, and it feels that things can get worse still.” So net-net, he concludes, “our call was absolutely right.”


USD futures hit a new high at 99.42 this morning before easing back.  The Cycles Model calls for a week of consolidation before moving higher.  The next Master Cycle pivot (high) may be due the week of March 21.  The final target may be the weekly Cycle Top at 100.47.


WTIC futures are coming down from a weekend high at 130.33 as tensions over the Ukraine ease.  The Cycles Model suggests a week-long consolidation with a probable Master Cycle top during the week of March 21.  The Possible target may be as high at 150.00

ZeroHedge reports, “One day after we reported that Germany had warned against a ban on energy imports from Russia, quoting Germany’s Economy Minister Robert Habeck who said “I would not advocate an embargo on Russian imports of fossil fuels. I would even oppose it,” adding that “we need these energy supplies to maintain the price stability and energy security in Germany,” and warning that “a shortage in supply could threaten social cohesion in Germany”, moments ago Bloomberg reported that Germany now openly opposes the push to stop Russian oil, gas imports.

“I’m not ruling out anything for the further development of this year,” German Finance Minister Christian Lindner tells reporters in Berlin when asked about the next steps against Russia. “At the current time, however, there is no new decision to be made.”

“The government insists that we do not take the initiative to end our imports of oil, gas and coal to Germany”


Posted in Published | 4 Comments