March 4, 2022

12:20 pm

GKX appears to have completed its Wave 5 of (1) today at 579.02 on day 253.  It may still rise for a few days, but taking profits may be the better option.  Sell all Ag-related ETFs.


12:02 pm

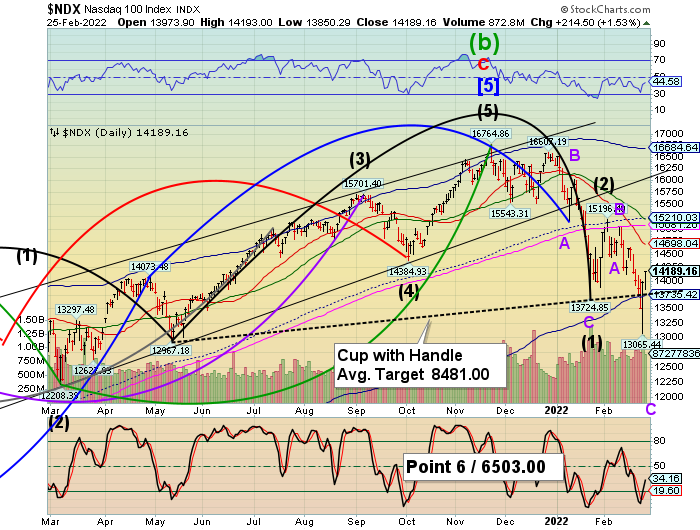
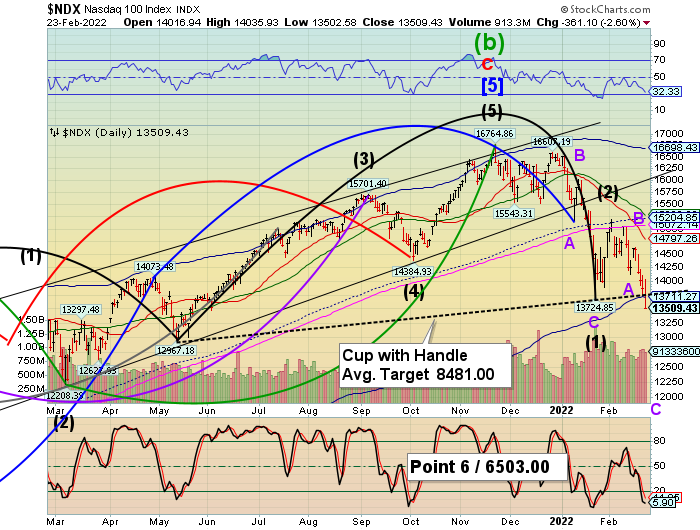
NDX is probing its daily Cycle Bottom support at 13764.00.  Once beneath it, the next target appears to be the Lip/Neckline at 13065.00.  It is tiptoeing into short gamma territory.

QQQ (336.38) is well beneath the Max Pain zone for today’s options expiration.  Short gamma begins at 335.00.  Will it bounce before the close, or give it all up?  Today’s action doesn’t look good.


11:05 am

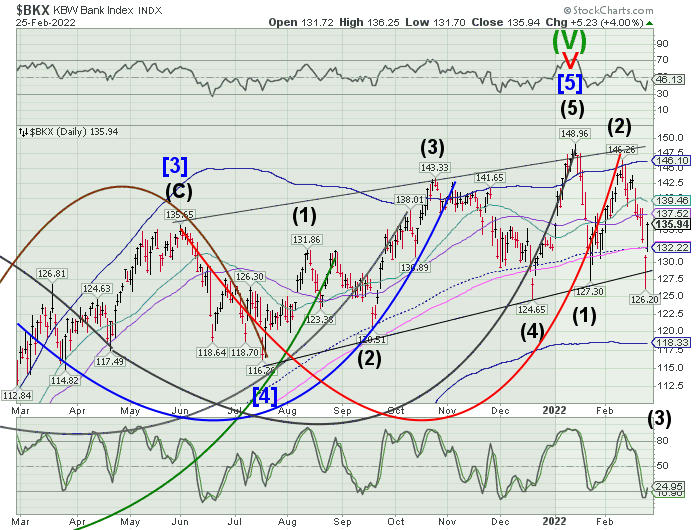
Our liquidity proxy, BKX has declined beneath the neckline of its Head & Shoulders formation at 126.00.  This gives all the indications of an impending crash in the markets.  What’s curious about this formation is that the current Master Cycle may have landed on February 24, on day 251.  The bounce took only a day before a reversal to a lower low.  Should that be the case, the new Master Cycle may run the entire month of March.

ZeroHedge reports, “…many did not think the EU would play the SWIFT card on Russia. It turns out they were correct…

SWIFT is the international payment system. Cutting off a top country from SWIFT access is a very big deal.

When the US and EU trotted out the SWIFT sanction card, I thought I got that one wrong. Closer inspection by Eurointelligence and others shows it’s Not So Swift After All.

FAZ informs us that the Swift sanctions are essentially dead in the water. Only seven banks, representing a quarter of the Russian banking sector, are subject to the sanctions. What happened is that once this sanctions list went through the mill of talks with member states, only this pared-down lists survives. The EU originally promised to hit 70% of the Russian banking system. One reason for the exclusion of Sberbank is the deposits held by savers in the bank’s EU subsidiaries. It would have triggered massive deposit insurance claims.”


10:37 am

The Ag Index is on a tear with another week to go in its Master Cycle.  Calculating targets for a rogue Wave may be an exercise in futility, as my previous target of 570.00 has already been exceeded.  GKX now exceeds its prior high made in March 2011 at 570.50.  At this point the best reference points are the round numbers.  The next round number target is at 600.00 with the next Master Cycle pivot due on March 9.

ZeroHedge reports, “This morning we listed some of the countries that are dangerously (and almost exclusively) reliant on Russia and Ukraine for their wheat imports, highlighting Turkey, Egypt, Tunisia and others…
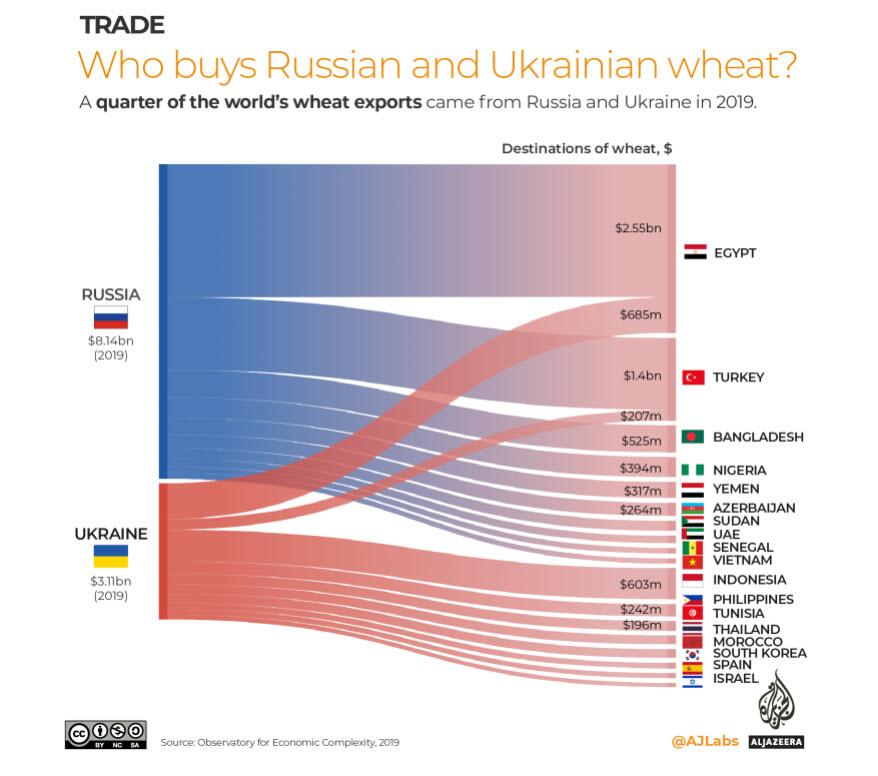
… which are facing an “Arab Spring” style food crisis (and potential uprising) in the coming weeks unless the Ukraine conflict is resolved.

And unfortunately, we can now confidently predict that the coming food crisis will strike every country that is using food fertilizer – which is all – because moments ago, Russian Interfax reported that as part of Moscow’s countersanctions, Russia has recommended fertilizer makers to halt exports, a move which will sent not only fertilizer prices orbitally higher, but all food prices will soon follow.”


10:30 am

Crude oil futures are consolidating within yesterday’s wide trading range.  The Cycles Model suggests another two weeks to the end of the current Master Cycle.  This Wave may rise to a range of 133.00 to 150.00 in that time.  The war is creating a rogue wave in commodities.

ZeroHedge reports, “Another day, another record discount for Russian Urals crude, which was offered at a price more than $22 below spot by oil trader Trafigura and still could find no giant…

… confirmed what we previously observed, namely that the commodity world is splitting in two: a bidless market for Russian oil, and (increasingly) offerless for non-Russian.


8:20 am

Good Morning!

I thought I’d start this Friday with a “big picture” chart showing the DJIA breaking down beneath the upper trendline of its 38.7 month-old Orthodox Broadening Top.  This morning’s DJIA futures have also broken beneath the daily Cycle Bottom support at 33548.41 for a second time, signifying a significant loss of liquidity and a loss of institutional support.  It is hovering near that area as I write.

8:35 am  ZeroHedge reports, “As noted earlier, it was difficult to get worked up about today’s jobs report in light of the barrage of geopolitical development, and yet if anyone needed a confirmation that the Fed will hike by 25bps in two weeks, they just got it when the BLS reported that in March, total jobs surged by a whopping 678K, much higher than the 423K consensus forecast, higher than last month’s upward revised 481K and the highest since last July’s 689K. However, offsetting this surge was the unexpectedly weak wage data, which saw a flat print in the monthly change in average hourly earnings vs expectations of a 0.5% increase (and down from 0.6% in February).


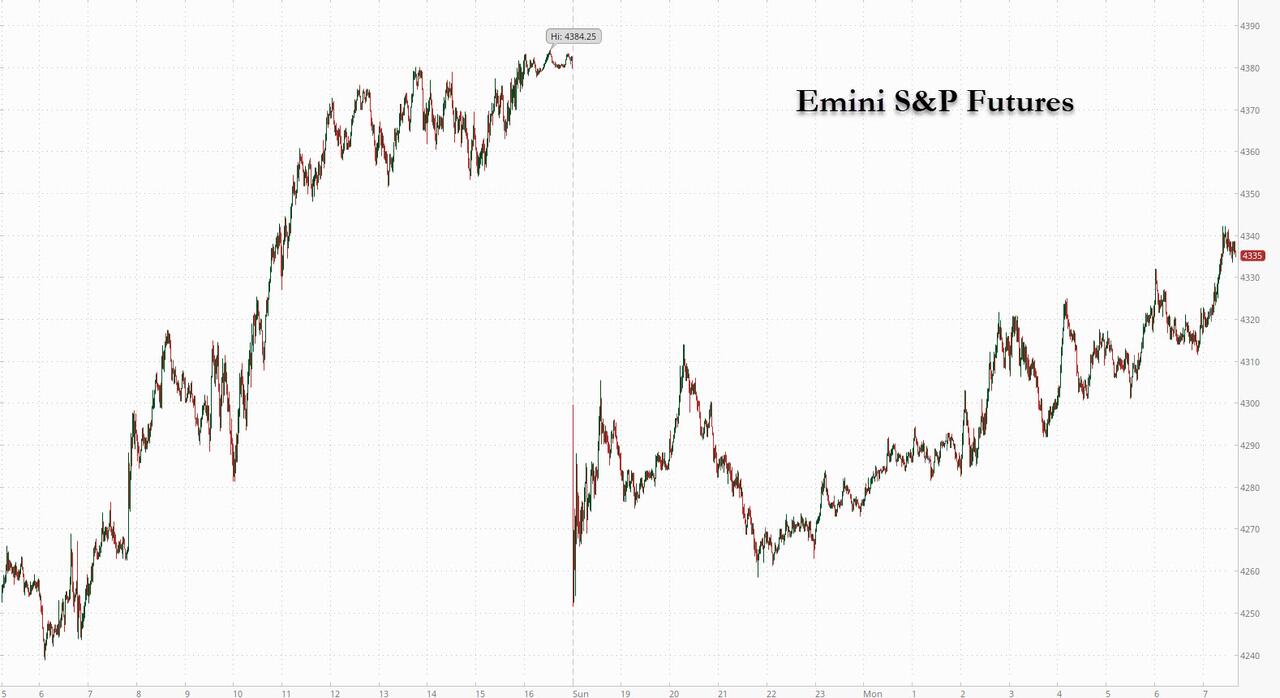
SPX futures have declined to an overnight low of 4287.00 before a bounce bringing it back above 4300.00.  Today’s options expiration is critical, since open interest is bearish (favoring puts) at 4350.00 and below, while gamma turns short below 4250.00.  The Cycles Model suggests a steep decline to the week of March 14, likely to be at least 8.6 days in duration.

ZeroHedge reports, “It has been another rollercoaster session, which saw futures tumble around 7pm ET following news that a Ukrainian nuclear power, Europe’s largest, had caught fire after alleged Russian shelling, and even though it largely turned out to be a false alarm with no damage to the NPP reactors or any radiation leaking, futures still have failed to recover much of the loss and were trading about 1.1% lower on concerns that the escalation of the war in Ukraine could have a stronger economic impact than anticipated. Contracts on the Nasdaq dropped 0.8% and Dow futures were 0.93% lower. As futures sold off, treasuries and gold climbed amid haven demand, while oil headed for its biggest weekly surge in almost two years. A dollar gauge rose to its highest level since July 2020, while the euro extended its decline below $1.10 for the first time since May 2020.”


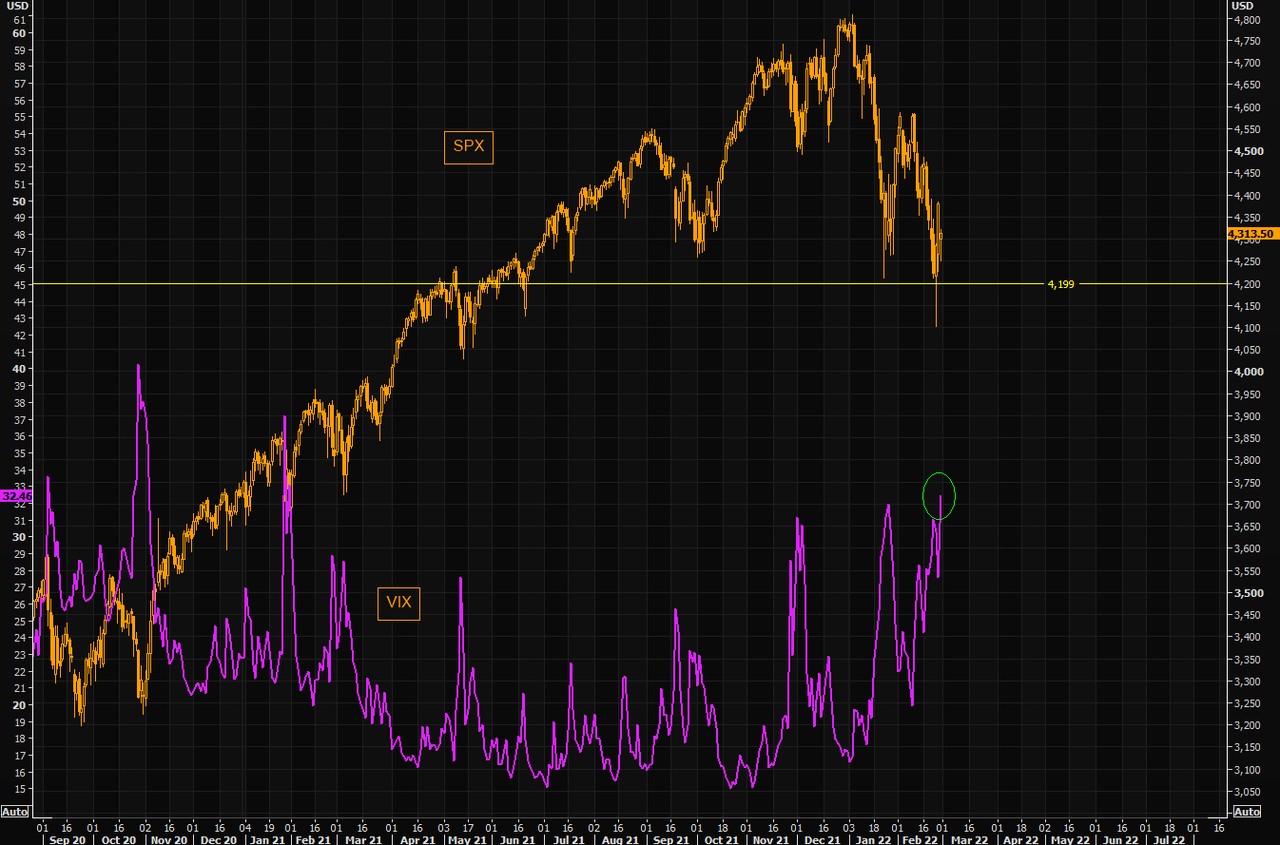
VIX futures made an overnight high at 34.49, reaching for the Head & Shoulders neckline.  A breakout suggests the minimum target at 63.78 may be met in the next two weeks.  The Cycles Model suggests this may be accomplished by the week of March 14.  The 17.2-month Ending Diagonal may be completely retraced by June. The Wave [3]  high for the VIX is likely to be over 90.00, since Wave threes cannot be the smallest Waves.  The monthly chart shows a massive Head & Shoulders with a possible target of 162.38.  Don’t hold your breath on this one.  I’m only saying it’s possible.  A rogue Wave, perhaps?


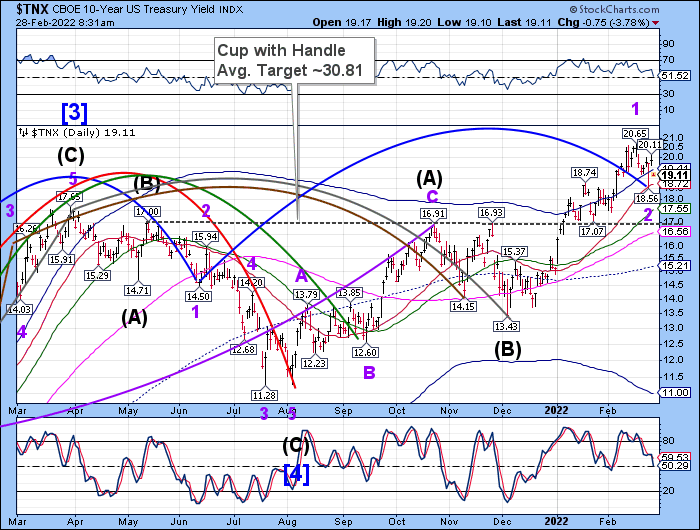
TNX beat a hasty retreat and may challenge the trendline again.  Doing so could extend the Master Cycle bottom, as today is day 266 in the old Master Cycle.  The decline in the 10-year T-note yield may be a result of a knee-jerk habit of switching from stocks to bonds in times of distress.  However, this is only a correction, not a new trend, as it may be in stocks.


USD futures just exceeded the 61.8% retracement target at98.31 I had previously been referring to.  This may be due to the panic flight of assets from Europe to the United States.  Next in line is a target near 100.00 over the next two weeks as the current Master Cycle winds down.


Posted in Published | Comments Off on March 4, 2022

March 3, 2022

12:58 pm

We may have seen the Wave 2 high in stocks at 10:00 am as recent good news could not “pop” the index to new highs.   Today is day 258 in the Master Cycle, so be on the alert to go short.  A reasonable level may be the short-term support at 4360.00, as short gamma begins at 4350.00.

ZeroHedge observes, “Reuters reports that Ukrainian negotiators have said the two sides have reached an understanding on a joint provision allowing humanitarian corridors for evacuating civilians.

The same negotiator reportedly said that the agreement involved a temporary ceasefire during evacuations.

A Russian negotiator was quotes as saying this is “substantial progress,” and Tass reports that a 3rd round of talks will take place in coming days.

The reaction was immediate as we suspect the algos only read the first few words of the headline…

We further suspect the algos are making a little too much of this – especially given Putin’s remarks just minutes before about “de-nazifying the nation.”


9:50 am

GKX is trending higher, but may see an end of its current Master Cycle in the next week.  A probable target may be 570.00, although it could streak to 600.00 under critical circumstances.


7:45 am

Good Morning!

Those of you who read my 4:40 pm post yesterday will notice that the NDX does not have an expected Master Cycle high in the next two days, while the SPX does.  At the same time, the NDX had a Master Cycle low in early January, while the SPX was just coming off its high.  Normally, the two indices go hand-in-hand, but at critical points, they diverge.  This would be considered a half-Cycle high in the NDX.  It’s target may only be Intermediate-term resistance at 14663.83, 2,000 points below the 200-day Moving Average.  At this rate of decline, we may not see a bottom in stocks until early June, which makes this a decline for the record books, since the average bear market lasts only two months.

NDX futures are flat this morning.

ZeroHedge observes, “For what may be the most vivid example of how central planning has turned the market into one giant (and so far successful) experiment in Pavlovian conditioning, look no further than the following chart from Bank of America which shows that during the current 10% correction which started in early January and continues to this date, Bank of America’s ultra high net worth, or “private” clients, have allocated the most dip buying capital on record.

And last week was no different: according to BofA quant Jill Carey Hall, during last week’s market rollercoaster, where despite the break out of the Russia-Ukraine conflict the index ultimately closed +0.8%, the bank’s clients returned to buying US equities ($4.6B) after selling the prior week.”


SPX futures are flat beneath 4400.00 as the market prepares for another options day on Friday.  Friday options turn positive above 4400.00, so it appears that dealers are in a sweet spot at or near Max Pain (for options investors, that is).  While both call and put options are sparse above 4400, gamma turns long at 4500.00.  Short gamma begins at 4350.00.

The Cycles Model calls for a Master Cycle high in the next two days. The target may be near the 200-day Moving Average at 4463.83.

ZeroHedge reports, “US stock index futures were flat on Thursday as investors assessed the impact of a surge in commodity prices on inflation and economic growth while eyeing news that a Ukraine delegation was headed to talks with Russia offering some hope of a ceasefire as the war in Ukraine enters its second week. Contracts on the Nasdaq 100 were down 0.2% by 7:15 a.m. in New York, after the underlying technology-heavy index rallied Wednesday to its highest level in two weeks. S&P 500 futures were flat and Dow futures declined 0.1%.


VIX futures are at the morning low at 30.32.  While VIX appears weak this morning, support lies at the Cycle Top at 29.63.  The Cycles Model suggests that the next Master Cycle high may be during the week of March 14 where the Head & Shoulder target may be met.

In tomorrow’s options, expiring VIX calls have predominance at 30.00 and above, with long gamma at 35.00.  VIX calls become a runaway train above 35.00.


TNX continues its climb higher.  UST shorts are still licking their wounds, but may soon notice the declining share values.  The next Master Cycle (high) ends in the third week of April, so this rally may have legs.  Trending strength comes back to TNX with a vengeance on Monday so bond investors should have made their positions by then.


USD futures are challenging the Cycle Top resistance at 97.41 and appear to have broken out above it this morning.  The current Master Cycle may continue its rally through the week of March 21.  98.30 is the nominal target for this Master Cycle.  However, it could just as easily go to 100.00.

ZeroHedge comments, “Over the weekend, the world gasped in shock when Western powers announced that the nuclear option would be used against Russia in retaliation for its invasion of Ukraine – sanctions against the country’s central bank and targeted expulsions of key banks from SWIFT, a move which has effectively locked Russia out of the western financial system and left its vast oil export industry – a key lifeline for the Putin regime – in limbo. But the real reason for the shock is that this was the first time the global reserve currency was weaponized against a G20 economy, setting a clear precedent for how the west would and could respond to any other nation that followed in Russia’s footsteps (something which China is clearly contemplating vis-a-vis Taiwan, and is carefully studying just how the west responds to Moscow),

As a result, and following this week’s dramatic freeze of the Russian central bank overseas assets, has prompted some to question just why countries build foreign currency reserves at all and, more broadly, whether the unprecedented western response to Russia hasn’t jeopardized the dollar’s reserve status.”


WTI futures consolidated this morning, declining to 106.51 as it regroups for its next probe higher.  The Cycles Model implies a continued uptrend to the week of March 21.  A possible target for this rally appears to be as high as 137.00.  Further probes higher may not have the same strength as the most recent week.

ZeroHedge reports, “(Update 9:05am ET) – Not so fast with that rumor. Moments after oil tumbled as speculation of an imminent Iran deal spread, Reuters and Bloomberg blasted headlines suggesting that the IAEA remains unhappy with Iran, which continues to grow its stock of enriched uranium, and remains in breach of many key limits set by the 2015 nuclear deal.

  • IRAN RAISES STOCK OF HIGHLY-ENRICHED URANIUM BY 83%: IAEA
  • IRAN HAS CONTINUED RESTRICTING IAEA ACCESS TO DATA
  • IRAN CONTINUES TO BREACH MANY KEY LIMITS SET BY 2015 NUCLEAR DEAL, INCLUDING URANIUM ENRICHMENT LEVEL AND ENRICHED URANIUM STOCK -QUARTERLY U.N. ATOMIC WATCHDOG REPORT
  • IRAN’S STOCK OF ENRICHED URANIUM IS ESTIMATED TO HAVE GROWN BY 707.4 KG SINCE LAST QUARTERLY REPORT TO 3197.1 KG -IAEA REPORT SEEN BY REUTERS
  • IRAN’S STOCK OF ENRICHED URANIUM INCLUDES AN ESTIMATED 33.2 KG OF URANIUM IN URANIUM HEXAFLUORIDE (UF6) FORM ENRICHED TO UP TO 60% PURITY, NEAR WEAPONS-GRADE -IAEA REPORT
  • IRAN’S STOCKPILE INCLUDES AN ESTIMATED 182.1 KG OF URANIUM IN UF6 FORM ENRICHED TO UP TO 20% PURITY, PLUS 36.5 KG OF URANIUM ENRICHED TO UP TO 20% IN OTHER FORMS -IAEA REPORT

So don’t hold your breath for an immediate Nuclear deal, especially since Iran is already selling most of its product to China.”


Posted in Published | Comments Off on March 3, 2022

March 2, 2022

4:40 pm

The Cycles Model has been a puzzle to me until today.  It had projected a Master Cycle Pivot on Thursday, March 3.  I had anticipated a low on that day.  However, the VIX and Hi-Lo don’t agree.  Today’s marginal new high suggests a MC high is more likely.  Waves (1)-(2) took 21 days.  The current Waves 1-2  have thus far taken 19 days.  This suggests that tomorrow or Friday may be a Master Cycle high (instead of a low).  The target for that high may be the 200-day Moving Average at 4463.11.

Until today, I just didn’t see this coming.  I can repeat Charlie McElligott’s sentiment, “This is getting exhausting.”

11:36 am

Dealers struggled to move SPX higher for the close of today’s options.  The bounce missed making a new high by 6 basis points.  Anything can happen now.  Traders are getting sick and tired (and squeezed) by all the hijinks.

ZeroHedge explains, “After yesterday’s epic rollercoaster in rates, where we first a dual VaR shock, first in the front-end of the curve as eurodollar exploded higher sending rate hike expectations plunging, and then moved to the long end with coupon bond yields crashing, especially in Germany, where the 10Y bund saw the biggest one day drop in yields in a decade…

… today we are seeing a sharp reversal in much of yesterday’s move – to be expected after Biden’s SOTU address yesterday when he again tasked Powell with easing inflation (even if it means an even sharper economic slowdown, although Biden’s speechwriter was unfamiliar with the trade-offs of monetary policy and so this particular part wasn’t mentioned) with Dec 22 Eurodollars sinking, and leading to one of the sharpest one day drops in the past year, although we are still nowhere near where we were just last week when absolutely everyone on Wall Street was convinced the Fed would hike as much as 7 times this year alone, and who knows how much in 2023.”


11:31 am

TNX ripped higher after making its Master Cycle low yesterday.  Powell’s comments did not raise the confidence level.  The next Wave higher will have legs.

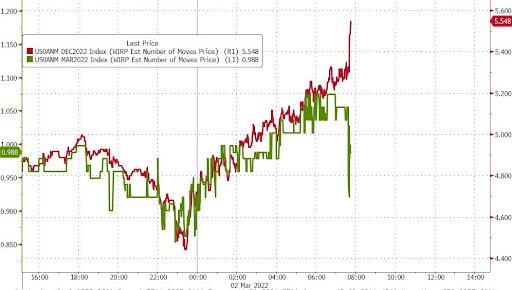
ZeroHedge remarks, “Rest in Peace 50bps March rate hike.

Moments ago, Fed Chair Powell said that he is “inclined to support a 25 basis point rate hike” in March, which immediately killed any market expectation of a 1+ rate hike in two weeks.

However, in the very next sentence, Powell said that if inflation stays hot, he could move more than 25 basis points at upcoming meetings, which in turn pushed the full year rate hike expectations sharply higher, from 5.2 to 5.6.

Of course, this is not the end of this story, and should oil continue to surge – and it will – unleashing inflationary shockwaves and crippling global growth, expect this hawkish consensus to once again unwind… but not yet, because as noted earlier, the VaR shock in the STIR space is now in full-blown reverse mode, with Dec 2022 ED futs collapsing and undoing their entire Tuesday move…”


8:15 am

Good Morning!

SPX futures rose to 4346.30 in an attempt to achieve Max Pain at 4350.00 during today’s options expiration.  However, that level could not be sustained and SPX slipped back lower.  Today we may see a challenge of the Lip and Cycle Bottom at 4182.03 as the panic Cycle evolves.  Wave (1) and Wave 1 each took 12.9 days to complete, so if we use that same algorithm, Wave (3) may not be complete until March 16, where the VIX and Hi-Lo are proposed to have their Master Cycle low.   However, we cannot rule out a panic decline of 4.3 to 6.45 days for Wave 3, leaving the Completion of Primary Wave [1] by mid-March.  Much of this has yet to be sorted out.

ZeroHedge reports, “U.S. futures and European stocks rose on Wednesday after the Kremlin said Russia was ready to resume negotiations with Ukraine. Nasdaq 100 contracts were up 0.7% by 730 a.m. ET reversing earlier declines of as much as 0.8%. S&P 500 futures rose 0.5%, while Dow futures gained 0.7%. Oil soared with Brent trading above $111 as traders realized that Russian oil output will be substantially reduced despite sanction loopholes. The dollar rose and 10Y yields rose.”


VIX futures pulled back to 32.31 early this morning, but have bounced pack to positive territory. VIX has a massive open interest at 25.00 with 15,098 call contracts expiring today.  That position alone has a $12.6 million liability at the end of the day at current prices.

The NYSE Hi-Lo Index closed at -24.00 after ranging as high as 102 at mid-day yesterday.


TNX leaped above the 50-day Moving Average at 17.65 this morning after Jerome Powell’s prepared remarks were released.  This puts TNX on a buy signal (UST on a sell signal).  Having made its Master Cycle low yesterday, the new Master Cycle appears to be active until late April.

ZeroHedge reports, “Fed Chairman Jerome Powell will testify before the House Financial Services Committee on Wednesday, part of the Fed chair’s semiannual testimony to Congress about the state of the economy. Most analysts expect Powell’s interlocutors to focus on his outlook for inflation as expectations for Q1 GDP growth continue to slide, stoking fears of stagflation.

Oil prices in the US have climbed to levels unseen since 2011 in the wake of Russia’s invasion of Ukraine, and global equity markets have been whipsawed as a result. Faced with this, investors have abandoned bets on the likelihood of a 50 basis point hike in March as the Fed struggles to balance geopolitical concerns with its domestic mandates to guarantee stable prices and strong job market.”


USD futures rose to 97.83 this morning, before easing back down to the Cycle Top support at 97.69.  The current Master Cycle may continue its run to the week of March 21 before it pivots.


WTI futures reached an overnight high at 112.47 as the upward trend continues in oil.  The Cycles Model suggests the current Master Cycle may not end until the week of March 21.

ZeroHedge reports, “In what one observer called “the fastest one yet” – the meeting lasted just 13 minutes, beating last month’s record for brevity – OPEC+ 23-nation coalition led by Saudi Arabia ratified an increase of 400,000 barrels a day on Wednesday, continuing the gradual restoration of output halted during the pandemic, according to delegate sources.

This was merely ratifying the plan – as expected – and notably gives no deference to President Biden’s urgings for the cartel to raise production to rescue his approval ratings at home.”


Posted in Published | Comments Off on March 2, 2022

March 1, 2022

12:48 pm

BKX is descending toward the Neckline of its Head & Shoulders formation at 126.25.  As a proxy for liquidity,  BKX shows cash exiting the markets to the point of being critical.


11:42 am

TNX has completed its correction down to the Lip of the Cup with Handle, making a bottom at 17.05.  In doing so, it has bloodied the bond shorts.  Today is day 263 of the Master Cycle, so there is not a lot more to be expected in this correction.

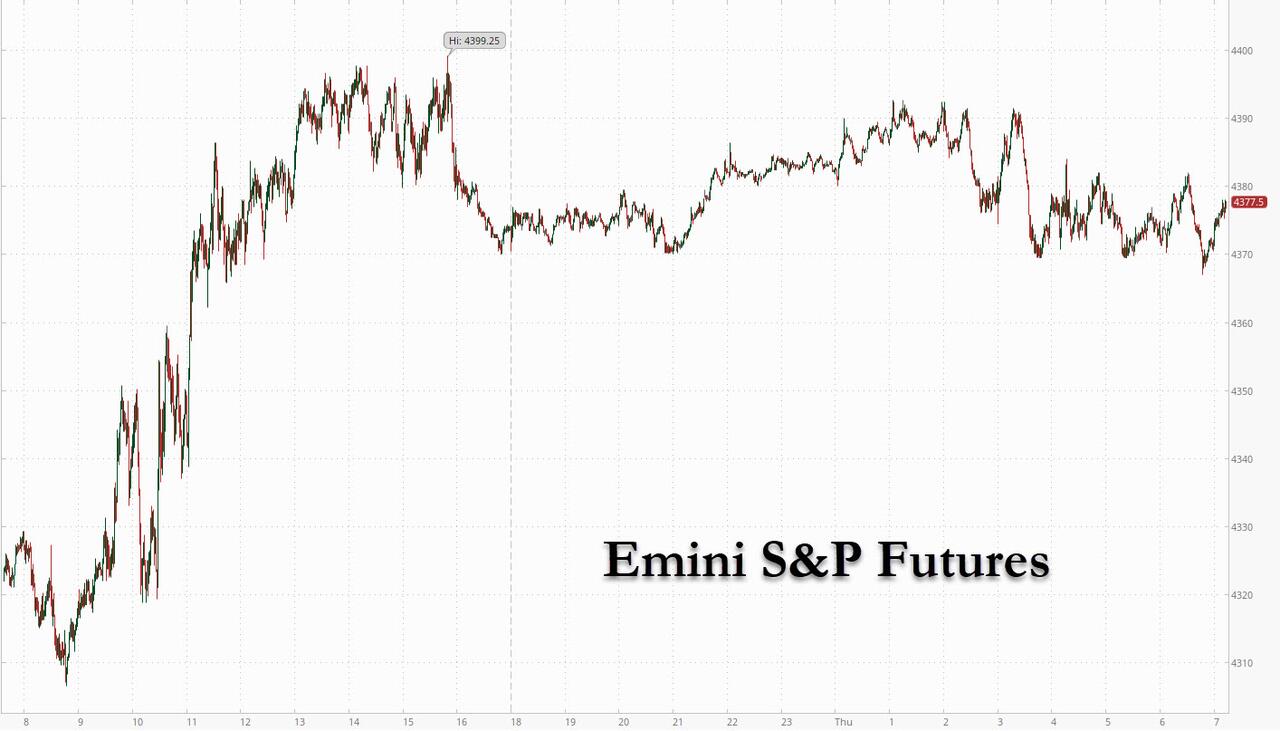
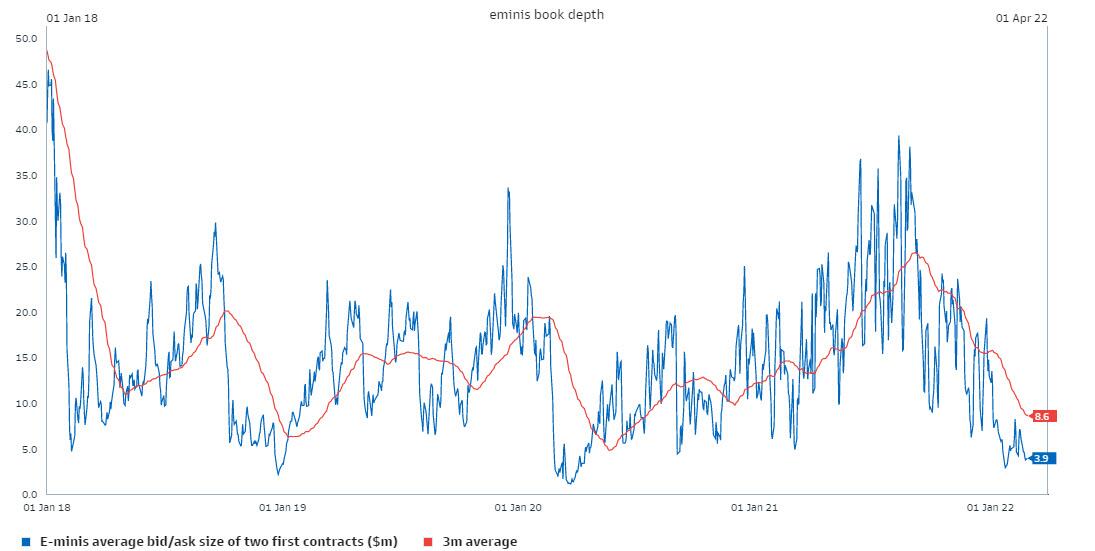
Zerohedge remarks, “With most traders glued to screens and following every tick in the chaotic mess that is the Emini, where liquidity has collapsed to levels not seen since the March 2020 crash…

… the real action is in bonds, where as Nomura’s Charlie McElligott writes in his morning note that we are seeing a “paradigm shift” in rates as a result of the spike in “unknown unknowns” from the Ukrainian war, which has prompted comments such as this one from the ECB suggesting that central bank normalization plans may have just died a gruesome death…

  • *ECB SHOULDN’T EXIT STIMULUS BEFORE ASSESSING WAR IMPACT: REHN

and immediately following:

  • *TRADERS DELAY 25BPS ECB HIKE BETS TO MARCH 2023 FROM JANUARY

… and which means that the market’s massive front-end short positioning – where “six or seven” rate hikes had become the market’s flawed baseline – is being VaR-shocked in full-blown stop-out fashion, leading to the EDZ2 +46 ticks from Friday low to this morning’s highs…


9:10 am

The GSCI Ag Index may present another golden opportunity to investors looking for an alternative to stocks.  It is currently in a correction that has about another week to run before reversing higher.  The weekly chart shows a proposed Head & Shoulders neckline at 474.00 with a proposed target at 696.00.  Currently I have the corrective target at the 50-day Moving Average just beneath that.  Of course, I will adjust the chart as the corrective decline is complete.

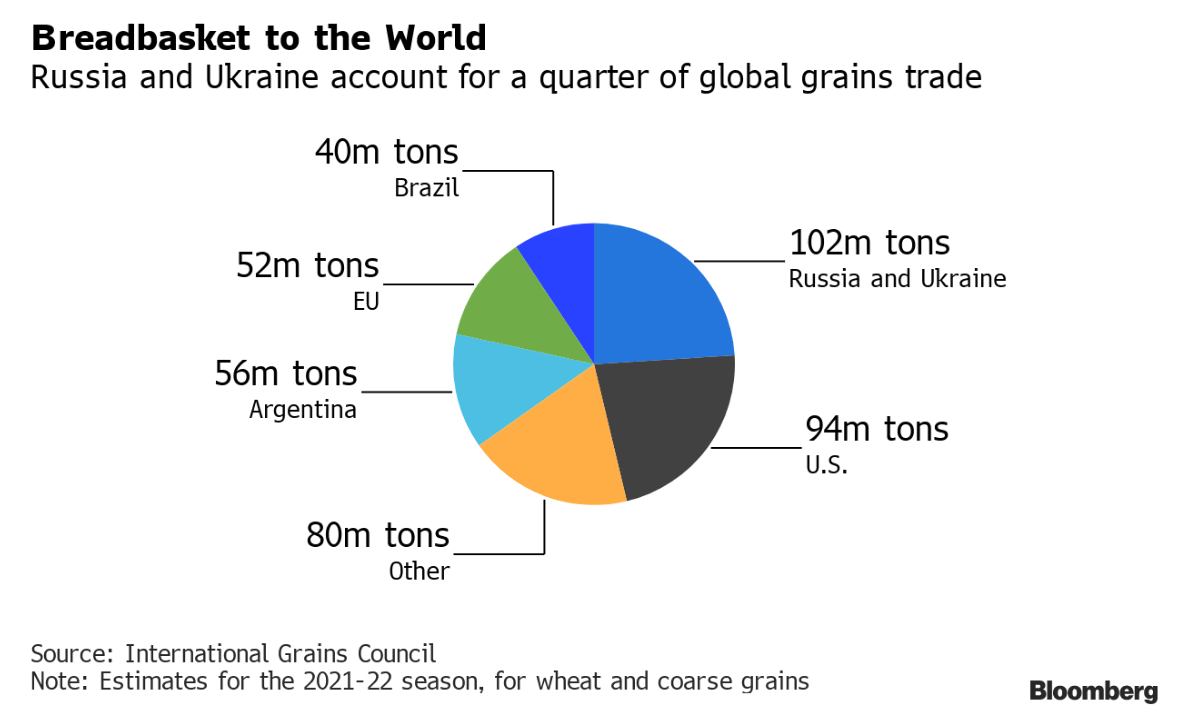
ZeroHedge reports, “Ukraine has earned the nickname “breadbasket of Europe” for its rich dark soil, vast wheat fields, and other farm goods. The Russian invasion has cut off the world from cheap and abundant wheat supplies.

Ukraine and Russia are vital to the global food supply, accounting for more than a quarter of global wheat trade, about a fifth of corn, and 12% of all calories traded globally, according to Bloomberg.

Reuters reports Ukrainian ports will remain closed until the Russian invasion ends and maritime security is restored for commercial ships. ”

ZeroHedge further observes, “China’s top economic planner, the National Development and Reform Commission (NDRC), announced Monday to “immediately” increase pork stockpiles around the country after prices fell last week, according to Bloomberg.

NDRC said the country’s staple meat stockpiles are being replenished as an index monitoring pork prices slipped below a critical threshold. The national average of pork prices against grain prices index registered 4.98 to 1 between Feb. 21 and 25, falling below the 5 to 1 ratio. The ratio signals the need for China to increase pork supplies.

Hog prices are back to levels not seen since before the African swine fever ravaged pig herds across the country, right before the virus pandemic.”


8:10 am

Good Morning!

SPX futures reached a morning low of 4326.90, then mad a weak bounce.  Yesterday’s melt-up at the end of the day reflected the need for dealers to close in neutral territory.  Tomorrow’s Max Pain zone is at 4340.00 with expiring options being positive above 4350.00 and negative beneath 4300.00.  Continued pressure from the Ukrainian conflict and with Powell on the docket  tomorrow, things may get rather dicey.  The Cycles Model is poised for a major low on Friday, but with follow-through over the next two weeks.

ZeroHedge reports, “In a mirror image of yesterday’s overnight bounce, S&P futures and European markets have slumped to session lows as a risk off mood prevailed as US traders got to their desks having hit overnight highs of 4,399 just before the European open, as mood soured after the conflict in Ukraine intensified amid mounting penalties against Russia, and as participants look to a heavy data-docket ahead and Fed speak including Powell later in the week.

Any residual optimism was shattered after Ukrainian President Zelensky said that negotiations with the Russian side have not achieved required results while Russian Defense Minister Shoygu says Russia will continue operations in Ukraine until it achieves its goals. As a result, Nasdaq 100 contracts were down 0.9% as of 7 a.m. in New York after the cash index closed yesterday’s session with its second straight monthly decline, a trend not seen since October 2020. S&P 500 futures declined 0.7% or 30 points to 4,337  while Dow futures fell 0.7% or 230 points, reversing much of yesterday’s last hour ramp. Stocks trading in Moscow remained halted for a second day, and the VanEck Russia ETF plunged another 12%. Treasury yields fell for a second day to the lowest since January, and the dollar was steady. Brent crude jumped more than 5% as traders balanced the possible release of emergency stockpiles against fears of disruption to Russian energy exports.”


VIX futures made an overnight high of 32.42, still within yesterday’s trading range.  It is using the Cycle Top support as its base, a sign that Wave [iii] of 3 of (C) of [3] may be underway.  The reason I bring this up is that is a lethal combination for stocks.  Sadly, no one is paying attention that the VIX may go much higher.


TNX fell to 17.31 this morning as storm cloud gather.  Last week I had mentioned that the neckline would be a possible target for Wave 2.  Today is day 263 of the current Master Cycle and this may be an appropriate end of Cycle.  It is likely to be on a buy signal at the end of the day.


USD futures rose to 97.20 this morning, still within yesterday’s trading range.  There are three more weeks left in this Master Cycle, as USD ventures toward the 61.8% retracement at 98.30.  From there, it may become evident that our current powers-that-be have destroyed the USD as the world’s reserve currency.

ZeroHedge observes, “The war being waged by Russia in Ukraine shows no signs of coming to any type of peaceful end.

Meanwhile, it appears to me that a separate war on the U.S. dollar could be “officially” waged at any moment, by Russia and China collectively, as the situation in Ukraine grows more dire, as Russia’s options wane and its ties with China grow closer.

While the hope is still to avoid a World War III type scenario, escalating sanctions from the West are forcing an increasingly unhinged Vladimir Putin to consider his options for pushback.

For example, on Sunday, Putin put nuclear deterrence forces on high alert as a response to increasing pressure from NATO, in a move that the U.S. ambassador to the United Nations said “escalates the conflict unacceptably.”

Posted in Published | 2 Comments

February 28, 2022

2:40 pm

BKX is on a similar flight path to the SPX.  There are two possible near-term Master Cycle lows.  The first occurs this week.  The second occurs the first week of April.  Keep that in mind as we move forward.

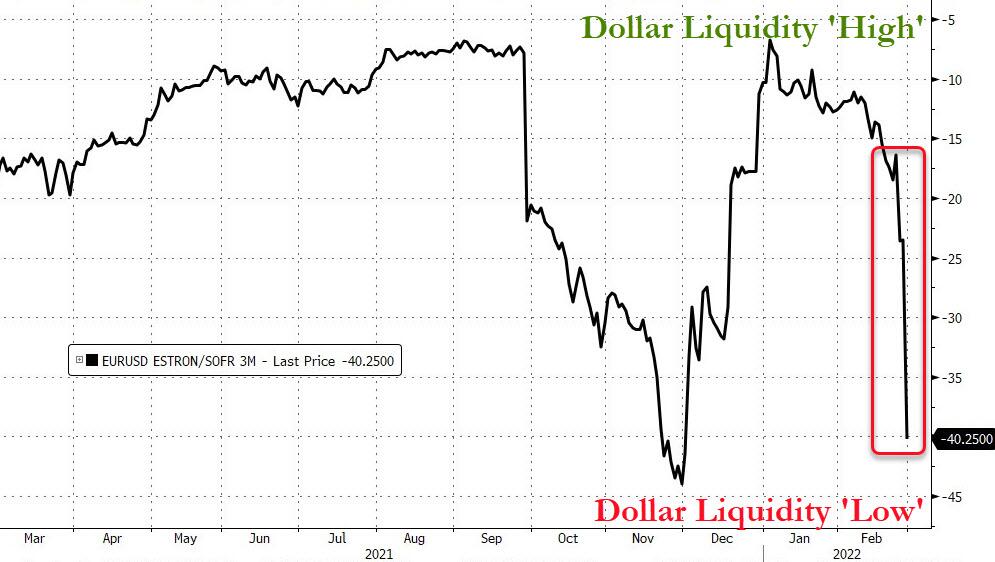
ZeroHedge observes, “Following Zoltan Pozsar’s blueprint for how the US/UK/EU sanctions unveiled over the weekend could lead to problems in the “plumbing” of the global financial ecosystem, we have seen several cracks appear already.

Dollar liquidity is drying up – and thus getting more costly – especially against the Euro…

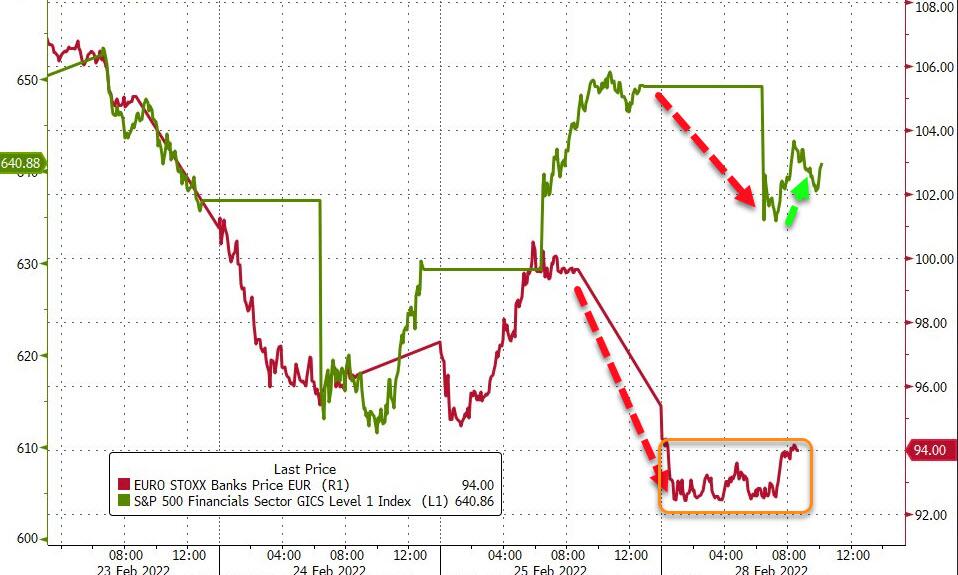
And while both US and European bank stocks were clubbed like a baby seal today, we note that US bounced back modestly while Europe’s financials couldn’t managed much (despite the overall indices rebounding from deep losses)…

So, the question is – which banks are most exposed to the ongoing (and escalating) threat of sanctions on Russia?

Specifically, among other more arcane details, the sanctions relate to:

(1) freeze of assets,

(2) capabilities of certain largest Russian banks to process transactions and

(3) proposed ban of certain payment avenues (SWIFT).


2:10 pm

There are multiple reasons for giving up my previous Wave count.  The primary on is that Wave 1 (481 pts.) is smaller than Wave (1) at 596 points.  The (1)-(2), 1-2 count means that the largest part of the decline is yet to come.  And the Cycles Model says it will be this week.  The minimum size may be the combined decline of the first two Waves, or 704 points.  That would be a close match to the Head & Shoulders target.  However, Wave threes are often multiples of the Waves preceding them.  A 2X multiple would put the target at 2980.00.  The Cup with Handle Target would be a 2.5X multiple.


7:45 am

NDX futures threatened the Lip of the Cup with Handle by declining to 13698.70 before a bounce.  That’s nearly a 3.5% decline at the open yesterday.  The die is cast, despite the 73% retracement.  The Cycles Model calls for 4 days of decline.


SPX futures dropped to 4259.10 at yesterday’s open, then bounced to 4345 this morning, a 68% retracement.  However, it has fallen away from the morning high and appears to be resuming its decline.  In the options market, we are at Deja Vu all over again.  Today’s expiring options are bearish beneath 4530.00, with short gamma beginning at 4300.00.  The options market is the “tail that wags the dog” as dealers exercise pain management on a daily basis.  But today may spin out of control.  There is another observation, listed below.

Yesterday, ZeroHedge observed, “Most people don’t realize that the Crash of 1929 and the Crash of 1987 both occurred exactly 55 calendar days after the stock market had topped.

All prices in this article are closing prices on the day being referenced.

1929: the peak in the Dow was reached on September 3rd, when it closed at 381.17.

55 calendar days after September 3rd was (Monday) October 28th. That was the exact date of the Crash of 1929, with the Dow down 40.58 points, or 13.5%.

1987: the Dow topped out at 2722.42 on August 25th.

55 calendar days later was (Monday) October 19th when the Dow collapsed 507.99 points, or 22.6% in one day!

This year, the Dow topped out on January 4th, and…

55 days later is Monday (!) February 28th.

ZeroHedge reports, “Global stocks and US futures tumbled on Monday, although they were well off their worst levels as a fresh round of ceasefire talks kicked off on Monday morning offering a glimmer of hope that hostilities will end; sovereign bonds rallied and commodities surged amid heightened uncertainty after a new wave of sanctions against Russia for the invasion of Ukraine.

March contracts on the S&P 500 Index declined as much as 2.9% before trimming losses to 1%, or down 43 points as of 745 a.m. in New York. Futures on the Nasdaq 100 and the Dow were each down 1.4%. European stocks also recovered from an earlier as banks with exposure to Russia led declines, while utilities and defense stocks gained. Oil, natural gas, wheat and palladium jumped, as Brent crude soared to about $103 a barrel on fears of commodity-supply disruptions. Rallies in the dollar, gold and Treasuries underlined the demand for havens.”


VIX futures rose to 33.52 after yesterday’s open, but settled back as the morning progressed.  The neckline of the Head & Shoulders formation is at 39.00.  A crossing today is likely and sets the stage for reaching the target by the end of the week.

ZeroHedge observes, “VIXplosion is back

VIX is +18%, trading at 32.5 as of writing, highest levels since January 2021. What most people tend to forget is that buying protection in panic is usually an expensive strategy. Unless this crashes imminently (and 1.5% down on Spoos is not a crash) VIX is trading at very rich levels. Volatility is not a trending asset over time, and we have come up a lot lately…


TNX has declined beneath the Cycle Top support and may be headed for a deeper low.  Last Thursday’s low was on day 258.  However, today’s actions may extend the Master Cycle low later this week.   The Ukrainian crisis may push TNX down to the 50-day Moving Average near  17.55.


Despite the 8% rally in BKX last week, it also is headed for a crash by the end of the week.  It may make a deeper low in early April, according to the Cycles Model.

ZeroHedge reports, “In a remarkable show of force and unity, western powers cast aside all their previous concerns about Russian energy export dominance, and uniliaterally announced the nuclear option of imposing sanctions on the Russian central bank coupled with targeted exclusions from SWIFT of key Russian banks.

  • *EU APPROVES BANNING ALL TRANSACTIONS WITH RUSSIAN CENTRAL BANK

The move has sparked a bank run in Russia, as locals scramble to pull out whatever hard currency they can get their hands on before it runs out, and is certain to trigger chaotic moves in FX and commodities when markets reopen on Monday. Already some Russian banks are offering to exchange rubles for dollars at a rate of 171 rubles per dollar on Sunday, compared to the official closing price of 83 on Friday before the European/US announcement about targeting the Russian central bank. In other words we are looking at a 50%+ devaluation of the Ruble. Additionally, widespread announcements of divestments in Russian equities by the likes of BP pls and the Norwegian sovereign wealth fund mean that the Russian market will be a bloodbath on Monday.”


Posted in Published | 2 Comments

February 25, 2022

3:25 pm

GKX may be having an early Master Cycle high on day 245 of its Master Cycle.  However, a correction in this environment may extend the Cycle to a more normal time.  The correction may last until the week of March 21, so there is time for an extension.  These are interesting times, indeed.

ZeroHedge reports, “Star Tribune reports a vessel chartered by Cargill Inc., a Minnesota-based agribusiness giant, was hit in a missile attack after leaving a deep-sea port on the outskirts of Odessa on Thursday.

“Right now, our priority is the safety of our people in the region. This is a rapidly evolving situation with a great deal of uncertainty,” said April Nelson, a Cargill spokeswoman, in an e-mail. “We are currently gathering information and assessing potential impacts to Cargill and our customers.”

Cargill said that the crew was safe, and the vessel was rerouted to Romania to undergo a damage report.

Cargill has a majority stake at a port in the Odessa port, exporting grains and oils worldwide. The company didn’t name the vessel. ”


3:00 pm

Gold may have had its Master Cycle high yesterday on day 268 of the Cycle.  Today it is testing Cycle Top support at 1882.27.  Once beneath it produces a sell signal.  The Cycles Model suggests that gold may go into decline for the next two months.

MarketWatch comments, “Gold futures fell on Friday, ending the week with a loss for the first time in four weeks. “What we’ve seen this year is a bid for gold put in early on,” especially through the month of February as the threat of invasion ramped up, said Adam Koos, president at Libertas Wealth Management Group. Now that the Russian invasion of Ukraine has taken place, “we have a ‘buy the news, sell the invasion’ theme playing out in the metals market.” April gold GCJ22, -1.70% fell $38.70, or 2%, to settle at $1,887.60 an ounce. Prices based on the most-active contract lost 0.6% for the week, according to FactSet data.”


11:45 am

Earlier this week I had warned that Wave [iv] may go to 4300.00.  I had underestimated the strength of resolve by the dealers to avoid pain at options expiration.  Wave [iv] may be fully extended and may reverse at any time, now that Wave (v) of [iv] equals Wave (i) of [iv] at 4374.00.  That gives Wave [v] at least 4.3 days of decline to complete C of (3).  Enough for a surprising and massive crash.  This move eliminates the Head & Shoulders formation, since they generally do not allow a re-emergence above the neckline.  Cup with Handle formations often have “soft” trendlines.


7:52 am

Good Morning!

SPX futures declined to 4233.00 in the early morning, but then rose to 4300.00, the lasts stronghold for the puts (5346 of them) expiring at the close.  Gamma turns positive at 4325.00.  This is evidence of dealer sponsored short-covering yesterday, to avoid a knock-out at the open when Index options expire.  As for the ETF options expiration,   SPY 430.00 puts and calls both have 14,500 contracts expiring  at the close, while 435.00 puts and calls both have over 19,000 contracts expiring at the end of day.  Long gamma appears above 435.00 and short gamma takes over at 425.00.  SPY is likely to walk a tightrope at 430.00 to avoid a melt-up or melt-down.
The Hi-Lo Index closed at -770.00, leaving the SPX as weak as it was on January 24.  This time, however, the Cycles Model still has 5 market days to go to the Master Cycle low.

ZeroHedge reports, “After yesterday’s furious gamma-squeeze rally, U.S. stock futures were slightly lower on the day, although near the overnight session highs as the ongoing Ukraine conflict and impact of Western sanctions continue to drive risk; sentiment was boosted after the Kremlin said that Ukraine’s neutrality offer is a move “toward positive” and following reports that China’s president Xi held a phone call with Putin who said Russia is willing to conduct high-level negotiations with Ukraine. S&P futures were down 10 points to 0.25% at 7:30am, after paring earlier declines of more than 1%, with Nasdaq futures down -0.15% and Dow futures down 0.4%. Europe’s Stoxx Europe 600 was in the green, and oil was steady after Bloomberg reported that oil importers in China are briefly pausing new seaborne purchases as they assess the potential implications of handling the shipments following the Ukraine invasion. Gold was steady, while Brent crude reached $100 a barrel and Treasuries rose.


VIX futures made a morning low at 29.26 thus far, just beneath yesterday’s trading range.  While it may still subside to the Cycle Top support at 27.77, the likelihood is that it may resume its uptrend.  The reason I say that is 28.00 is the beginning of long gamma in the VIX.  A VIX above 28.00 could be the tail wagging the dog during options expiration.

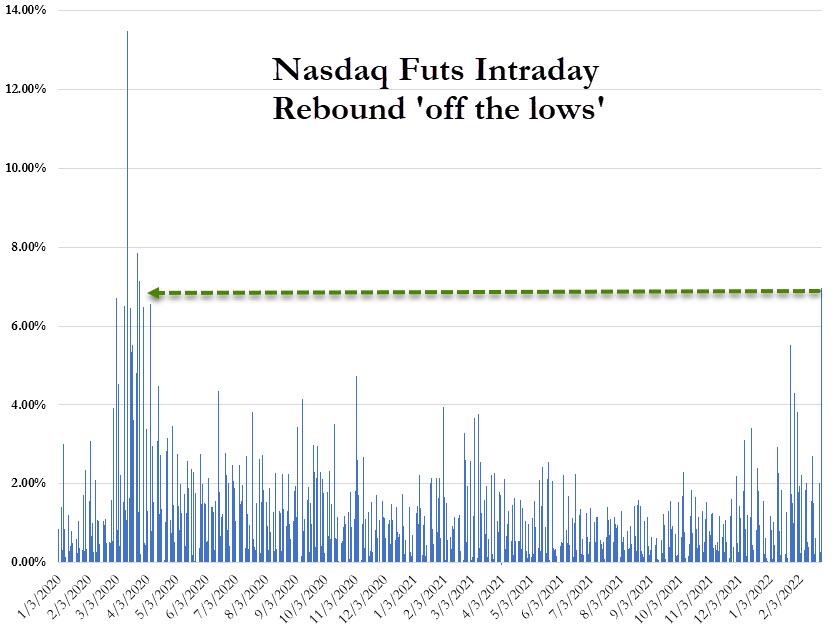
ZeroHedge comments, “As we noted earlier, today’s stunning rebound in stocks (most notably Nasdaq, which swung from down 4% overnight to close up 3%)…

…was the biggest intraday rebound since The Fed ‘saved the world’ in March 2020.

The reversal began at the US cash market open, stalled a little, then exploded higher after President Biden’s sanctions speech was not as harsh as feared.

The question is – WTF Happened!!!”


TNX has risen to 20.16 this morning, not wasting any time re-establishing its upward trend.  The Cycles Model suggests a double dose of strength beginning this weekend, with the new Master Cycle extending for up to two months.  Many analysts see yields going down with the SPX.  However, the Cycles have changed and are no longer in sync with stocks.

ZeroHedge reports, “After two stellar coupon auctions this week, when both the 2Y and 5Y saw record low dealer awards, moments ago the week’s auction cycle concluded with the sale of $50 billion in 7 Year paper in another stellar auction.

The high yield of today’s just concluded auction stopped at 1.905%, stopping through the When Issued 1.915% by 1 basis point. And while this was sharply higher compared to last month’s 1.769%, and the highest yield for the tenor since July 2019, it priced in a day when there has been a lot of market chaos, which helped boost demand for the safe haven.

The bid to cover of 2.364 was also solid, the highest since November, and well above the six-auction average of 2.304%.


Dollar Index futures pulled back to a morning low of 96.77 after a breakout of the Cycle Top at 97.65.  The Cycles Model suggests that USD may continue it uptrend until the week of March 21.  The 61.8% Fib retracement of the 2020 decline lies at 98.30, which provides a target for this rally.


Posted in Published | 1 Comment

February 24, 2022

3:25 pm

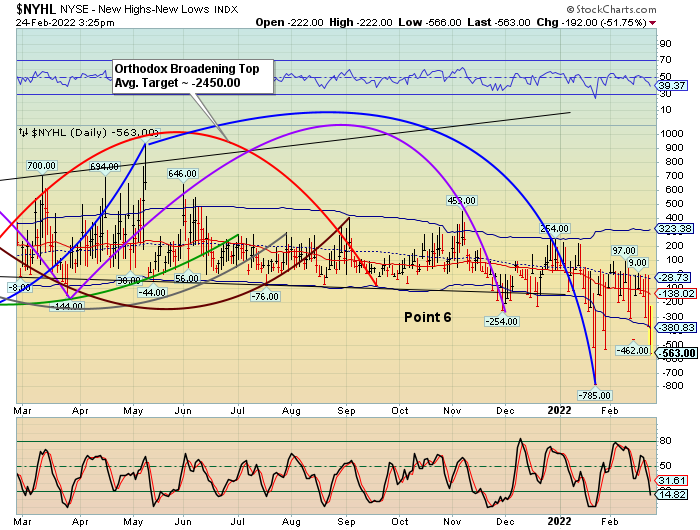
You just have to see this to recognize the craziness of this market.  The SPX gained nearly 3.5% from its morning low in a day that the Hi-Lo was -563.00???  This is short covering on steroids!  People are getting hurt.


3:17 pm

Wave C of (3) is turning into a monster by subdividing, which makes it extend even more.  Next up is our panic down day in the form of Wave (iii) of [iii] of C  of (3).  Wave threes cannot be the smallest Waves.  In this case, it may be a multiple of the decline from 4489.55.  A 2X multiple may take Wave (iii) down as much as 750 points, or 3500.00!  Remember, tomorrow is yet another options expiration, which will compound the gamma issue.  There may not be a rebound such as this the next time.


1:20 pm

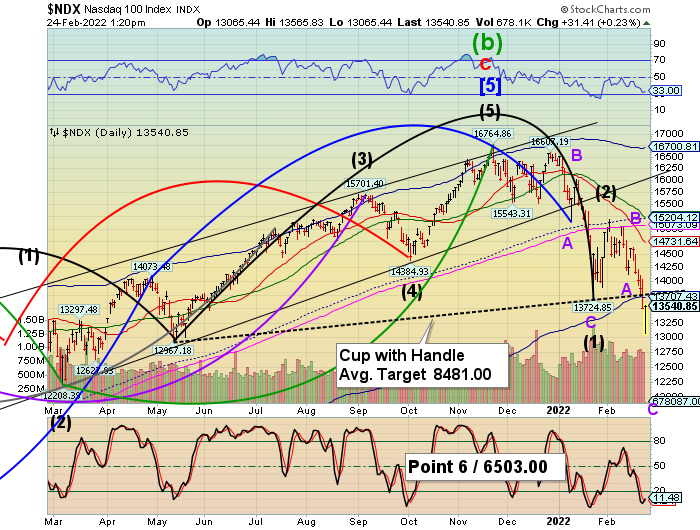
It may seem unbelievable that the NDX is back in positive territory.  However, the Cycles Model calls for a retest of the Cycle Bottom at 13707.00 before resuming the decline.  That may delay the Master Cycle bottom until the close of Wednesday, March 3.  This retest is a “mechanical reaction” to the crossing of the trendline.  We may see the “reaction” end in the next hour or so.

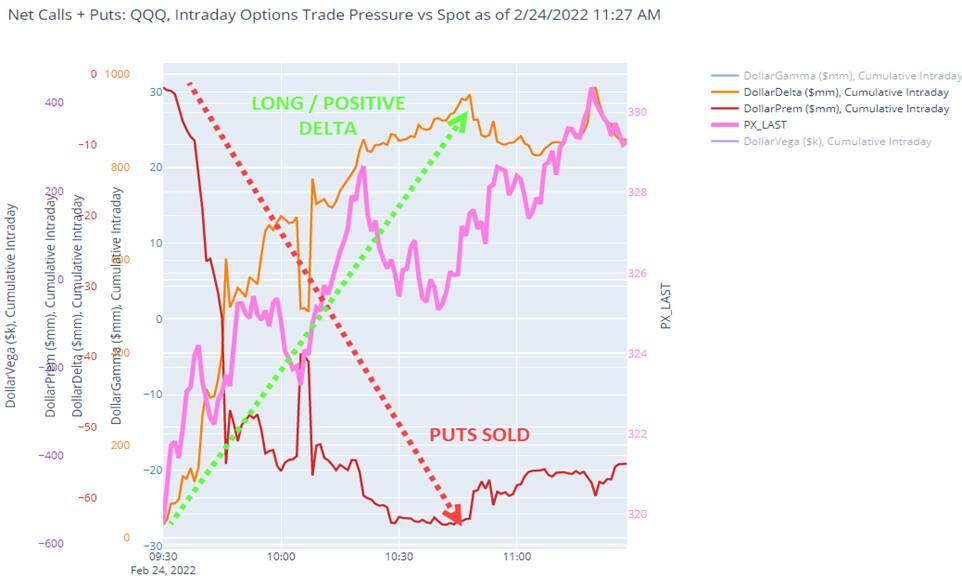
ZeroHedge remarks, “Update (1300ET): In case you were wondering just who (or what) was BTFDing today, Nomura’s Charlie McElligott can clear things up for those chasing the momo here.

Equities’ move off the lows is largely a function of “Long / Positive Delta” expressions in the options space (as opposed to “wholesale” uptick in risk-appetite – although there is def some offense being played).

Primarly, index / etf downside hedge monetization (see below) and VIX upside CS monetization , in addition to some “offense” with upside prem spent, largely via Call Spreads.

Collecting premium from selling QQQ Puts equals positive deltas…

So, it’s hedge unwinds, not optimism that is driving this and as McElligott warns, this may leave us open to pullback thereafter unless flows sustain.”


1:03 pm

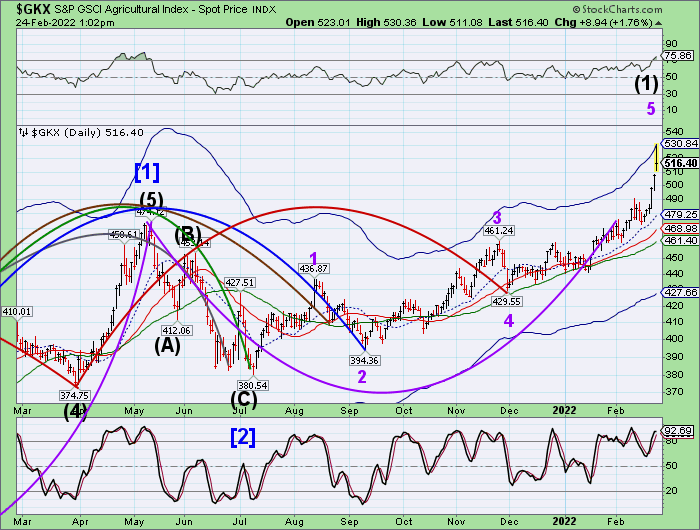
The GSCI Ag Index is in a panic rally that may not end until the second week of March.  This is a true supply-and-demand situation.  The U.S. has lost two major fertilizer plants in the past year.  There is a terrific drought in the Southwest.  Fuel costs for agriculture and transportation are going up and Belarus (a major source of raw agricultural materials) has stopped its export of potassic fertilizers.  This is the perfect storm for food prices.

In addition, the war may raise radioactive dust across Europe.

ZeroHedge remarks, “Edible oil prices soared this week, prompting fears that record-high food prices could be imminent. On Wednesday, soybean oil futures in Chicago hit their highest levels since 2008, and palm oil, the commodity used in thousands of food products, jumped to new highs.

Soybean prices increased 1.4% to 71 cents per pound, the highest level since 2008. US canola futures are also on the verge of an all-time high, and palm oil in Malaysia hit a new record high of $1,434 per ton.”


12:50 pm

BKX has broken its trading channel trendline at 129.00 today.  It also may be  in a panic mode through late next week.  It has also broken the lower trendline of a two-year Ending Diagonal, which may be doomed to a complete retracement to 55.40.


12:40 pm

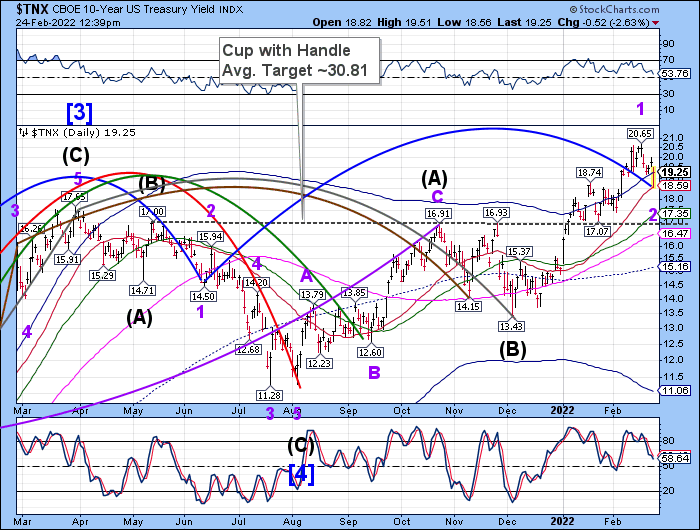
TNX bottomed at 18.56, on the Intermediate-term support to make a likely Master Cycle low (day 258).  Yields are set to go much higher, as the Cup with Handle formation indicates.  The next Master Cycle Pivot is two months away, a probable high, as indicated by the Cup with Handle formation.

Zerohedge comments, “While it’s not the first time that the NY Fed has experienced a major “technical glitch” preventing it from executing its daily open market purchase of Treasuries and MBS securities, the Fed sure could have picked a better day for a printer jam.

Moments ago, the NY Fed announced that “due to technical difficulties, today’s Treasury outright purchase operation – scheduled for 10:10 AM – will be rescheduled. It is now scheduled to take place Friday, February 25, 2022 at 10:10 AM. Additionally, today’s MBS outright purchase operations – scheduled for 10:00 AM and 11:30 AM – will also be rescheduled to Friday, February 25th, 2022 and Monday, February 28th, 2022 respectively. Information on Treasury securities operations and MBS purchase operations can be found on the New York Fed’s webpage. This does not impact any other operations scheduled for today.”

1:30 pm

ZeroHedge reports, “After two stellar coupon auctions this week, when both the 2Y and 5Y saw record low dealer awards, moments ago the week’s auction cycle concluded with the sale of $50 billion in 7 Year paper in another stellar auction.

The high yield of today’s just concluded auction stopped at 1.905%, stopping through the When Issued 1.915% by 1 basis point. And while this was sharply higher compared to last month’s 1.769%, and the highest yield for the tenor since July 2019, it priced in a day when there has been a lot of market chaos, which helped boost demand for the safe haven.

The bid to cover of 2.364 was also solid, the highest since November, and well above the six-auction average of 2.304%.”


12:20 pm

SPX did not Limit Down at the open.  Instead, it bounced at 4100.00.  Then it retested the Lip/Neckline at 4202.00.  It has been my experience that, once the neckline/lip have been retested, the decline may take another 4.3 days in a panic.  That would put the bottom of Wave (3) on Wednesday, day 257 of the Master Cycle, near 2:00 pm, to be exact.  It wouldn’t hurt to be early, if Wave (3) should extend beyond that time.  The majority of the decline will have been done.  Just so you know, there may be an extension of the decline, Wave (5) of [1], lasting until the week of March 14 after a very sharp rally that may go as high as 4000.00 in the interim.


7:00 am

Good Morning!  I am getting an early start, since I am taking my wife to the dentist this morning.

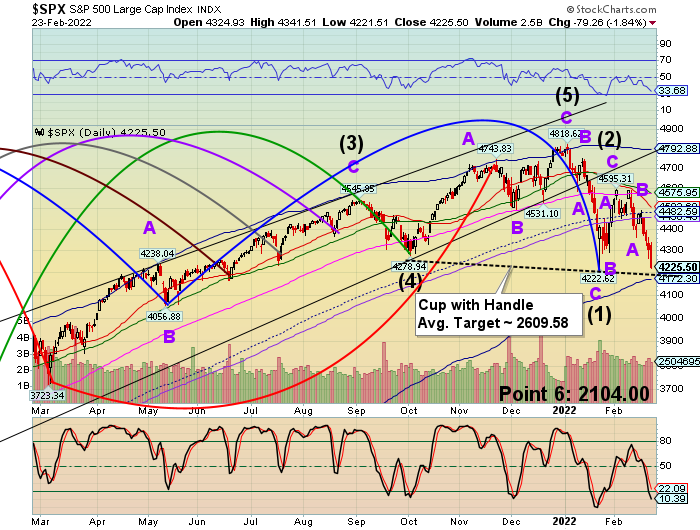
SPX futures crashed down to 4100.00 before a bounce, which is currently underway.  This is day two of a three-day decline in Wave [iii] of C of (3), a triple panic in the Waves, and there may be a much further to decline tomorrow.  Should the Head & Shoulders stop at 3626.00, then the Head & Shoulders formation is in play.  However, the Cup with Handle suggests an average target of 2609.58 by tomorrow’s end.  Worse and much worse appear to be the only two choices the market can make at this time.  Tomorrow’s options expiration is likely to be a disaster, since short gamma is like a runaway train.  The Fed will have to wait until the weekend to just put on the brakes.  Investors buy puts as “portfolio insurance.”  However, there is no such thing.  Risk is simply transferred to the put sellers, who must go even more short.

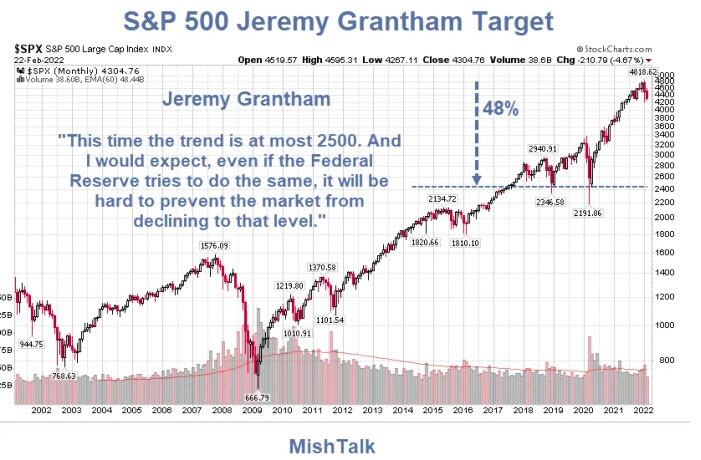
MikeShedlock observes, “Let’s discuss value investor Jeremy Grantham’s thesis on “super bubbles” and his target for the S&P 500.

S&P 500 chart courtesy of StockCharts.Com, annotations by Mish with thanks to Jeremy Grantham.

Fourth Super Bubble    

For almost a half-century, value-investing icon Jeremy Grantham has been calling market bubbles. Now, he says U.S. stocks are in a “super bubble,” only the fourth in history, and poised to collapse.”


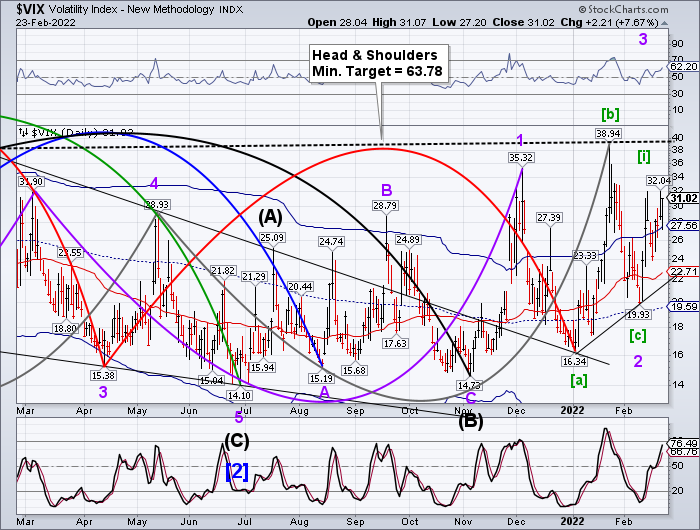
VIX futures rocketed to the neckline of the Head & Shoulders at 38.94 before easing back in the overnight session.  The next rally may push through the resistance, turning it into support for the next week.  It may fall short of the March 2020 high of 85.47 by tomorrow’s end, but next week may see the VIX push over 100.00.

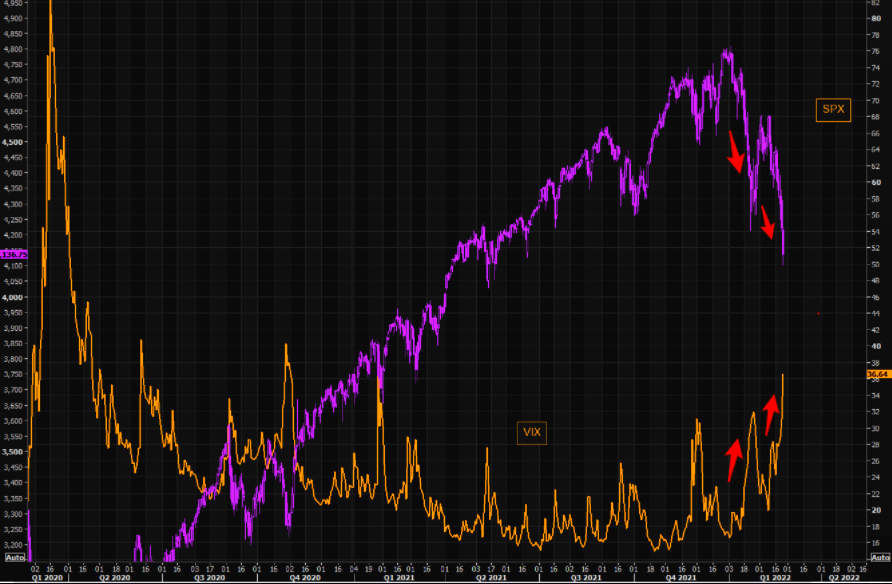
ZeroHedge explains, “VIX panic in a pic

Let’s take a closer look at the VIX panic du jour. VIX is up around 20% in early prints. We have seen sharper moves to the upside in VIX over the years, but this time VIX is starting from very elevated levels already. The Russian fear has been priced in by VIX in a “slow motion” fashion over the past weeks, but don’t forget that VIX is pricing more than the Russian situation. VIX is also pricing Fed and the general macro narrative. Volatility as an asset is mean reverting for obvious reasons. It is therefore noteworthy to see the trend in VIX since last autumn. VIX has basically trended higher from 15 ish to now trading around 36/37. The sell off this time around is approx the same as the early January sell off, but the VIX is trading at much higher levels compared to what we saw in late January and is now way higher than where it closed in late January. The problem with people chasing late hedges up here is that protection is very expensive.”


NDX futures plummeted to 13032.70 this morning and bounced, but the rebound was anemic.  The only alternative to the Cup with Handle formation is a Head & Shoulders formation with a target of 10685.00.  The first “limit down” stop in the NDX is at 12563.00.  We may see that at the open, with a market closure for the first 30 minutes.  Today may be a “panic down day” with losses of 10% or more.

ZeroHedge reports, “U.S. stock index futures crashed along with global markets on Thursday as Russia’s assault on Ukraine sent investors fleeing risky assets, while the tech-heavy Nasdaq was set to open in a bear market. Contracts on the Nasdaq 100 were down 2.9% by 7 a.m. in New York, having dropped as much as 3.6% earlier and signaling that the underlying gauge was poised to fall 20% from its November record high for the first time since the pandemic; the S&P 500 was down 2.23% or 98 points to, 4,214, while Dow futures lost 2.3%.  The flight to safety saw the 10-year Treasury yield tumble 14 basis points to under 1.9%. Gold hit the highest since September 2020, while the dollar also spiked higher.

The Nasdaq was set to open in a bear market, with NQ futures down more than 20% from its all time highs just two months ago…

… while the VIX spiked higher, and was last just around 37, up almost 10 points on the day.”


TNX futures declined to 18.46, just shy of the named target of 18.43, where Wave [c] equals Wave [a] of the Wave 2 correction.  Wave equality in a correction is standard fare and today is day 258 of the Master Cycle.  Whatever happen during the rest of the day is yet unknown, but the Cycles Model suggests that TNX may start a powerful rally by the weekend.  Head & Shoulders and Cup with Handle formations usually point to a Wave 3 target.

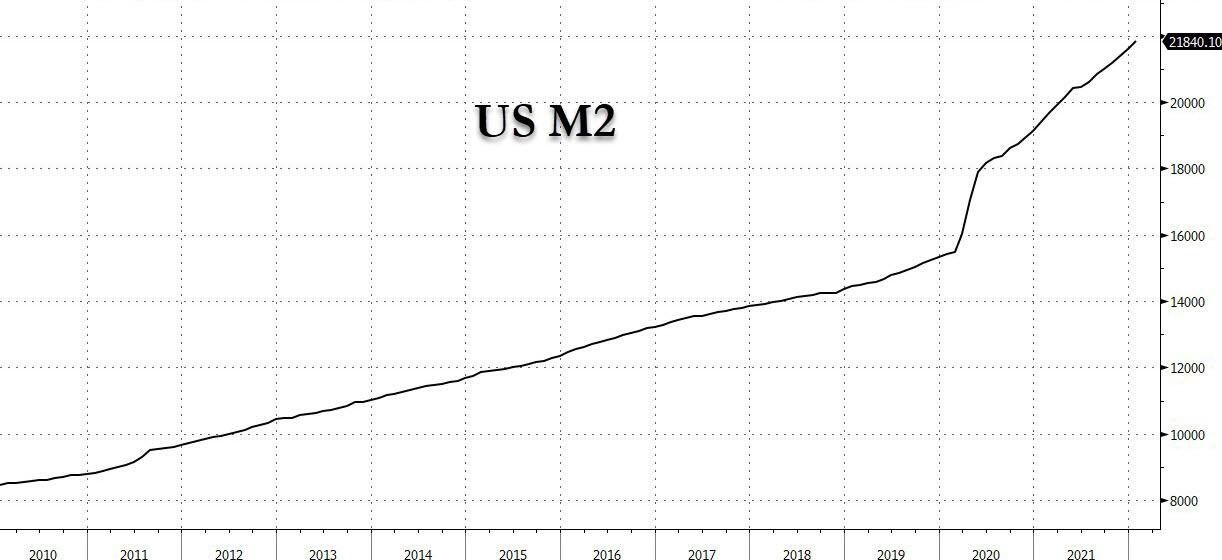
ZeroHedge remarks, “The Fed has a problem. It’s in the business of creating money, but it formulates monetary policy without regard to money itself. So in times when its policy decisions produced a record surge in broad money, policymakers are not attentive or alerted to the negative (inflation) consequences.

From February 2020 to the end of 2021, broad money increased by $6.5 trillion or over 40%. That increase over less than two years is roughly equivalent to the rise over the previous ten years. Yet, policymakers who have long argued that “inflation is always and everywhere a monetary phenomenon” called the surge in inflation transitory, owing to supply bottlenecks. Had policymakers still recognized money as a potential source of inflation, it would not be in the pickle that they find themselves today.”


Posted in Published | 1 Comment

February 23, 2022

1:15 pm

NDX has declined through the double support between 13720.00 and 13750.00.  Now it gets serious, due to the short gamma accumulation.  The Cycles Model suggests two more impulses down with two or more “limit down” days.  Keep your hats on.  It may be a wild ride.

ZeroHedge informs, “Nomura’s Charlie McElligott notes that equities ‘short gamma, extreme short delta’ just points to the regime shift with Fed in “Financial Conditions Tightening” mode…

…where strength is sold into / short-dated Puts are bought to press into selloffs then closed same day; but institutional traders are also ‘day trading’ rallies with call buying and closing – perpetuating intraday swings and new world order of range-trading.”


8:15 am

Good Morning!

SPX futures rose to 4350.40, just 2 points shy of the 38.2% Fib retracement of the decline from 4489.55.    Should the decline follow the existing hourly pattern, we may see a Master Cycle low on March 3 (day 258).   Today’s options expiration shows calls dominating above 4375.00 with long gamma at 4400.00 while puts dominate at 4350.00 and below.  Short gamma begins at 4310.00.  The bounce cannot last in this environment.

ZeroHedge reports, “US equity futures – which on Tuesday tumbled into a technical correction, down 10% from January’s all time highs – rebounded led by tech companies as investor fears over the standoff in Ukraine eased following the limited initial Western sanctions against Russia. As of 7:15am, eminis pared some gains but were still up 0.7% or 28 points on the day; Nasdaq futures were up 0.9% and Dow futures were up 0.54%. The VIX remained elevated, last seen around 28 after trading above 30 yesterday. Treasuries extended declines after the yield curve flattened in the Wall Street session, with the 10Y yield rising to 1.97% after tumbling as low as 1.85% on Tuesday. Crude oil fluctuated, while gold dipped as haven demand eased. The dollar slipped and cryptos reversed some of their recent losses.”


VIX futures bottomed at 27.20, challenging the Cycle Top support, then bounced back above 28.00 this morning.  VIX is on the brink of a breakout with the neckline of the Head & shoulders next to fall.  The Cycles Model suggests that the VIX may continue to rise in strength this week and through the week of March 14.

The NYSE Hi-Lo Index closed at -307.00 on Tuesday and may have begun its next descent.  The decline in the Hi-Lo may gather strength as early as tomorrow and increase in trending strength through mid-March.


TNX appears to be in mid-correction with a possible target near 18.34 by the end of the week.

ZeroHedge reports, ” In a day when risk assets have been sliding and safe havens were generally bid, only to see a sharp reversal earlier in the session which pushed Treasury yields sharply higher with 2Y yields spiking 12bps from session lows, there was quite a generous concession ahead of today’s $52 billion 2Y auction.

And sure enough, the just concluded auction maturing on “leap” February 29, 2024 priced with stellar metrics all around, starting with the high yield which at 1.553 (the highest since Dec 2019) and sharply higher from last month’s 0.990%, stopped through the When Issued 1.559% by 0.6bps.

The bid to cover of 2.638 was also impressive, and while not nearly as high as last month’s 2.811, was well above the six-auction average of 2.56.”


Gold futures have pulled back from its the high yesterday at 1918.30, short of the June 1 high at 1919.20 and making a Master cycle high in the process.  The Cycles Model calls for a 2-month decline from here.  It could easily decline to the Lip of the Cup with Handle formation.  I have been gettin numerous calls about buying gold and have done my best to discourage them.


Posted in Published | 3 Comments

February 22, 2022

10:15 am

BKX, our liquidity proxy, has dropped beneath its 50-day Moving Average at 137.44.  Currently it is challenging that resistance, but may not last above it very long.  The Cycles Model suggests a Master Cycle low on or around March 4, indicating the “Fed Put” may be employed.  However, there are indicators that it could be extended another week.  In other words, the first attempt at market stabilization may fail.

RealInvestmentAdvice analyses, “The “Fed put?” Exactly, what is it, and where does this mythical support reside?

It isn’t surprising with the rough start to 2022, investors are hoping the Fed will look to stabilize financial markets. Of course, after more than a decade of monetary interventions, investors developed a “Pavlovian” response.

Classical conditioning (also known as Pavlovian or respondent conditioning) refers to a learning procedure in which a potent stimulus (e.g. food) is paired with a previously neutral stimulus (e.g. a bell). What Pavlov discovered is that when the neutral stimulus was introduced, the dogs would begin to salivate in anticipation of the potent stimulus, even though it was not currently present. This learning process results from the psychological “pairing” of the stimuli.

Importantly, for conditioning to work, the “neutral stimulus,” when introduced, must be followed by the “potent stimulus,” for the “pairing” to be completed. For investors, as each round of “Quantitative Easing” was introduced, the “neutral stimulus,” the stock market rose, the “potent stimulus.” 

As shown, each time a more substantial market correction occurred, Central Banks acted to provide the “neutral stimulus.”


8:00 am

Good Morning!

NDX futures have made new (bear market) lows, declining to 13591.90 before bouncing above the Lip of the Cup with Handle and Cycle Bottom at 13710.67.  Odds are better than even that the decline may continue beneath the Lip, causing a cascade of selling due to the short gamma that the NDX finds itself in for today’s options expiration.

ZeroHedge observes, “Global stocks and US futures have staged a remarkable recovery and erased overnight losses of as much as 2.2% as investors bet that the surge in geopolitical tensions will mean a less hawkish Fed and as investors clung to hopes that Moscow’s deployment of troops to two breakaway regions in eastern Ukraine will be as far Russia goes. S&P 500 futures were fractionally in the green at 715am ET after earlier sinking 2.2% and eyeing correction territory; European stocks trimmed losses as investors weighed the risk of geopolitical tensions in Ukraine. Benchmark Treasury yields pared their decline to trade at 1.92% and gold slipped.”

The spectre of war on Europe’s eastern flank had flared on Monday, sending oil prices to a seven-year high, less than a $1 away from $100, after Russian President Vladimir Putin ordered troops into the Donetsk and Luhansk regions of Ukraine.


SPX futures declined to 4255.50, just above the January 24 low and the Lip of the Cup with Handle/Cycle Bottom at 4169.00.  The Cycles Model suggests 8.6 days are left to the Master Cycle low.  Today’s options expiration shown calls prevailing at 4400.00 and above.  Puts have the majority beneath that with short gamma beginning at 4300.00.  At the very least, dealers and hedge funds must keep the SPX above 4300.00.  Wednesday’s options expiration show short gamma beginning at 4350.00.  A close today beneath 4300.00 may bring a meltdown on Wednesday.

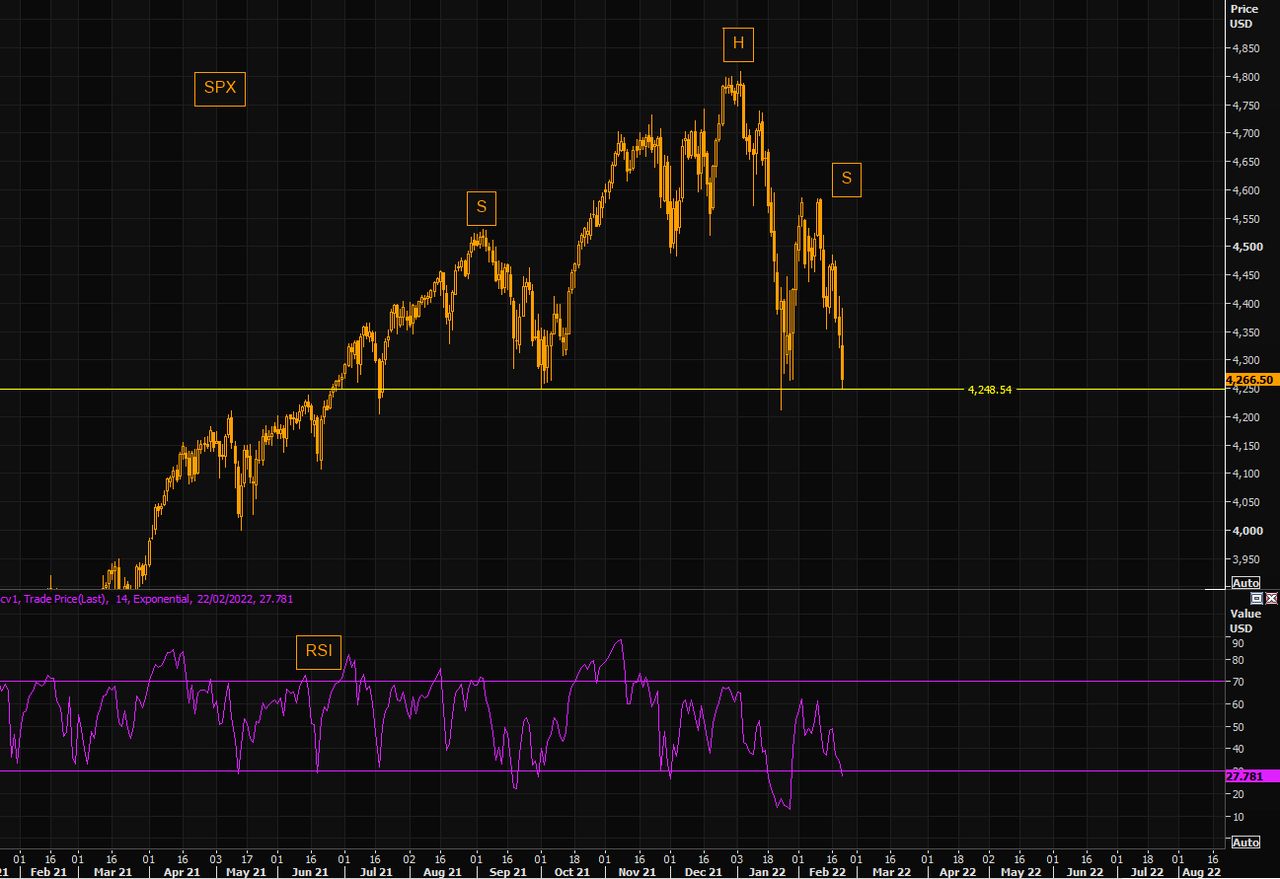
The-market-ear observes, “SPX – is this it?

We have not closed here or lower since last summer, but we did trade slightly lower during the January sell off. 4250 is the huge level to watch. RSI is oversold, but we have seen even more oversold conditions during more extreme sell offs. 4250 breaks and we risk the huge head and shoulders formation triggering, or 4250 holds and we put in a double bottom. Why not a bounce in order to frustrate people just in time for when every analyst has become an expert on wars…”


VIX futures reached an overnight high of 32.02 before settling back on the “good news.”  Today’s expiring options are long above 25.00 and long gamma kicks in at 30.00.  Once the VIX clears the previous high at 32.04, it may be unstoppable.  The Cycles Model calls for a Master Cycle high on March 14, 10 days beyond the Possible March 4 Master Cycle low in the SPX.  Considering that the Master Cycle low in the NYSE Hi-Lo Index is proposed on March 16, I would venture that the SPX (extended)low may be closer to mid-March, as well.


TNX bounced after a low of 19.18 last Friday, day 252 of its Master Cycle.  The Cycles Model suggests a Master Cycle low on Thursday and the Elliott Wave guidelines suggest a low near 18.00 at this time.  I had suggested earlier that TNX may decline to the Lip of the Cup with Handle.  It is still possible, but time is running out on this Cycle.  Depending on how fast it rises, the 50-day Moving Average ma be an appropriate target.


USD futures rose to 96.24 before easing back near Friday’s close.  The Cycles MOdel indicates the uptrend may continue through late March.  A 61.8% retracement of the 2020 decline gives a probable target of 98.30.


Gold futures made an overnight high of 1918.30, just shy of the 1919.20 made last June 1.  Today is day 266 of the current Master Cycle, so despite the week-long extension, gold has not been able to make a new high.  This does not bode well for the precious metal.  Despite the fact that gold reacts positively to political crises, liquidity may soon run out.


WTIC futures appear to be correcting an impulsive decline beneath its Cycle Top at 90.04.  The Cycles Model suggests it may raise though the end of the week, but not to new highs.  Instead, we may see a decline to the week of March 21.   While the reversal from the trendline high gave us an aggressive sell signal, the re-crossing of the Cycle Top confirms the sell signal.  The fundamentals say  “higher prices,” but the Cycles suggest that smart money may be making its exit.

ZeroHedge comments, “As Bloomberg’s Jake Lloyd-Smith wrote last night, oil markets are so bullish at present that forecasts for $100/bbl crude have become par for the course, which suggests that the threshold will be tested in 1H, “even if tensions over Ukraine cool,” which now appears improbably and is why $100 oil may come as soon as tomorrow.

As the BBG reporter notes, “the three-digit-barrel forecast surfaced at least a year ago and used to turn heads given it was bold, and prices were way, way lower back then. It’s founded principally on the case that energy consumption returning to normal as the pandemic ebbs will underpin gains”.

Goldman Sachs added its voice to the chorus not so long ago, when its chief commodity strategist and one of the closest-followed analysts on Wall Street, said he’s never seen commodity markets pricing in the shortages they are right now.”


Posted in Published | 1 Comment

February 21, 2022 Washington’s Birthday

9:00 pm

SPX futures have a chance of showing their true colors tonight as they have already slipped beneath Cycle Bottom support at 4274.17.  A “regular” decline would stop and bounce at the Neckline at 4200.00, confirming the Head & Shoulders formation.  However, should it go beneath the trendline (alternatively known as the Lip) we may see a limit down day tomorrow to 4100.00 or lower in a Cup with Handle formation.  SPX is now deep within short gamma territory (beneath 4300.00) where the decline may become self-reinforcing.

ZeroHedge reports, “As somewhat expected, the general risk-off theme has hit market as they reopened after Putin’s actions.

US equity futures extended their losses with Nasdaq down over 2.5%…

Treasury futures indicate a 5bps or so drop in the 30Y Yield to around 2.18%…


8:15 am

Good Morning!

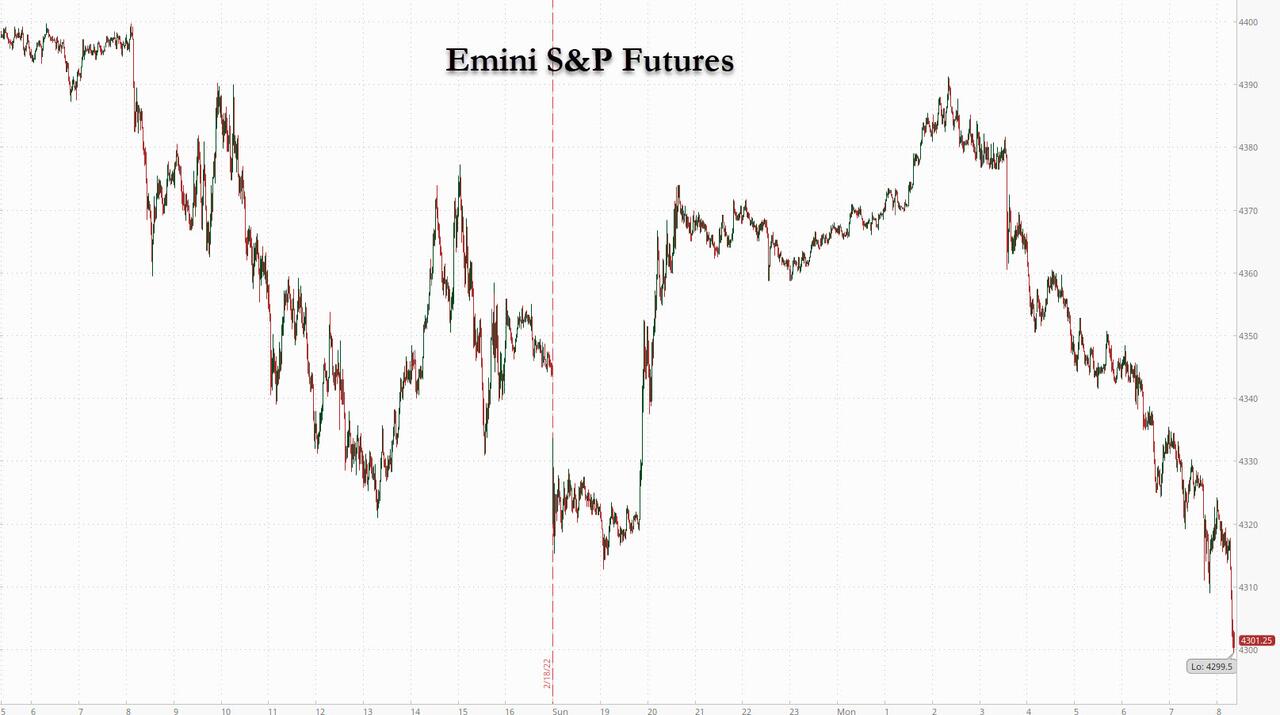
SPX futures rallied to a high of 4396.40 at 2:00 am, then sold off.  The financial markets are closed for President’s day, so all activity ceases at 9:30 am.  Tomorrow’s options expiration sows Max Pain at 4355.00 while puts gain dominance at 4345.  Short gamma is likely to start below 4300.00.  The daily trading band is narrowing, suggesting a potential panic decline beneath 4300.00.

ZeroHedge reports,”Any hope of de-escalation following the news late last night that Putin and Biden had agreed to a Macron-organized summit to pursue a diplomatic path out of the Ukraine crisis lasted only a few hours, and died a painful death around 3am Eastern time, after Kremlin spokesman Dmitry Peskov poured cold water on the summit progress when he said that  “It’s premature to talk about any specific plans for organizing any kind of summits” and that there are no “concrete plans” for a summit yet. Subsequent news that a mortar shell had destroyed a Russian border checkpoint near Rostov – something which Ukraine’s military denied doing – did not lift the already downbeat mood, but it was the news just after 7:40am ET that Russia had killed five “saboteurs” who tried to violate its border (and which Ukraine once again slammed as fake news) in an unconfirmed incident that would be the first direct clash with Ukrainian forces, that sent US equity futures tumbling 0.92% to session lows of 4,299.5, down some 90 points from overnight highs, and hit global risk assets while safe havens such as gold and the dollar spiked. The 1.5% decline in Nasdaq 100 futures outpaced that of S&P 500.”


VIX futures are flat due to President’s Day.  Should they reflect the action in the SPX futures, we might be seeing new highs in the VIX.


TNX futures are also flat this morning, due to President’s Day.  It is due for a Master Cycle low later this week, making it likely that it may test or challenge the Cycle Top support at 19.06.

ZeroHedge remarks, “Back in April 2018, when the world was growing briskly, the global economy was firing on all cylinders, the US was merrily hiking interest rates and shrinking the Fed’s balance sheet without a cloud in sight, the repo crisis was over a year into the future and the covid crash wasn’t due for almost two years, we noted a strange move in a very underfollowed – if critical and very forward looking – corner of the market, and wrote that “this would imply some expectation priced in of a reduction in the Fed policy rate around Q1 2020; that or the market starting to actually price in – and not just contemplating – the next Fed policy error, i.e., hiking right into the next recession.”

What was this indicator that correctly predicted the most iconic event of the post Lehman generation, to the quarter if not the month?

Well, we were looking at the forward curve for the 1-month US OIS rate, perhaps the best predictive proxy for the Fed policy rate, and noted that it had inverted after the two-year forward point. This was notable because, as we also said then, such an inversion had happened “only three times over the past two decades: in 2005, 2000 and 1998.” Of course, 2018 was another such inversion, one which prompted us to predict – two years ahead of time – that Q1 2020 is when the Fed would cut rates and in retrospect, we were spot on as that’s when the Fed fired its bazooka and not only slashed rates to zero to fight covid, but also unleashed the biggest ever bond buying program ever while also backstopping the corporate bond market to avoid the total collapse of the Western financial system in the aftermath of the covid global economic shutdown.

We bring this up because not only is the 1 month OIS spread between the 2Y and 3Y fwd negative again – for only the fifth time in history – but it is now the most negative it has ever been!”


Posted in Published | 3 Comments