April 5, 2022

8:15 am

Good Morning!

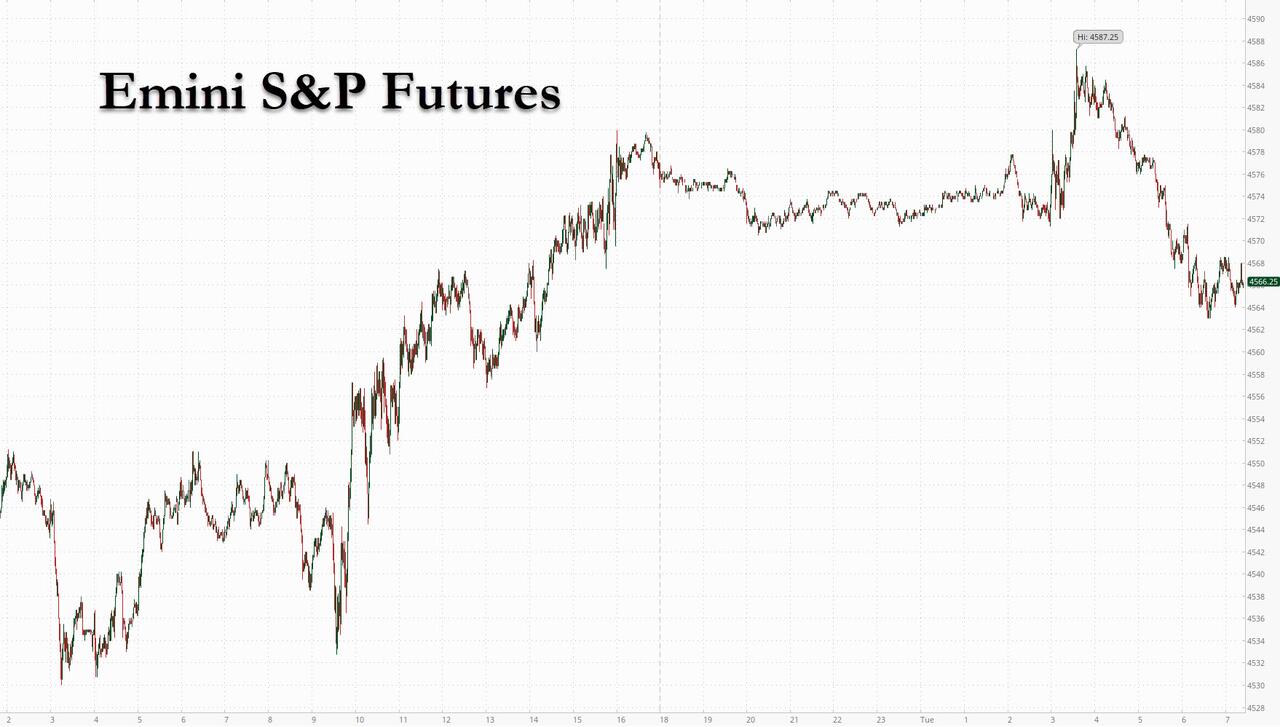
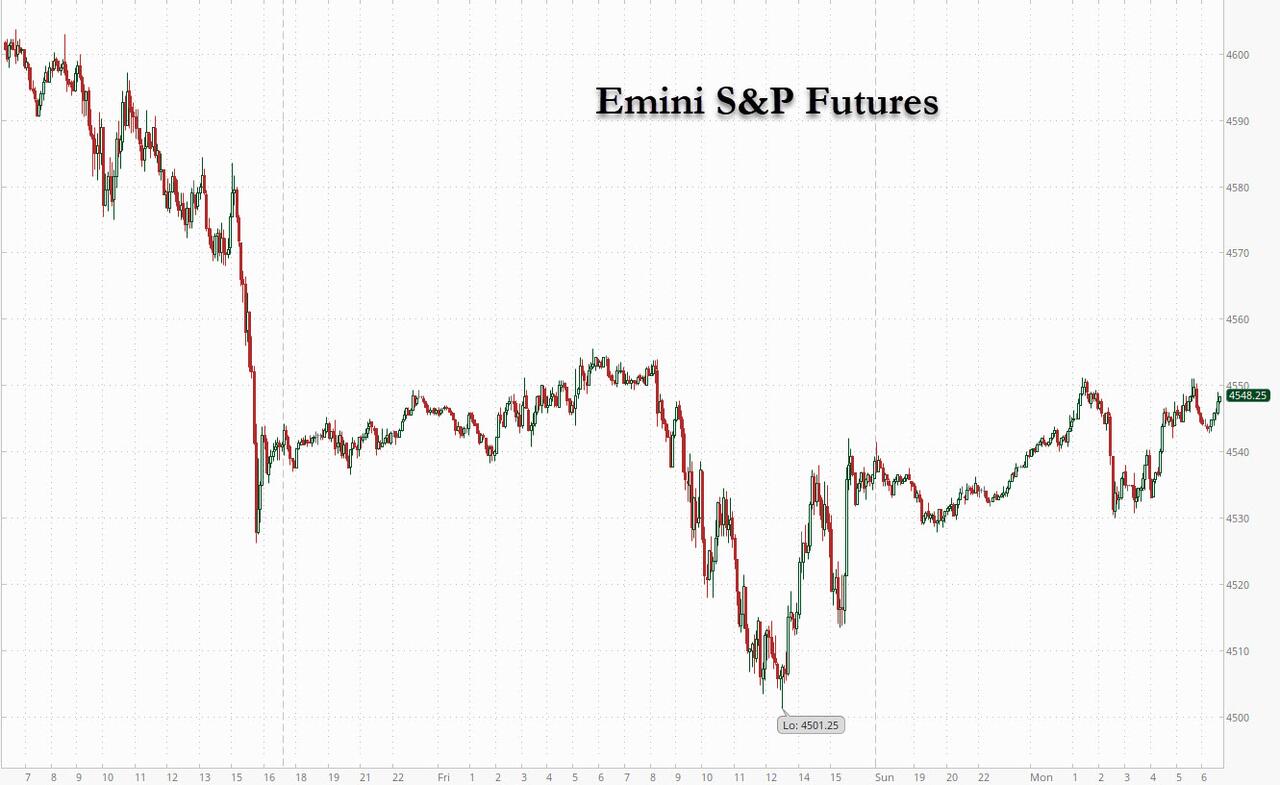
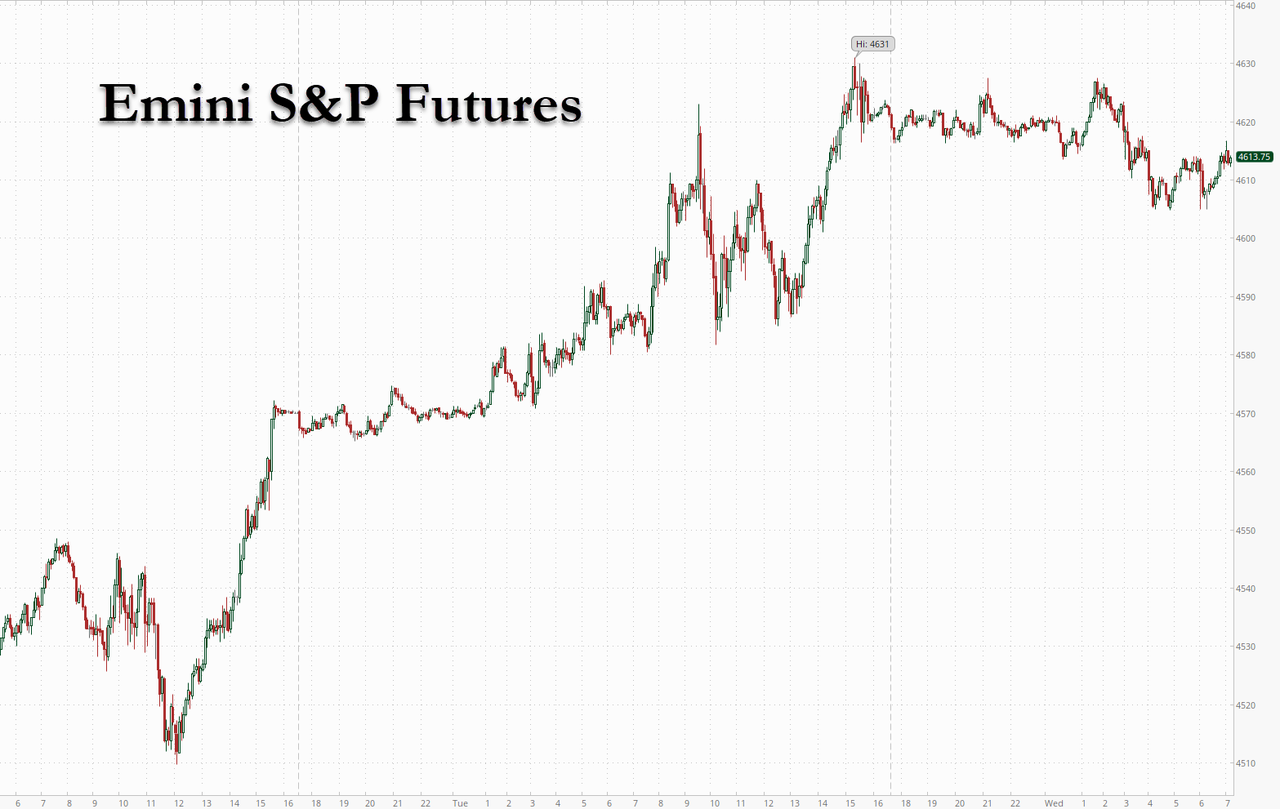
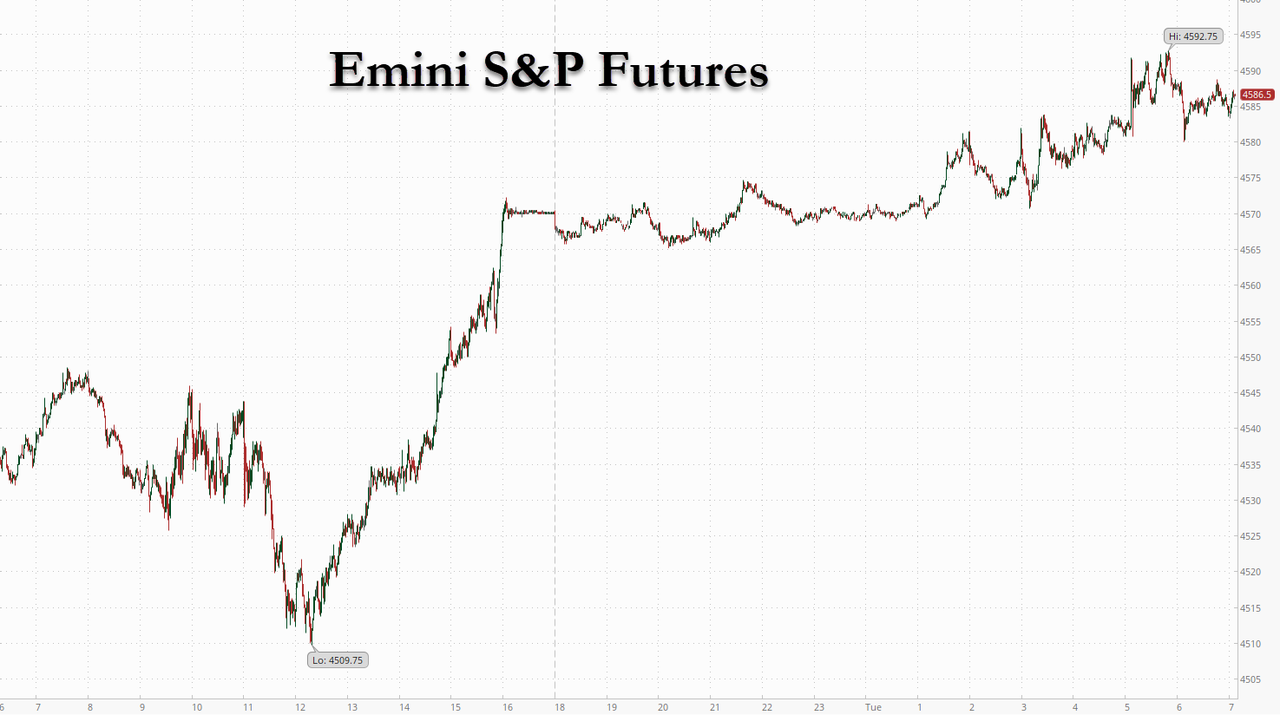
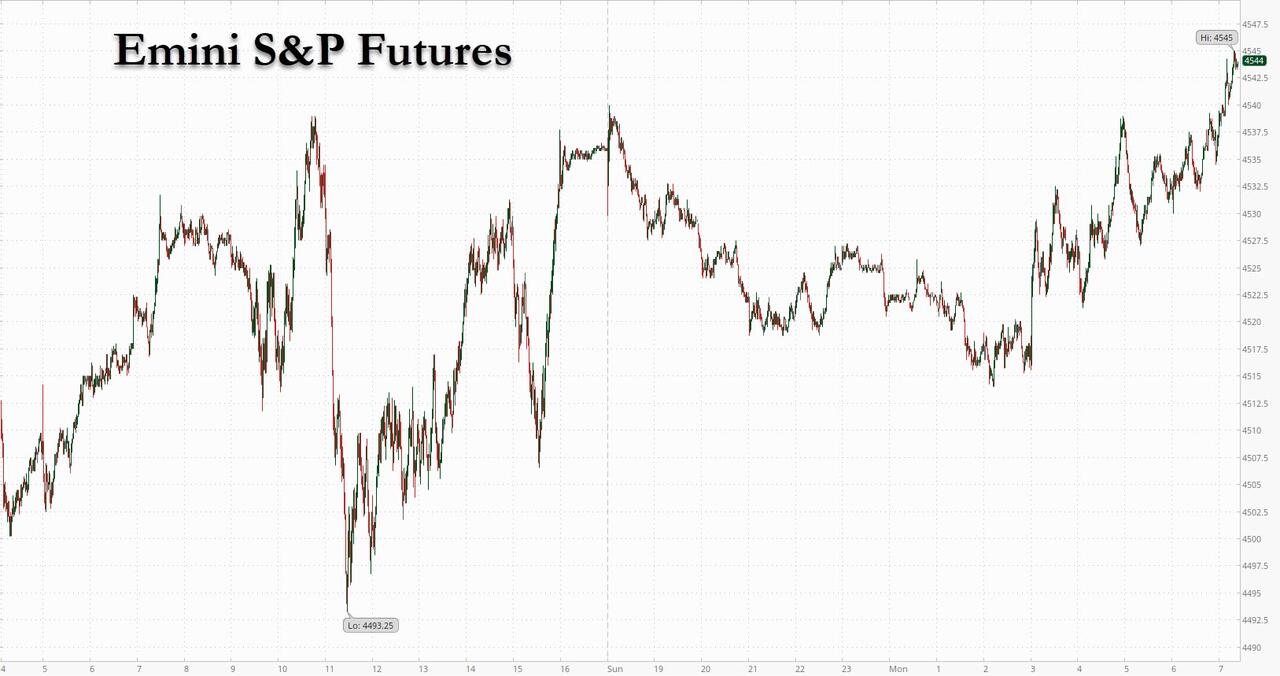
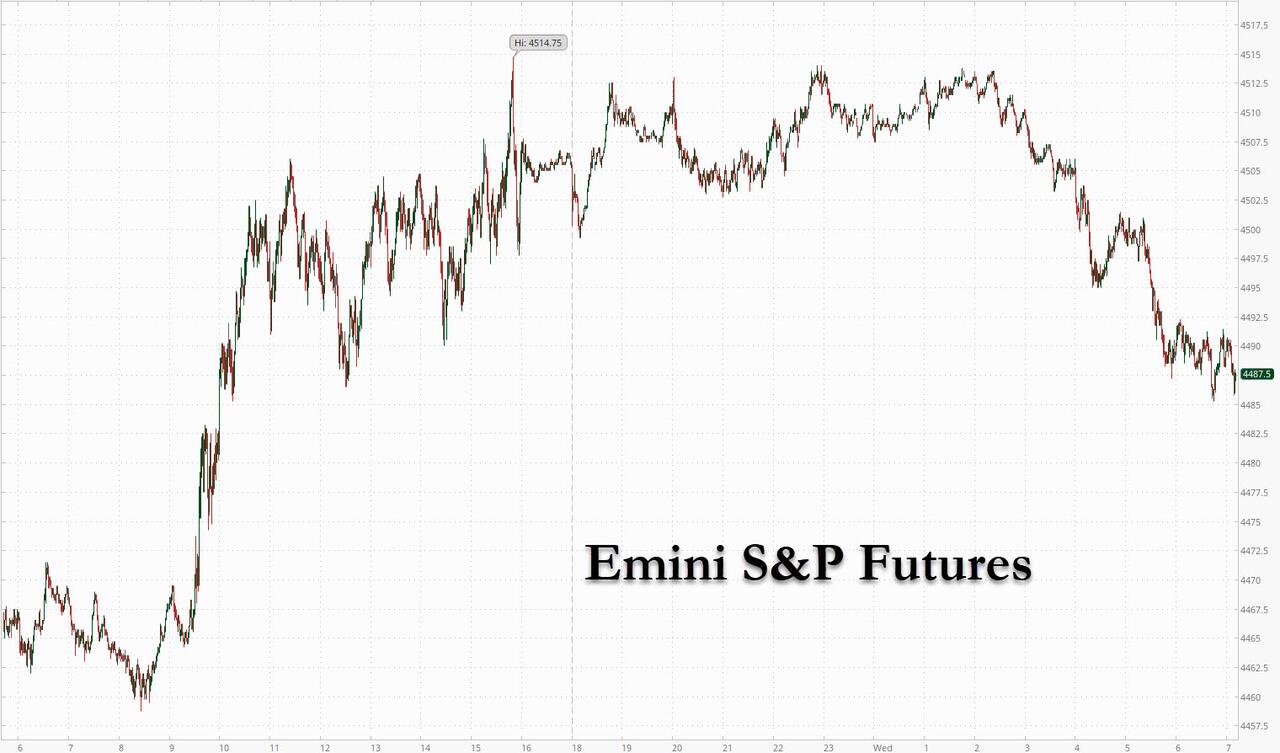
SPX futures made a 78.6% retracement yesterday, then started easing down in the overnight market.  For tomorrow’s expiring options, Max Pain is at 4570.00.  It is bounded by long gamma at 4600.00 and short gamma at 4500.00.  The Cycles Model shows trending strength reappearing today and Friday.  Should SPX decline beneath mid-Cycle support at 4502.40, the trend will be down.

ZeroHedge reports, “After initially trading sharply higher around the European open, US stock futures dropped to session lows as traders digested the latest developments in the Ukraine war, including a EU proposal to ban Russian coal imports, the same coal which we profiled yesterday as hitting record highs on lack of Russian supplies and where Russia accounts for nearly half of all European coal imports… it makes one wonder if Europe can’t stop, won’t stop until it commits energy suicide.

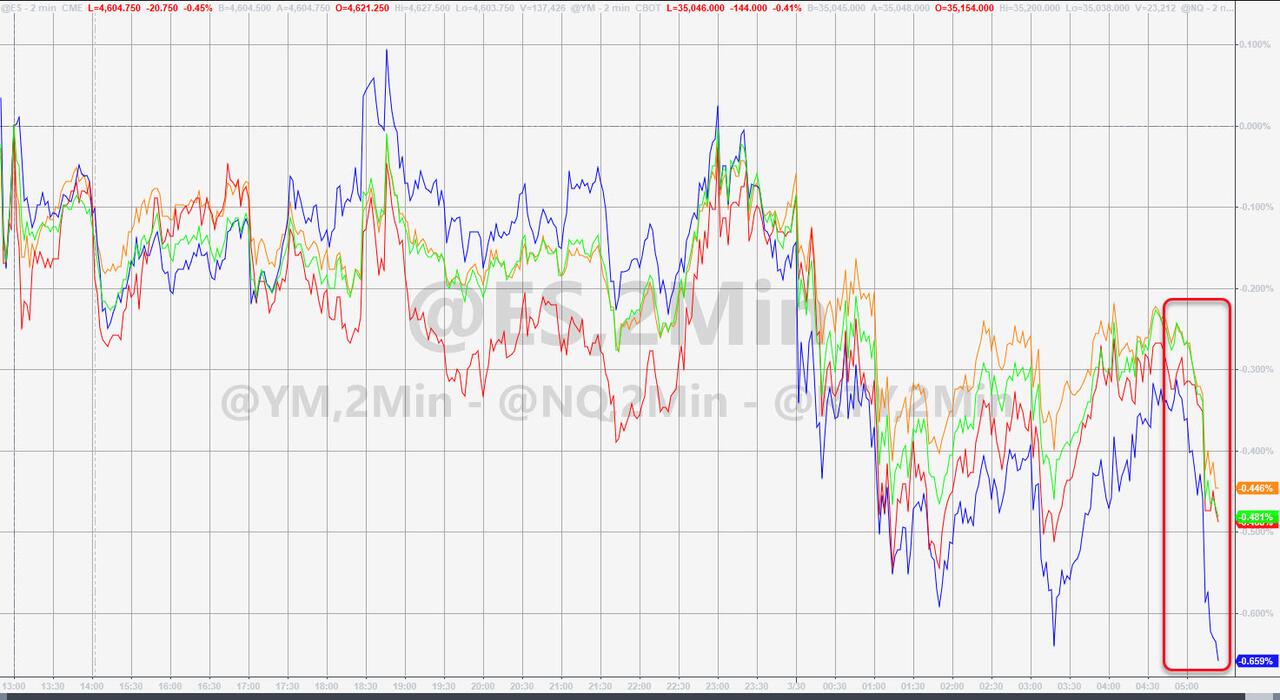
In any case, S&P500, Nasdaq 100, and Dow Jones futures all fell 0.3% each, with Bloomberg adding that the European Commission is also expected to propose banning most Russian trucks and ships from entering the bloc, although the EU isn’t planning to sanction oil or gas for now.”


VIX futures rose above 19.00 after extending its Master Cycle low to day 279.  The lengthy Cycle may be attributed either to dealers and hedge fund attempting to push the SPX higher through the back door or it may be a huge influx of retail investors buying the short VIX ETFs.  In either case, someone will be burned.  The Cycles Model suggests a rally in VIX through the end of the month is imminent.


TNX is marching higher as it may touch the rising trendline above 25.00 before the final retracement down to the Cycle Top support at 22.50.   This move may happen yet this week, as trending strength comes roaring back next week.


Posted in Published | 1 Comment

April 4, 2022

1:45 pm

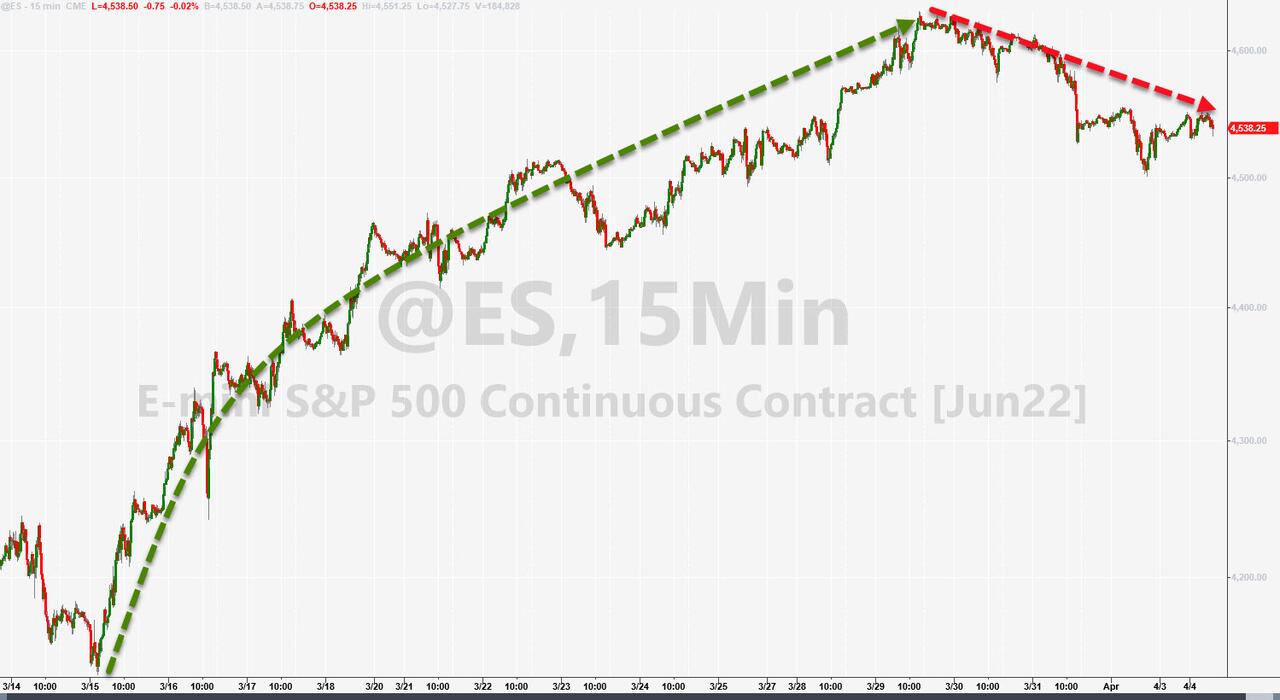
SPX has made a 52% retracement and may  turn down at any time.  Investors may short the SPX beneath 4500.00.

ZeroHedge advises, “We have perhaps seen the end of the recent meltup as Nomura warns markets are suffering from some “macro fatigue”…

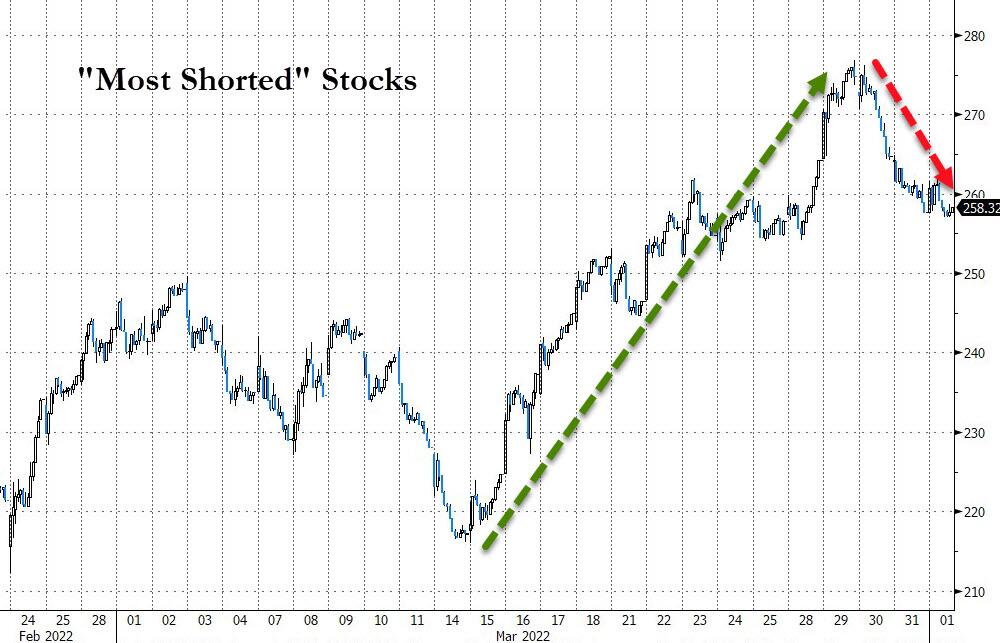
…and BofA confirmed in a trading desk note this morning that “our model’s S&P 500 short could be fully covered…” adding that “we are in the late-stages of a short-cover-rally as the implied vol spike in heavily-shorted names has started to fade…”


10:07 am

The GSCI Ag Index appears to be holding at Intermediate-term support at 537.40 and may be about to resume its rally higher.  The next Master Cycle (high) may come at the end of April, giving it plenty of time and space to rally.  While no specific target is evident, the technical landscape suggests highs between 800.00 and 1000.00.

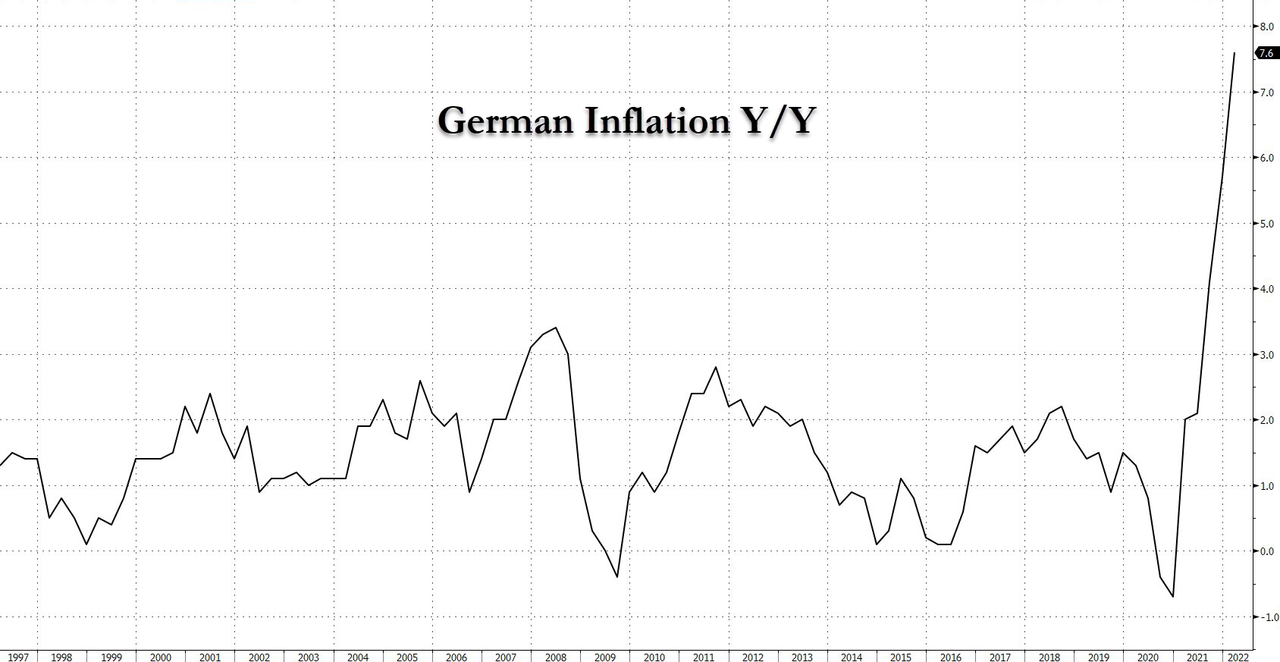
ZeroHedge observes, “Just days after Germany reported the highest inflation in generation (with February headline CPI soaring at a 7.6% annual pace and blowing away all expectations), giving locals a distinctly unpleasant deja vu feeling even before the  Russian invasion of Ukraine broke what few supply chains remained and sent prices even higher into the stratosphere…

… on Monday, Germany will take one step toward a return of the dreaded Weimar hyperinflation, when according to the German Retail Association (HDE), consumers should prepare for another wave of price hikes for everyday goods and groceries with Reuters reporting that prices at German retail chains will explode between 20 and 50%:


9:45 am

BKX is due for a Master Cycle low as early as today as it hits the Lip of the Cup with Handle formation.  It may mean a retest of the mid-Cycle resistance and trendline at 132.37.  There appears to be trending strength at the end of the week.  However, BKX is in a downtrend, suggesting the decline may resume very quickly in a potential phase-shift to a panic decline.  This juncture is very hard to define, so forgive my speculation if I am wrong.

ZeroHedge comments, “While his friend and fellow Democrat Larry Fink used his latest annual letter to cheer for an accelerating transition to ESG while simultaneously warning about the fallout from “de-globalization” spurred by Russia’s incursion into Ukraine, JPMorgan CEO Jamie Dimon warned Monday in his own annual letter to investors that the US economy faces “unprecedented” risks from the confluence of COVID pandemic, high inflation and, of course, the situation in Ukraine.

“They present completely different circumstances than what we’ve experienced in the past – and their confluence may dramatically increase the risks ahead,” Dimon said.”


7:45 am

Good Morning!

NDX futures rose to a weekend high of 14936.70, but has since eased back from the high.  In today’s options expiration, QQQ (Friday’s close: 361.85) prices beneath 360.00 favor puts, while short gamma may start as high as 355.00.  Calls dominate above 362.00, but call volume is thin, making it difficult to judge where positive gamma begins.  In all, QQQ/NDX are testing short gamma again.  This morning shares got a boost when Musk took a 9.2% stake in Twitter.

ZeroHedge reports, “After suffering tremendous losses in January and February, March was a very confusing month for hedge funds: as JPMorgan’s Prime Brokerage writes in its monthly note, the start of March was characterized by one of the largest de-grossing episodes among Equity L/S funds in N. America, along with quite significant net selling globally (especially in APAC), and resulted in some marquee names such as Tiger Global suffering massive losses.

So as markets closed out the month and quarter with a very sharp rebound in equities, most funds were again caught by surprise, while few are willing to embrace the recent move higher in risk as a persisting trend.”


SPX futures also got a boost, rising to 4556.70 before subsiding.  In today’s expiring options, Max Pain is at 4545.00.  SPX options turn negative at 4535.00 and short gamma resumes at 4500.00.  This confirms the next level of intensity in the decline beneath mid-Cycle support at 4501.42.  While options become positive above 4560.00, positive gamma doesn’t kick in until 4600.00.

Should SPX decline beneath mid-Cycle support, the trend becomes short.  The Cycles Model indicates increasing trending strength this week.

ZeroHedge reports, “US futures rose along with stocks in Europe and Asia, as corporate news took some of the focus off developments in the Ukraine war, where peace talks are expected to resume on Monday. Nasdaq 100 futures led gains among other gauges, climbing as much as 0.4% with S&P futures up 0.2%, while equities also rose in Europe. Twitter soared as much as 29% in premarket trading after Elon Musk took a 9.2% passive stake in the company. Tesla shares also rose after the automaker posted record first-quarter deliveries despite supply chain and logistical constraints, taking other electric-vehicle stocks higher as well.


VIX futures got a boost to a high of 20.74 over the weekend.  However, it remains beneath mid-Cycle resistance at 21.07.  Wednesday’s expiring options show Max Pain at 21.00, which explains the hesitancy to rise above mid-Cycle resistance.  Short gamma begins at 20.00, while long gamma begins at 25.00.  Should VIX rise above its mid-Cycle resistance, it may experience trending strength during monthly options expiration and in the final week of April.


NYSE Hi-Lo Index made its Master Cycle extended (272 days) high on Wednesday at 149.00.  The Hi-Lo issues a sell signal with a close beneath 0.00, with confirmation beneath mid-Cycle support at -59.33.  The Cycles Model suggests an upcoming Master Cycle low in about three weeks.  However, it may linger near the low through the end of the month.


TNX opened at the lower end of Friday’s trading range.  It may test the Cycle Top at 22.31 this week before a return of trending strength next week.  The Cycles Model suggests a Master Cycle high may be made the week after options expiration.


USD futures are rising out of their Master Cycle low last week to challenge the Cycle Top resistance at 98.96 today.  The Cycles Model anticipates a very short Master Cycle ending on or near April options expiration.  The intended target may be 100.00, or slightly higher.


Posted in Published | Comments Off on April 4, 2022

March 31, 2022

7:00 am

Good Morning!

I am getting an early start because I am spending time this morning with three granddaughters, all under the age of 5.  Yikes!  I am “re-using” charts from yesterday afternoon, since StockCharts appears to be down.  Perhaps it is due to the mass coronal ejection that is hitting us this morning.  Our location is having a strong wind storm that is rattling the house and is due to bring in snow by the end of the day.

SPX futures retraced above the trendline overnight, hitting 4620.00 before giving up all of its gains.  It is currently in the red beneath the trendline and may be going lower.  Tomorrow’s op-ex shows Max Pain near 4550.00 with positive gamma at 4650.00 and short gamma beneath 4520.00.

The Cycles Model suggests a repeat performance for Wave (3) in time.  The decline into the Master Cycle low is scheduled to take 51 days, just as the prior decline did.  However, that is where the similarity ends.  Wave (3)s can never be the smallest Waves.  In the 2008 decline [SuperCycle Wave (a)], Waves threes were consistently 1.5 times the sized of Wave ones.   SuperCycle Wave (c) should be a multiple of SuperCycle Wave (a).  By all indications, Wave (3) may be triple the size of Wave (1).  The Cup with Handle target of 2542.00 agrees, in this case.

ZeroHedge reports, “US equity futures were muted and flat on the last trading day of the month and quarter, fading a modest overnight gain as the underlying index headed for its first quarterly decline in two years on worries about surging inflation, hawkish monetary policy and an economic slowdown. Contracts on the S&P 500 were down 0.1% at 730 a.m. ET while Dow futures were little changed and Nasdaq 100 futures rose 0.2%, while European stocks fell, heading for the first quarterly decline since 2020. Asian equities retreated on lackluster Chinese PMI data and regulatory concerns. Treasuries held gains with the 10Y yield dropping to 2.31% (from 2.50% earlier this week when the 2s10s inverted) and the dollar ticked up against almost all G-10 peers. Fed watchers will be focused on the PCE deflator, which may have sped up in February.”


VIX futures have been climbing steadily all night and are currently at 20.27.  Should the decline in SPX get underway we may see a sharp reaction from the VIX.  The first buy signal comes above the mid-Cycle resistance at 21.03, but you may wish to accumulate shares (ETFs or options) before that event.  The Cycles Model shows the new Master Cycle in the VIX peaking at the end of April.


TNX futures have declined to a low of 23.11 this morning, keeping in stride with a possible retracement to the Cycle Top at 21.89.  Why that level?  Wave threes often “walk” along the Cycle Top, once they have emerge above that support, due to the strength of that phase in the Cycle.  There may be a decline to the Intermediate-term support at 20.70, but I would lay odds that the Cycle Top will hold.

ZeroHedge observes, “Rates – big levels coming up

Consensus about yields spiking further is strong. In our thematic email, Ready for the rates reversal?, we pointed out some facts that the move higher in rates had the potential to reverse/take a pause. Since then rates have come down and are approaching rather big levels. Things could get “dynamic” should we see yields move slightly lower as we risk taking out rather big supports.

US 10 year – is that a reversal in the making?

Quick short term levels for the mighty US 10 year. First support for yields coming in around the 2.3% level. Note that the 21 day moving average is still way lower. Next big support is down at 2.05% where the 50 day comes in. Resistance is the recent high in the 2.5/2.55% area.”


Posted in Published | Comments Off on March 31, 2022

March 30, 2022

3:05 pm

SPX appears to be crossing its Ending Diagonal trendline at or near 4595.00.  It’s time to start put on short positions.

Good luck and good trading!


8:05 am

Good Morning!

SPX futures dipped to a morning low of 4610.20 before a small bounce beneath yesterday’s close.  Today is day 34 (34.4) of a rally after a 51-day (51.6) decline, totaling 86 days in a potentially completed top-to-top Cycle.  The Cycles Model suggests a possible final burst of strength today before a reversal that may occur yet by the close.  Retail investors and hedge funds may finally be getting up the courage to go long again as the Hi-Lo Index closed at 43.00, second highest only to March 21 at 57.00.  Most of the rally until then has been short covering, which kept the Hi-Lo Index in the negative.

Today’s options expiration shows Max Pain at 4575.00 with options positive over 4585.00 and negative beneath 4570.00.  This leaves room for the decline to begin today, all else being equal.

ZeroHedge reports, “S&P 500 futures edged lower along with European shares, as the “peace in our time” optimism that pushed stocks on a history bear market short and gamma squeeze rally in the past two weeks fizzled and was instead replaced with the far less pleasant reality that de-escalation of the war in Ukraine is exaggerated as the Kremlin said that talks with Ukraine in Istanbul Tuesday yielded no breakthroughs and refused to discuss the status of Crimea as part of a peace deal, as the Russian constitution prohibits anyone discussing the fate of Russian regions. The S&P futures were 0.3% lower while Nasdaq futures declined 0.4%. Commodities climbed, fueling renewed concerns about inflation’s impact on profits and economic growth while the inversion of the 2s10s yield curve that started the clock on the next recession did not help investor mood. Europe’s Stoxx 600 snapped a three-day winning streak after surging to the highest level in five weeks and oil futures gained over 2%. The dollar slipped, the euro climbed and the yen bounced from a six-year low after the Bank of Japan pledged to buy more securities than planned and include longer-dated debt.”


VIX futures rose to 19.80 this morning and appear to remain buoyant throughout the morning.  Today’s expiring options are positive above 18.00 and long gamma takes effect at 25.00.  The VIX Cycle may be complete with an 84-day bottom-to-bottom cycle as of yesterday.

ZeroHedge observes, “Having soared on optimism yesterday amid chatter of Russian forces retreating, Ukrainian President Zelenskiy poured some cold water on that hope by noting that Russia is sending new forces during a speech to the Norwegian parliament. He also warned that he sees risk in the Black Sea from Russian mines.

That headline triggered selling in futures and the algos too stocks to overnight lows…”


TNX hesitated this morning, but has not changed its corrective stance.  The Cycles Model suggests a corrective mode into next week before another surge of trending strength reappears.  A probable decline to the Cycle Top support at 21.89 may still be in the works.

ZeroHedge comments, “The Federal Reserve and other central banks took ownership of the bond markets during the pandemic with zero-bound rates. Now they are busy breaking them.

The bleak reality for investors is that bonds are at risk of turning into just another speculative asset, and a particularly focused area for speculation — what the Fed will do next is becoming almost the only question that matters, rather than one of the key questions.

The fallout from all these central bank maneuverings is degrading the haven qualities of fixed-income securities and threatens to turn yield curves into mere noise, rather than reliable signals about real-world economics.”


USD futures turned lower, declining to a low of 97.85 this morning.  There is a new Master Cycle which is due to end in mid-April.  Should the USD not decline beneath the Wave [iv] low at 97.71. it is possible that the final surge to 100.00 or higher may yet occur in the next two weeks.


Crude oil futures advanced above the Cycle Top at 105.72 in a corrective bounce which may last until the weekend, per the Cycles Model.  The current Master Cycle ends in mid-April, suggesting a further decline.

ZeroHedge informs, “Pipelines are the primary method of transporting crude oil around the world, delivering oil and its derivative products swiftly to refineries and empowering reliant businesses.

And, as Visual Capitalist’s Christina Kostandi and Niccolo Conte detail below, North America is a major oil hub, with the U.S. and Canada alone are home to more than 90,000 miles of crude oil and petroleum product pipelines, along with more than 140 refineries that can process around 20 million barrels of oil every day.

This interactive graphic uses data from Rextag to map out crude oil pipelines and refineries across the U.S. and Canada, showcasing individual pipeline diameter and daily refinery throughput.”


Posted in Published | Comments Off on March 30, 2022

March 29, 2022

12:15 pm

VIX has stretched its Master Cycle to 273 days, an unusually long stretch.  However, there is some light at the end of the tunnel, as Wave (c) reaches equality with (a) at 18.51.  The stretch may be over, or nearly so.  Prepare for the panic blow-back on the next move, as a slingshot move may be in play.

ZeroHedge suggests, “Don’t buy protection when you must…

…buy it when you can. The VIX guy managed nailing it again. Since his latest call on March 9 (here), VIX has collapsed. VIX needs to double from here in order to reach the most recent highs. When was the last time you bought something and it doubled? Now is the time when you can buy it…”

11:55 am

GKX bounced from the Intermediate-term support at 530.53 this morning on day 263 of the Master Cycle.  It is likely to have one more probe deeper, possibly as low as the 50-day Moving Average at 507.12.  Wave C of (2) achieves equality with Wave A at 515.00.  The March 8 peak at 592.02 exceeded the March 2011 high at 570.50 giving GKX a breakout status with a potential of reaching 900.00 or higher by the end of the year.

ZeroHedge explains, “t was a spooky time to be out at sea off the US East Coast on Halloween in 1991. A strong storm system over the maritime provinces in Canada merged with the remnants of Hurricane Grace, forming a new, epic, and dangerous Nor’easter. The winds of this new storm breached 70 miles per hour and a wave as high as 100 feet was measured off the coast of Nova Scotia, but the storm was not renamed as either a tropical storm or a hurricane – instead, it is known only colloquially as simply the Perfect Storm. Six fishermen from Massachusetts perished when their vessel Andrea Gail sunk in open waters, and the story of the storm and of that tragedy became the subject of a best-selling book and a blockbuster feature film.

While the concept of a perfect storm is often too casually assigned in popular culture, it is difficult to find a more apt description of what has been unfolding in the global agriculture markets over these past several months. The tempest caused by the European energy disaster has merged with the hurricane of consequences flowing from Russia’s invasion of Ukraine, forming the genesis of a generational crisis in food that will leave few unaffected. While we’ve been warning about just such a scenario for some time, after spending the past two weeks traveling across the US Midwest and conferring with our contacts in the agricultural sector, even we are a little spooked by what we’ve learned. In a financial crash, the correlation between all asset classes converges to one. The coming crash in global food supply will be driven by a similar phenomenon across virtually every input into farming – they are all spiking to historic highs simultaneously, supply availability is diminishing across the spectrum, and the time to reverse the worst of the upcoming consequences is rapidly running short.

Other than that, things are great.”


8:30 am

Good Morning!

SPX futures have risen to an overnight high of 4617.60, where Wave C is 1.5 times the size of Wave A.  The point to be made here is the NYSE Hi-Lo Index closed at -64.00 yesterday, suggesting the only players may be the dealers and overseas buyers and not the retail clients who are still reluctant to go long, but may be more interested in selling the high and exiting the market as best they can.

ZeroHedge reports, “Following yesterday’s surge in stocks following an FT report that Russia has eased on its Ukraine demands and the Russian ceasefire document no longer contains any discussion of three of Russia’s initial core demands – “denazification”, “demilitarisation”, and legal protection for the Russian language in Ukraine – overnight futures have extended their “feel good” rise as peace negotiations which resumed on Tuesday in Turkey between Russia and Ukraine stoked a rally in global equities, and hit session highs after Ukrainian negotiator Podoliak noted that a ceasefire is being discussed with Russia adding a press conference is to be expected later. Ukraine is striving for a cease-fire agreement in talks with Russian negotiators that started Tuesday in Turkey, setting a “minimum” goal of an improvement in the humanitarian situation. Nasdaq 100 futures were up 0.6% while S&P 500 futures gained 0.5% and Dow futures 0.4%. Europe’s Stoxx 600 Index also advanced, with auto and consumer stocks outperforming. Oil fluctuated as investors weighed the impact of China’s mobility curbs against a Covid resurgence on demand; the dollar dropped. Treasuries bear flattened, outperforming bunds and gilts as haven demand continues to be unwound; the 10Y TSY yield rose to 2.50%.”


VIX futures may be consolidating beneath the mid-Cycle resistance at 21.02 after a 272- day Master Cycle.  This leaves an entire month of potential rally as the next Cycle Pivot is at the end of April.

CharlesHughSmith instructs, “Stocks don’t vanish when sold; somebody owns the shares all the way to the bottom. These owners who refuse to sell because they have convinced themselves the next dip will be the hoped-for resumption of the bullish trend are called “bagholders.”

Trends are tricky. Humans anticipate the present conditions will continue on into the future. In economics and finance, we call this continuation a “trend.” Trends continue until something fundamental changes and the trend takes a new course.”


TNX has pulled back to 24.37 this morning as it consolidates after a dizzying rally. It may pull back to the Cycle Top support at 21.74 in the next two weeks but, soon afterward, may break above the trading channel of the last 4-6 months.

ZeroHedge reports, “With interest rates marching relentlessly higher both in the US and across the world, even as much of the yield curve pancakes and inverts to pre-recession if not pre-depression levels…

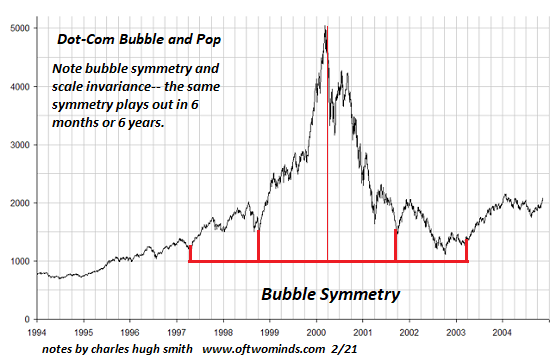
… because the last time the 2s30s 1Y fwd was here, the dot come bubble burst…

… Wall Street has once again shifted its tune for obvious reasons, and while no longer predicting the yield curve can’t invert – pretty much everyone now acknowledges it’s just a matter of time, with Goldman predicting 2s10s goes negative next quarter..


USD futures have declined beneath the Cycle Top support at 98.78 to a morning low of 998.13.  This was done without exceeding the prior high at 99.43 to complete the final impulse.  Today is day 265 in the current Master Cycle, so time is running out for a new high.  I am reluctant to make a call on a reversal yet, although yesterday’s high at 99.36 may have been the end of a truncated impulse.


Crude oil futures have declined this morning to a low of 98.56, violating three supports in the process.  It is on a confirmed sell signal with about 4 weeks of decline ahead of it, according to the Cycles Model.

ZeroHedge reports, “A recently published analysis by a consumer advocacy nonprofit maintains that shutting a 4.5-mile section of a nearly 70-year-old pipeline that spans the Great Lakes from Wisconsin to Ontario would impose $23.7 billion in higher fuel costs on families and businesses in Indiana, Michigan, Ohio, and Pennsylvania.

Damage to anchor support EP-17-1 on the east leg of the Enbridge Line 5 pipeline within the Straits of Mackinac in Michigan is seen in this June 2020 photo.(The Canadian Press/HO – AP, Michigan Department of Environment, Great Lakes, and Energy)

Consumer Energy Alliance’s (CEA) 14-page report estimates that closing Canada-based Enbridge’s Line 5 pipeline in the Straits of Mackinac, which connect Lake Michigan to Lake Huron, would spur regional fuel price spikes of 9.47 to 11.66 percent “independent of any other market conditions, such as the surge in fuel prices observed over the past 12 months that are tied to international oil markets and logistical challenges caused by the pandemic.”


Gold futures smacked down to a morning low of 1888.40, just above the 50-day Moving Average at 1886.85.  It is on a sell signal and may decline to the week of April 25, says the Cycles Model.  It may decline as far at the mid-Cycle support at 1820.57.  There are still many writers who insist that gold is “real money.”  However, the fact that gold can be confiscated and is unable to travel across borders is limiting the value of gold as a currency.


Posted in Published | 15 Comments

March 28, 2022

2:12 pm

I reported last week that the March 17 low in GKX may have been ins Master Cycle low on day 251.  Today is day 262 and no new lows have been made.  It appears that the mid-Cycle support at 556.58 may be preventing a new low from being made.  While the rally off the low seems insignificant, it is impulsive (5 Waves), suggesting the new Master cycle has begun.


1:58 pm

BKX, our liquidity proxy is declining from the trading channel trendline an the 200-day Moving Average at 131.75 after challenging it last Friday.  This is likely to be our sell signal with a near-term target at the Cycle Bottom by the first week in April.  It appears that the decline may speed up as the Ukraine crisis heats up.  There is another consideration appearing today   See below.

ArmstrongEconomics writes, “I reported on the Private Blog that I had a copy of the legislation and I was told it would be introduced today – Monday 28th. That info was correct. Well, here it is!. Reps. Stephen Lynch (D-Mass.), Jesús Chuy Garcia (D-Ill.), Ayanna Pressley (D-Mass.), and Rashida Tlaib (D-Mich.), all Democrats, have introduced the “Electronic Currency And Secure Hardware Act” (ECASH Act) that does far more than just creating a digital currency. This Act cleverly strips the Federal Reserve of its authority to create the money. ”


1:37 pm

SPX has fulfilled all the requirements for a 61.8% retracement of Wave (1) at 4550.00.  The NYSE Hi-Lo has declined to -39.00 today, showing internal weakness.  However, Wave twos may retrace all the way back to the origination of Wave one (4818.62).  In addition, Wednesday (day 255) shows trending strength, making it the more likely daily peak to finish off the first quarter.  Should the rally continue, the next resistance is the 2-hour Cycle Top at 4587.43.  While there is no overt sell signal, it would be wise to start accumulating hedges at this time.


10:00 am

Some people go to Florida for Spring Break.  Others head north for the steelhead run.  That’s me, fly fishing in a catch-and-release section of the Pere Marquette.  The temperature was 22 degrees.  But the steelies were running.


8:20 am

Good Morning!

After a weekend decline to 4520.60, SPX futures rose above the 100-day Moving Average at 4546.00 to a peak near 4550.00, its 61.8% Fibonacci retracement value.  Today’s expiring options become positive above 4525.00 and gamma turns positive at 4550.00.  Based on the layout of today’s expiring options, SPX may remain flat to lower to minimize the payout (Max Pain).  In addition, there is pressure to put a positive spin on the markets through the end of the quarter.  Today is day 252 of the current Master Cycle, so there is room to go sideways or higher.  However, the turn may take investors by surprise.  Be prepared.

ZeroHedge reports, “After initially sliding lower, US equity futures reversed and erased earlier declines, climbing 0.2% along with Nasdaq futures as Stoxx Europe 600 extends gains to 1.1%, a move that found added inertia after Tesla, one of the world’s biggest companies, soared 6% after hinting it too would pursue a stock split weeks after Amazon did the same. Most Asian shares lost ground earlier, with Chinese stocks falling as a virus flareup led to a lockdown in financial hub Shanghai, and raised worries over fresh supply chain disruptions while even higher yields led to growing recession fears. Cryptocurrency-exposed stocks gains as Bitcoin turned positive for 2022; gold and oil retreated.”


VIX futures surged to 22.19 over the weekend before pulling back, still above the mid- Cycle support at 20.99.  It is normally the mid-Cycle support/resistance that gives the locus for the turn in Wave two.  In addition, Friday was day 269.00 of the Master Cycle and the final Wave structure now appears complete.

ZeroHedge warns, ““They Turned the Machines Back On” shouted the man on CNBC. When you are in the middle of a significant secular shift in investor psychology one of historic proportions, there will always be those moments where market participants still believe “the dream is still alive.” It’s NOT today, “it´s still yesterday” is the thinking.

The “buy the dip” crowd rushes back into a short covering bonanza and stocks make an extremely unhealthy vertical move higher. That is NOT how real bottoms are formed. Think of Apple – AAPL equity just experienced its largest 9 day move higher in at least ten years up close to 17%. With the S&P 500 up nearly 10% in nine days we file this under Q2 2000 action .

The index closed at 4543 on Friday – right on the ominous 61.8% retracement of the recent decline. With HEAVY resistance at 4600 and wheel barrels full of supply – the “get me even and get me out” crowd is lurking.”


TNX may be taking a rest after a 48.8% rally in the month of March!  The Cycles Model suggests a 1-2 week retracement, most likely to test the Cycle Top at 21.54 before moving higher in strength to the week after options expiration.

ZeroHedge comments, “Plus Ça Change

A strong economy, high inflation, and then an oil price shock…even if history does not repeat itself, it may rhyme. While we do not think the 1970s provide the map for the road ahead, it is always worth taking stock of the lessons of the past. The orthodoxy of monetary policy will be tested with the Russian invasion of Ukraine and the stagflationary shock. Let’s consider the implications for the Fed and the ECB.

After the inflation of the 1970s had been tamed, the views of central bankers in developed markets on commodity price shocks evolved. Inflation expectations became anchored near – indeed at times below –target inflation rates, and the received wisdom was that either cost shocks should be ignored, because the inflationary effects would be transitory, or that policy should ease, because the drag on the real economy was a bigger threat. That stance became the textbook response. Will central banks now throw the textbook out of the window?”


USD futures have risen to 99.32 as it makes its last probe toward 100.00.  Today is day 264 in the Master Cycle, so once the prior high is exceeded, one must prepare for an imminent reversal.

ZeroHedge observes, “Update(9:01ET): Russia on Monday has issued a firm and unyielding response to G-7 ministers who had dismissed as “unacceptable” its plan to only accept ruble payments for Russian gas going to “unfriendly” nations.

Earlier Monday German Economy Minister Robert Habeck said from Berlin that the Kremlin demand for natural gas contracts to be paid in rubles is a “one-sided and clear breach of contracts” – saying the contracts must be honored under prior conditions, according to Bloomberg. “That means that a payment in rubles is not acceptable and we urge the relevant companies not to comply with Putin’s demand,” Habeck said. “Putin’s effort to drive a wedge between us is obvious but you can see that we won’t allow ourselves to be divided and the answer from the G-7 is clear: the contracts will be honored.”

The Kremlin’s quick shooting down of the German economy minister’s comments and the G-7’s stance on the ruble came Monday via a Russian lawmaker to state-run RIA Novosti: “Russian lawmaker Abramov says G7’s refusal to pay in Russian roubles for gas will definitely lead to a halt in supplies.”


West Texas Crude made a low this morning of 106.42 as it moved away from Thursday’s Master Cycle high.  The supports to watch are the Cycle Top support at 104.88 and the Broadening Wedge trendline and Intermediate-term support at 101.27.  A cross beneath either  may bring a sell signal with a decline stretching to the April options expiration, or shortly thereafter.

ZeroHedge observes, “After Friday’s oil price surge, catalyzed by a Houthi attack on Saudi Aramco oil facilities in Jeddah, on Monday oil retreated as China’s worsening virus resurgence raised concerns about demand in the world’s biggest crude importer, while rebels in Yemen announced a three-day temporary pause in hostilities against Saudi Arabia.

WTI and Brent futures fell more than 4% each after authorities in Shanghai said they will lock down half of the city in turns for mass Covid-19 testing. Growth risks from inflation and tightening monetary policy also hit sentiments, pushing down sovereign bonds and equity markets were mixed.”


Gold futures declined to 1924.60, crossing beneath the Cycle Top support and giving a potential sell signal.  The Cycles Model suggest s decline to the week of April 25 in the current Master Cycle.  The target may be mid-Cycle support at 1819.73 or the trendline near 1810.00.

OilPrice.com advises, “The latest round of sanctions imposed on Moscow by the West is drawing some mixed reactions from experts.

  • The U.S. announcement to block gold transactions was done alongside Group of Seven and European Union allies that will also impose the gold reserve ban.
  • “Any sanctions on Russia’s gold reserves would do little more than reveal the degree to which government bureaucrats don’t understand gold.”

Following Russia’s invasion of Ukraine about a month ago, the U.S. and its western allies swiftly imposed a raft of economic and trade sanctions on Russia, notably on buying oil, a partial SWIFT ban and against billionaire oligarchs seen as close to President Vladimir Putin. Russia hit back by imposing export bans including telecoms, medical, vehicle, agricultural, and electrical equipment, as well as some forestry products such as timber.

But it’s the latest round of sanctions that has been drawing mixed reactions across the board: the U.S. ban on gold transactions with Russia.”

 

Posted in Published | 125 Comments

March 25, 2022

7:45 am

Good Morning!

I am off to an early start as I am going steelhead fishing with my son and grandson on the Pere Marquette river.  The fish are running in high water and we expect snow over the weekend.  Not my idea of a sunny spring break.

SPX futures are challenging the 100-day Moving Average at 4537.36 on day 49 of the Master Cycle.  SPX has retraced 60% of the decline on day 29 from the February 24 Master Cycle low.  The 61.8% Fibonacci retracement lies at 4550.00.

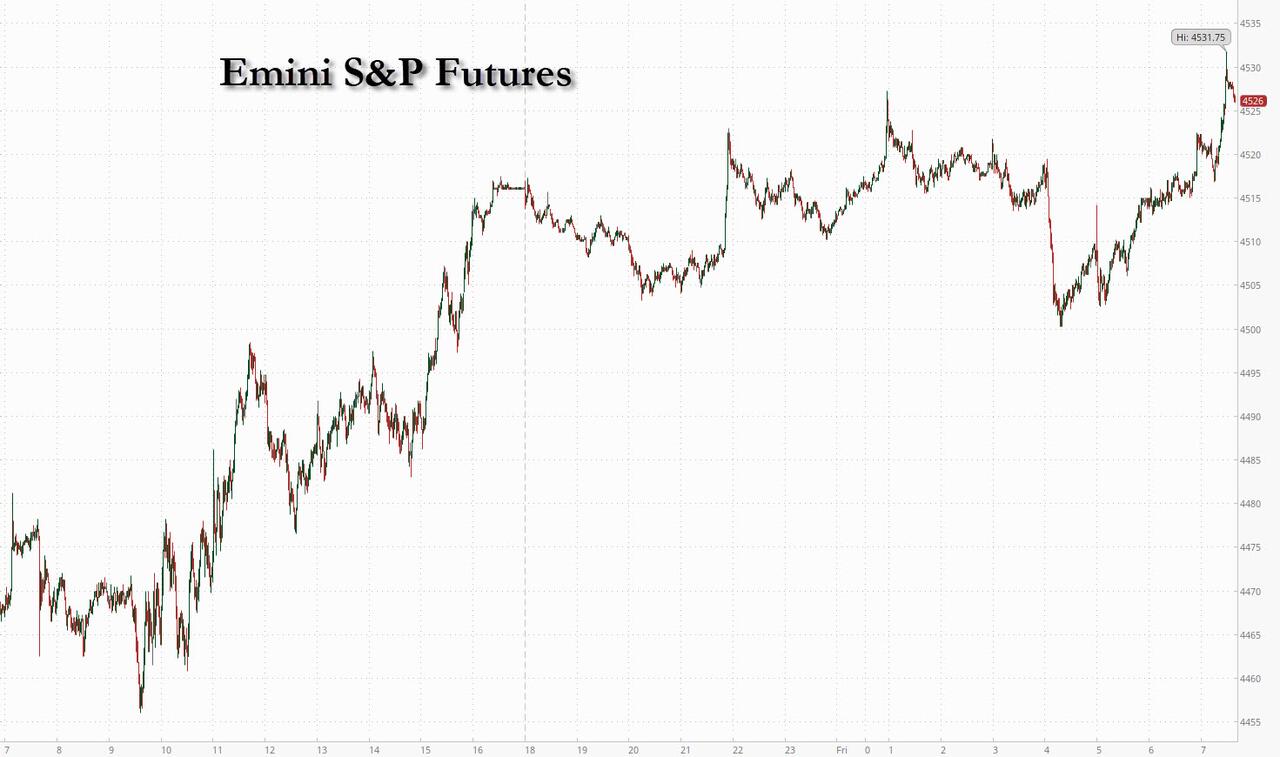
ZeroHedge reports, “After a jerky, stop and go session that saw several sharp moves in both directions only to reverse into a relatively narrow trend, S&P futures were near session highs, up 0.3% or 14 points to 4,526 around the time US traders got to their desks as investors evaluated economic risks from Federal Reserve monetary-policy tightening and Russia’s war in Ukraine. Sentiment was boosted by WTI crude futures sliding 1.6% as the EU continues to make plans to reduce its dependence on Russia. Asia stocks were mixed, with losses led by Hang Seng which closed down 2.5%, while Europe’s Stoxx Europe 600 index rose, led by the tech and real-estate sectors. President Joe Biden will travel to Poland for a visit focused on refugees as his European trip continues. The dollar dropped, bitcoin jumped near $45,000 while Treasuries were flat, remaining on course for one of their worst quarterly routs since at least the early 1970s.”


VIX futures are calm, despite the rising SPX.  Yesterday’s probable Master Cycle low was on day 268.  The structure that we see from the December 3 high is a triple zigzag which explains the jagged sideways performance of the VIX.  The mid-Cycle support at 20.96 may provide a floor for this correction.  Those of you trading the VIX may find this position to be ideal for accumulation.  Buy it when you can get it cheaply.


Posted in Published | 12 Comments

March 23, 2022

8:30 am

Good Morning!

SPX futures are challenging the mid-Cycle support at 4492.00 this morning, giving the first hint of a reversal.  The mid-Cycle line offers an aggressive sell signal.  Today’s expiring options are positive above 4475.00 and turn negative beneath 4435.00, so there is a very narrow range of neutrality that may be kept through today’s close.  It does, however, indicate room for a decline.  The 200-day Moving Average is at 4473.04 which, if crossed, may encourage short sellers.

ZeroHedge reports, “A torrid rally that pushed US stocks higher on 5 of the past 6 days appeared set to end, as US index futures drifted lower on Wednesday while bond markets stabilized from a historic rout driven by an increasingly hawkish tilt from the Federal Reserve took a breather after record losses. Contracts on the Nasdaq 100 were down 0.5% at 7:15 am in New York, while S&P 500 and Dow futures fell 0.4%; European bourses were also pressured sending the Euro Stoxx 50 -0.6%, with the exception of the FTSE 100 +0.4% amid crude action. Asia stocks closed higher, led by Nikkei 225’s 3% advance. The dollar rose to session highs amid hawkish Fed rhetoric and the USD/JPY continues to climb. Bonds bounce as risk wobbles and bulls pounce, but sellers remain prevalent; 10-year Treasury yield fell to about 2.37%, after hitting its highest since May 2019 on Tuesday and rising as high as 2.42% overnight.

After sliding to session lows, around 22.7 yesterday, the VIX has reversed the entire Tuesday move and was last seen just shy of 24.


VIX futures have risen to 24.00 this morning, short of the 50-day Moving Average at 26.74.  The number where analysts sit up and take notice may be 25.00, so we may  use that as an aggressive long entry.  Of course, the Master Cycle low was on day 266, which suggests the risk of a further bearish extension is minimal.


NDX futures appear to be rapidly declining, having hit a morning low of 14523.00 and still dropping.  The 50-day Moving Average is at 14444.47, where an aggressive sell signal lies.

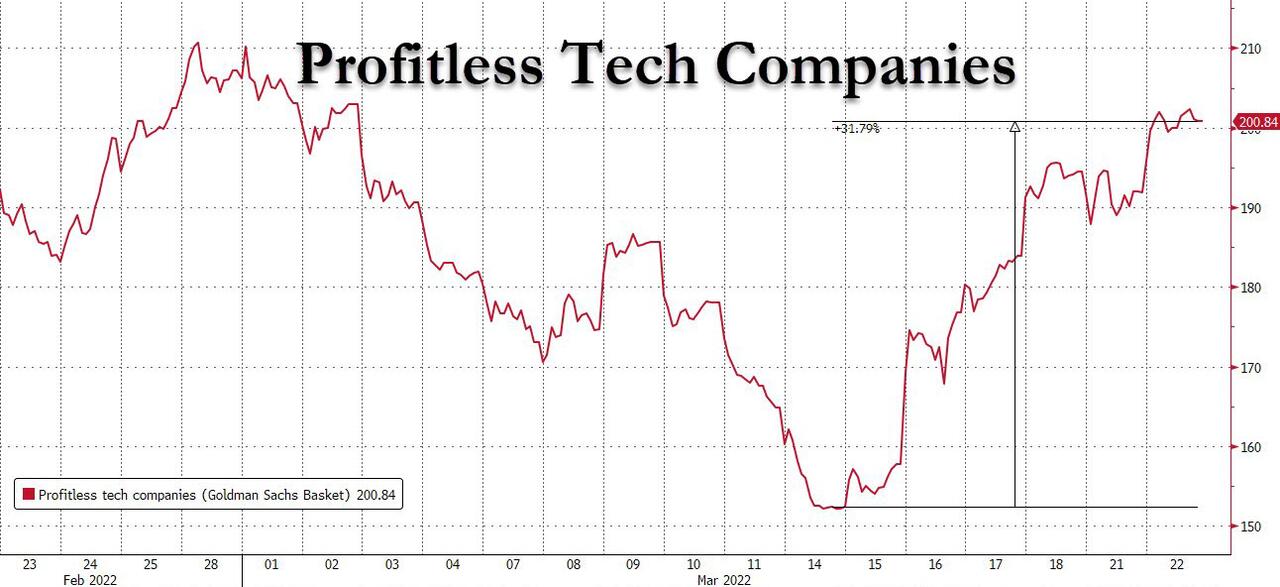
ZeroHedge exclaims, “Last week’s short-lived tech rally pushed some unprofitable tech stocks up nearly 50%. As remarkable as such a move is, strong temporary moves to the upside are nothing unusual in a market that is crashing. And “crash” is the best description of what some areas of the technology sector are going through.

Tech stocks, as measured by NASDAQ, peaked on November 19, 2021. However, if we look at the subset of unprofitable growth stocks, former unicorns that have seen tremendous growth in their stock prices in recent years or former SPACs, then the peak in many of these stocks occurred a few months earlier shortly after the meme stock mania. Chinese tech stocks, in turn, peaked in late 2020 as the Chinese government clampdown on tech companies began.”


The rally in TNX is taking a pause, as anticipated by the EW structure.  The Cycles Model suggests a correction may be underway for the next two weeks.  A pullback to the Cycle Top support at 20.98 is possible.

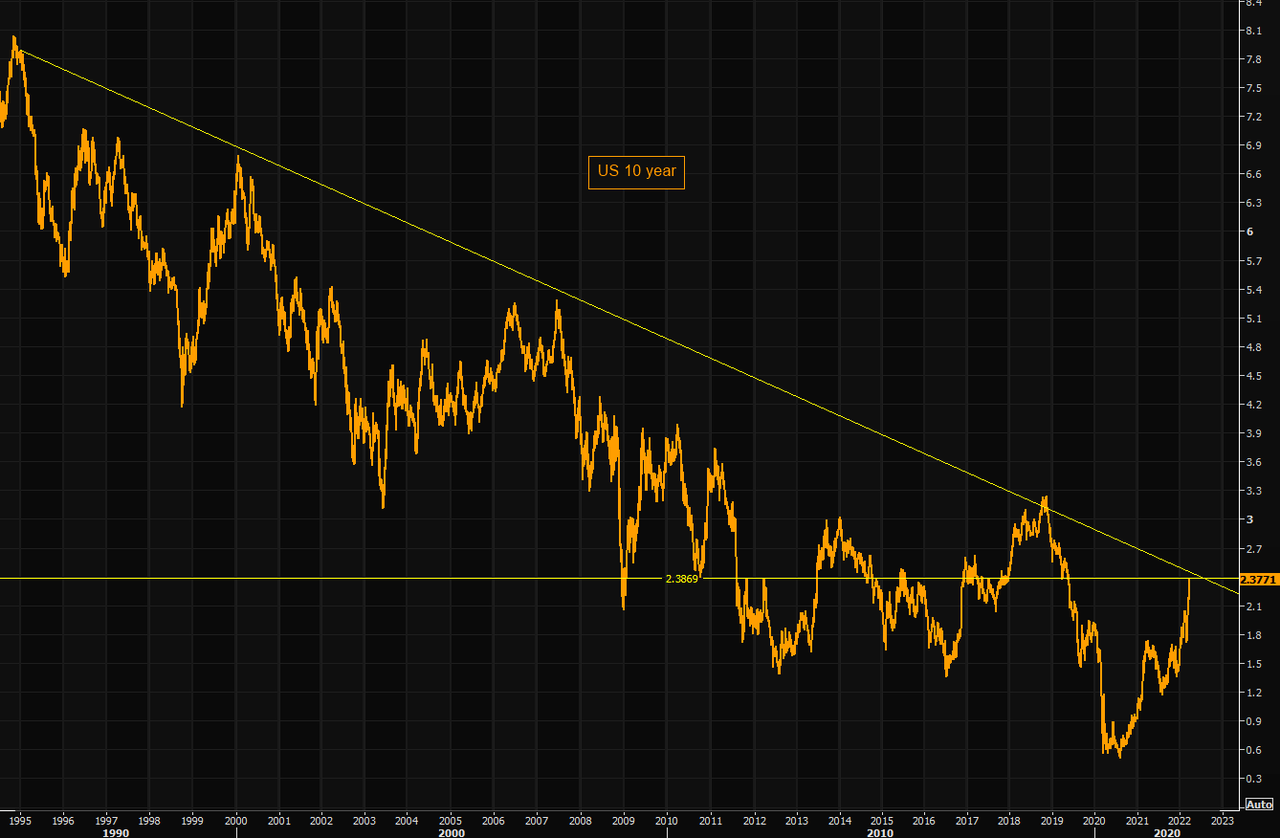
ZeroHedge remarks, “US 10 year – the long term view

The US 10 year yield is approaching huge levels. This needs to pause, or…

Source: Refinitiv

US 10 year – the perfect trend channel

Us 10 year continues trading inside the big (and perfect) trend channel. Rising yields has become very consensus lately…


USD futures have risen back above the Cycle To support/resistance at 98.53 this morning.  Today is day 259 of the old Master Cycle, which may be modified to show a top near 100.00, should it rally into the end of the week.


WTI futures have rallied to an overnight high of 113.88.  however, I have been warning since Monday that it is at its Master Cycle end.  Today is day 260.  Should the reversal occur today, there may be three weeks of decline.  The mid-Cycle support is the normal target.  However, should a liquidity crisis occur, the decline may test the bottom of the Broadening Wedge formation or possibly the Cycle bottom at 56.26, near the 61.8% retracement point.

ZeroHedge warns, “While the world has been obsessively focused on crude oil and gasoline in recent weeks, we instead alerted readers to a far more dire scenario playing out in diesel, a source of energy which is absolutely critical in keeping the “just in time” world running on time.

As a reminder, here are some of the articles we have published on the topic in recent weeks, many even before the Ukraine war:

Fast-forward to today, when our warning was echoed by the heads of one of the largest commodity trading houses and the biggest independent oil trader who were speaking at the FT Commodities Global Summit in Lausanne, Switzerland on Tuesday.”


Posted in Published | 1 Comment

March 22, 2022

2:57 pm

Today is day 246 of the current Master Cycle.  This may be an early Master Cycle top for three reasons; First, the VIX has made a Master Cycle low today and the NYSE Hi-Lo Index (a leading indicator) has made a Master Cycle high yesterday.  Second, the Wave (1) decline took 51 (51.6)days while the rally took 26 days (25.8), leaving a 56.7% retracement.  Finally, the mid-Cycle resistance at 4492.00 is a common resistance for a Wave (2).

RealInvestmentAdvice is a bit befuddled by it all.  Looking ahead, should this be the top, the next Master Cycle decline may also take 50+ days, indicating a potential bottom during the third week of May.


2:25 pm

The Ag Index is in a correction phase that may have a few days left to go to a probable Master Cycle low.  There is still a likelihood that he correction may extend down to Intermediate term support at 518.12 by the end of the week or early next week.  The most powerful advance is yet to be made.

Michael Snyder at ZeroHedge comments, “Food prices in the U.S. have already been soaring, and now we are on track for an absolutely horrible winter wheat harvest.  Of course this comes at a time when the war on the other side of the globe is going to greatly reduce wheat exports from Russia and Ukraine.  Over the last 12 months, the price of wheat has already risen 69 percent, and now this crisis threatens to go to an entirely new level.  In all my years of writing, I have never seen anything like this, and I am deeply concerned about what the months ahead will bring.”

To make matters worse, strikes are hobbling the transportation system.  ZeroHedge observes, “The North American agricultural sector could be in for a major shock if Canadian Pacific Railway Ltd’s (CP Rail) work stoppage is not resolved in a timely manner because it could spark a shortage of fertilizer and other shipments critical for the spring growing season, according to AP News.

AP News reports more than 3,000 CP Rail conductors, engineers, train, and yard workers represented by the Teamsters Canada Rail Conference stepped off the job Sunday as the union and CP Rail couldn’t strike a deal.”

Just when things cannot get worse, they will.  ZeroHedge reports, “Everyone needs to start paying attention to this crisis, because America’s rapidly growing bird flu pandemic is going to deeply affect all of us at the grocery store.  This pandemic began on February 8th when a confirmed case of HPAI was confirmed in a domestic flock, and on March 9th I published an article that discussed the fact that nearly 2.8 million birds (mostly chickens and turkeys) had already died.  If the pandemic had fizzled out after that first month, it wouldn’t have ultimately been a major deal.  But instead, this pandemic has escalated dramatically here in the second month.  If cases continue to spread like wildfire, we will soon be facing a nightmare of absolutely epic proportions.”


7:45 am

The Shanghai Composite Index has stalled beneath the Lip of the Cup with Handle formation.  SSEC has been on a sideways consolidation from 2015 until the breakdown in March.  It and the NDX have similar characteristics due to the overweight of technology.

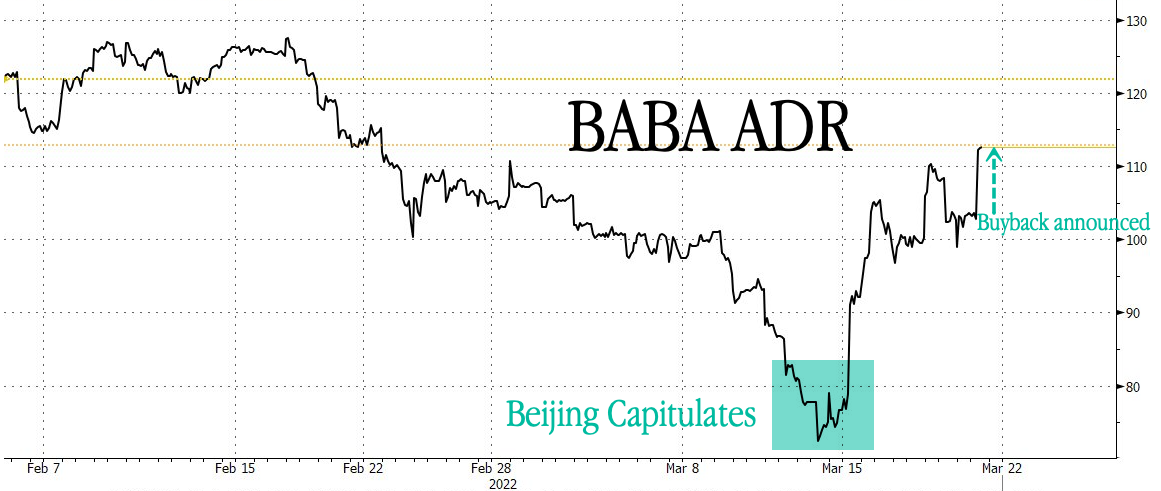
ZeroHedge reports, “Nearly a week after China’s top financial policy body vowed to ensure stability in equity markets and support oversea stock listings, more fuel was added to the rally on Tuesday when Alibaba Group upsized its share buyback program to $25 billion from $15 billion, sending Alibaba shares in Hong Kong as much as 5.4% higher. The move indicates a multi-year crackdown on technology companies by Beijing is waning.

Shares of Chinese-listed stocks in the US were lifted as well. Alibaba jumped 8.9%, Baidu +4.8%, JD.com +5.5%, Pinduoduo +5.9%, ride-hailing giant Didi +5.8%. ”


NDX futures are hitting resistance at the 50-day Moving Average at 14465.08.  It has also made a 38.2% Fibonacci retracement of its decline from its November peak.  The peak to (today’s) peak elapsed time is 120 days.  The next 60 days may be the most intense decline seen in a lifetime.

The conflict in Ukraine is having a strong effect on technology since the Ukraine provides many components for the microchip and EV industry.  The green revolution is about to implode.

ZeroHedge reports, “Tesla has hiked the price for its large-scale rechargeable lithium-ion battery product, otherwise known as the “Tesla Megapack,” following a massive jump in industrial metal prices due to the Russian invasion of Ukraine.

EV website Electrek reports the price of the Megapack jumped nearly 24.5% since last year. In 2021, a single Megapack was priced around $1.2 million. Now the price is much higher, starting at $1,537,910.”


SPX futures have been bumping against the mid-Cycle resistance at 4480.78, a common stopping place for Waves twos.  Wave (3) may take up to 60 days and may offer an unprecedented intensity to its decline.  Be prepared for a sudden change in trend.

ZeroHedge reports, “US equity futures reversed earlier losses and European stock markets rose as a sharp rally in crude oil stalled, even as a selloff in bonds deepened Tuesday after Fed Chair Powell signaled a stronger commitment to clamp down on inflation.

Futures on the S&P 500 and Nasdaq 100 flipped to gains from losses, the former trading 0.3% higher or 14 points to 4,466 while the latter was 0.25% in the green. The Stoxx Europe 600 Index marched 0.4% higher, led by banks and cyclical stocks like automakers, while the Hang Seng led gains in Asia, closing up 3.15% after Ali Baba raised its stock buyback by $10 billion. Treasury yields continued their ascent after short-dated rates posted one of the biggest daily climbs of the past decade on Monday.”


VIX futures made a low at 23.16 this morning after yesterday’s Master cycle low at 22.99.  This is a great time to accumulate the VIX ETFs and options.

SeekingAlpha explains, “Volatility-based ETFs and ETNs subside once again in early market trading as the S&P 500 VIX Index (VIX) dropped down to the 23 handle, after it touched 37.8 the day Russia attacked Ukraine. Additionally, the index now sits right on top of its 100-day moving average.

As volatility in the market subsides, investors are approaching the financial space with more of a risk-on approach, forcing specific volatility funds to decline.”


TNX appears to have completed a Minute Wave [i] in its journey to its Cup with handle target.  It may consolidate to its cycle Top support at 20.79 before resuming its upward trajectory.  The Cycles Model suggest another five weeks of rally ahead before a more severe correction.

ZeroHedge notes, “As the Russian invasion into Ukraine continues into its 3rd week, despite the world’s hopes for resolution, uncertainty continues to grow.

  • What will the geopolitical situation look like after a cease-fire is declared? (IF one is declared)
  • How badly will the trade disruptions with Russia worsen inflation, given Russia’s role as a top exporter for many key commodities?
  • Are we weakening the US dollar’s role as the global reserve currency by giving other nations cause to accelerate their efforts to de-dollarize?

Meanwhile, the cost of capital is increasing as interest rates are on the rise — right as we anticipate the Federal Reserve will kick off a new era of Quantitative Tightening at its meeting this week.

Are a further correction in the markets and possibly a recession now more likely as a result?

Money manager Peter Boockvar concludes “yes”.


Posted in Published | Comments Off on March 22, 2022

March 21, 2022

10:00 am

SPX may have peaked with a 17.2 market day rally from the February 24 low.  I had mentioned on Friday that it was day 17, but did not know whether it would extend to the full Cyclical complement of days.  It has.  The Cycles Model suggests a Master Cycle low the week of April 4.  A decline beneath the 50-day Moving Average at 4438.29 confirms the decline.

ZeroHedge comments, “Atlanta Fed President Raphael Bostic stirred the hawkish pot hard this morning with some more aggressive comments on QT (and rate-hikes).

“I penciled in six rate hikes for 2022 and two more for 2023,” Bostic said in a speech Monday to a National Association for Business Economics conference in Washington.

“I recognize that I am toward the bottom of the distribution relative to my colleagues, but the elevated levels of uncertainty are front forward in my mind and have tempered my confidence that an extremely aggressive rate path is appropriate today.”

Bostic may be hoping for that but the market sees 7 more hikes this year and 2 RATE CUTS in 2023/2024.

Bostic said he considered inflation as the top concern for policy makers this year and described the U.S. labor market as tight.


9:50 am

The Ag Index may have resumed its ascent after a short consolidation.  If so , it may have another 2-3 weeks of rally to meet its next Master Cycle high.  It has met is mid-Cycle support, currently at 542.96which is the normal retracement for Wave (2).  At the same time, it retracement has been shallow and liquidity is still an issue.  The only way that we will know that the trend is reestablished is a breakout above the March 8 high.

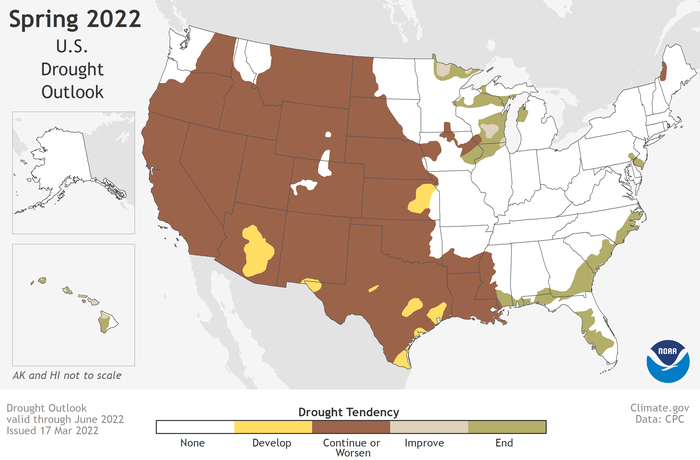
ZeroHedge reports, “Abnormally dry to exceptional drought conditions are expected to persist across 60% of the continental U.S. as spring in the Northern Hemisphere begins. Forecasters expect little to no rain for certain parts of the western U.S. through June.

From April to June, above-average temperatures are expected from Southwest to the East Coast and north through the Midwest, according to a new outlook published by the National Oceanic and Atmospheric Administration (NOAA).

NOAA’s map shows a greater than 50% chance of drought persistence for nearly 60% of the continental U.S.

“Severe to exceptional drought has persisted in some areas of the West since the summer of 2020, and drought has expanded to the southern Plains and Lower Mississippi Valley,” said Jon Gottschalck, chief, Operational Prediction Branch, NOAA’s Climate Prediction Center.”


8:00 am

Good Morning!

SPX futures dipped to a weekend low of 4440.40 before rising back to breakeven.  By Friday’s close it had reached the 200-day Moving Average at 4470.46.  Not surprisingly, it had closed very near to its Max Pain zone at 4480.00.  Today’s expiring options go long at 4450.00 and short at 4400.00.  SPX no longer has short gamma chasing its tail, but there may be some serious unwinding of longs by dealers and hedge funds making a market in options should it decline beneath 4400.00 today.  Should Friday’s high be the swing high, we may see two weeks of decline into the first week of April, the next Master Cycle pivot.

ZeroHedge reports, “U.S. equity futures and European bourses stocks reversed modest overnight losses and turned higher as US traders got to their desks on Monday as crude oil extended a climb and investors monitored diplomatic efforts to bring an end to Russia’s almost month-old war in Ukraine.  S&P futures rose 0.07% or 3 points after earlier sliding almost 30 points; Nasdaq futures were flat.

Focus on Monday will be on a speech by Fed Chair Jerome Powell after the central bank kicked off a rate-hiking cycle last week.  Powell is set to speak at the annual meeting of the National Association for Business Economics at 12pm ET; text release and Q&A are expected.”


VIX futures rose to a weekend high of 24.98, just under the bottom trendline at 25.00.  It may have completed its Master cycle low on Friday, day 262.  A rise above the trendline may give us an aggressive buy with the 50-day Moving Average at 26.58 offering confirmation.

ZeroHedge comments, “VVIX knew (again)

VVIX has been in “denial” for some time and has refused getting excited about the last VIX attempts to move higher in early March. Both have fallen hard during the latest squeeze, but note that VVIX closed at lowest levels since early November. There is obviously more to it, but last time VVIX was here, the VIX was substantially lower. We are not calling for VIX to reach those levels, but the gap between the two indexes remains very wide.

Source: Refinitiv

Sentiment and VIX

Imagine the pain should we decide moving higher from the lower band of this chart…


TNX rose with strength this morning, but did not break out.  The Cycles Model offers little direction for the next two weeks, so we may see TNX drift or go lower with the Cycle Top acting as near-term support.  The Cycles Model indicates a Master Cycle (high) in the third week of April.

ZeroHedge comments, “Bill Gross, the PIMCO founder and longtime “Bond King” of Wall Street, has likely grown accustomed to critical portrayals in the press, following his widely publicized dispute with a Laguna Beach neighbor (Gross published his own account of the aftermath which is definitely worth a read for the entertainment value alone), and after the recent publication of a book called “The Bond King” – which prompted him to pen his own memoirs to counteract what he feared would be a negative portrayal. Now comfortably ensconced in retirement, the PIMCO founder has taken a break from managing his own portfolio (which has recently included winning options bets against GME and AMC) to share his concerns about the Fed’s rate-hike plans with the FT‘s top business editor.

Bill Gross

Gross fears that if the Fed follows throuogh with its plans to hike rates by 25 basis points at each successive meeting this year, it will “crack” the US economy and the housing market, sending the US careening into a recession.

As we shared on Wednesday, the Fed’s median projection as expressed in the latest “dot plot” shows 7 rate hikes in 2022, which would leave the Fed funds rate, the central bank’s benchmark interest rate, at a peak of 2.75%.

Raising the benchmark rate to this terminal level would cause the US economy to “crack”, Gross said, causing a recession and “breaking” the housing market (which has been caught in a torrid buying frenzy).

“I suspect you can’t get above 2.5 to 3 per cent before you crack the economy again,” he said. “We’ve just gotten used to lower and lower rates and anything much higher will break the housing market.”


USD futures have been consolidating beneath the Cycle Top resistance at 99.42, leaving Thursday’s low at 97.72 as the possible Master Cycle low on day 253.  A breakout above the Cycle Top resistance gives us a final buy signal with USD target near 100.55.  The next Master Cycle (high) may occur near mid-April.


Crude oil futures rose to a weekend high of 107.50 on day 258 of its Master Cycle.  It is primed for a reversal that may not find a bottom until mid-April.

OilPrice.com observes, ”

  • WoodMackenzie: European gas storage levels will likely be within the five-year range by the end of this winter.
  • If Russian flows continue, the European Union (EU) and the UK will end this winter’s heating season with 27 billion cubic meters (bcm) of gas in storage.
  • Increasing imports from Norway, Algeria and LNG may help to compensate lower gas flows from Russia.

Europe Can Survive Throughout Summer Without Russian Gas

If Russian gas flows to Europe were interrupted now, Europe would have enough gas to last it through the end of this winter and the following summer without having to curtail demand, energy consultancy Wood Mackenzie said on Friday.”


Gold futures have been hovering near the Cycle Top resistance at 1925.41.  The correction may have run its course.  The Cycles Model suggests trending strength returning later this week wit the next Master Cycle (high) anticipated in the last week of April.  Gold is an indicator of political turmoil and mistrust of governments.


Posted in Published | 2 Comments