April 22,2022

3:50 pm

SPX continues its decline.  This is not a time to take profits yet.  The next bounce may be at the trendline at 4100.00.


7:40 am

Good Morning!

NDX futures probed lower in the overnight session, to a low of 13611.80.  The 50-day Moving Average at 14257.32 proved to be resistance at yesterday’s high and now the Cycle Bottom at 13518.32 may be the next support.

Today’s expiring options show two heavy concentrations of calls at 13700.00 and 13800.00.  Puts are very concentrated (short gamma) at 13500.00.  QQQ (334.15 close) expiring options are negative beneath 340.00 and short gamma starts at 335.00.

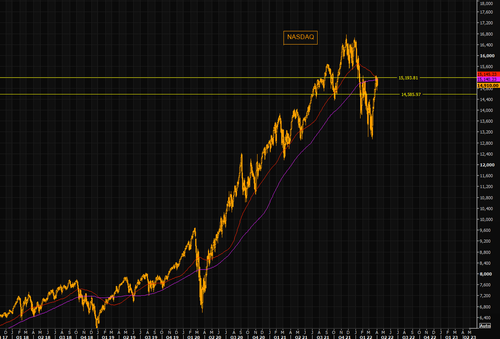
ZeroHedge notes, “NASDAQ – the cross of crosses

Time to revisit the “cross of crosses”, the 100 vs 200 day moving average cross, that occurred right at the most recent NASDAQ resistance. With NASDAQ falling below the big 14k level today, this moving average cross is becoming “serious”. Supports are: 13.6k and the 13.2k level.

Source: Refinitiv

Tech stress refuses easing

VXN is back to recent highs, while VIX remains 2 points below those highs. Tech remains the pillar of this market…and price action is all but bullish.


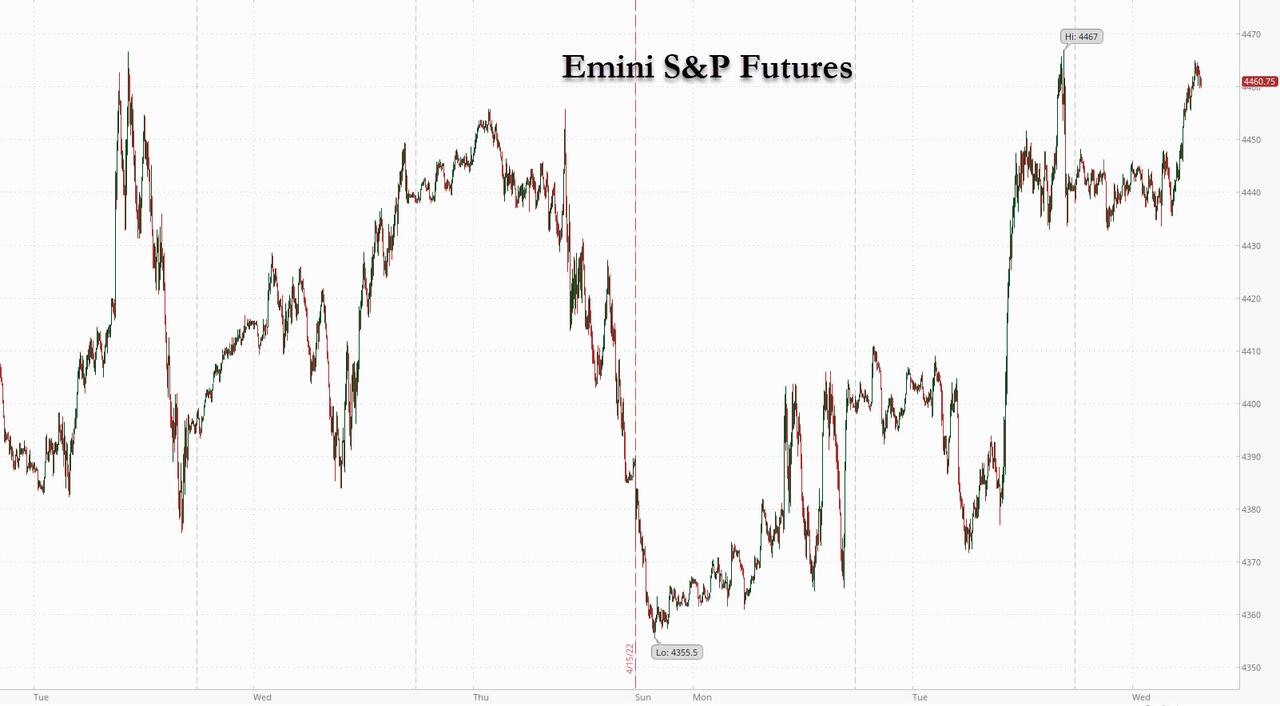
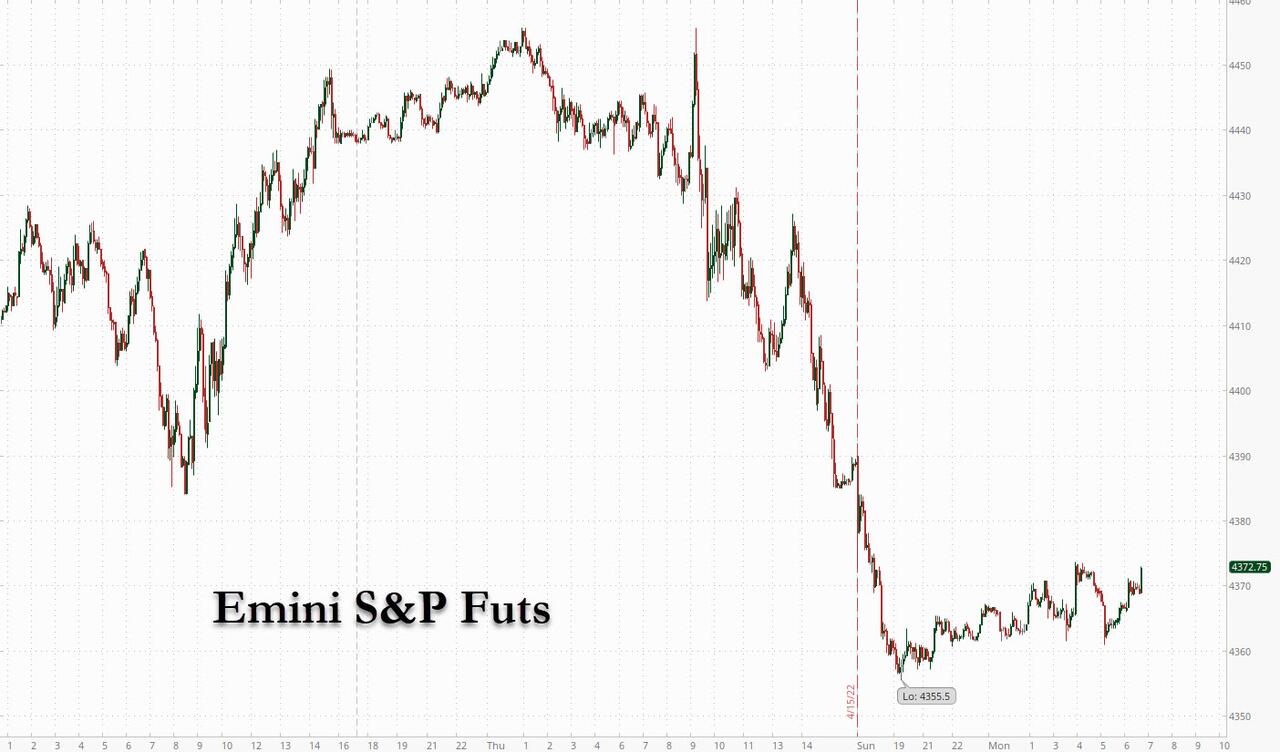
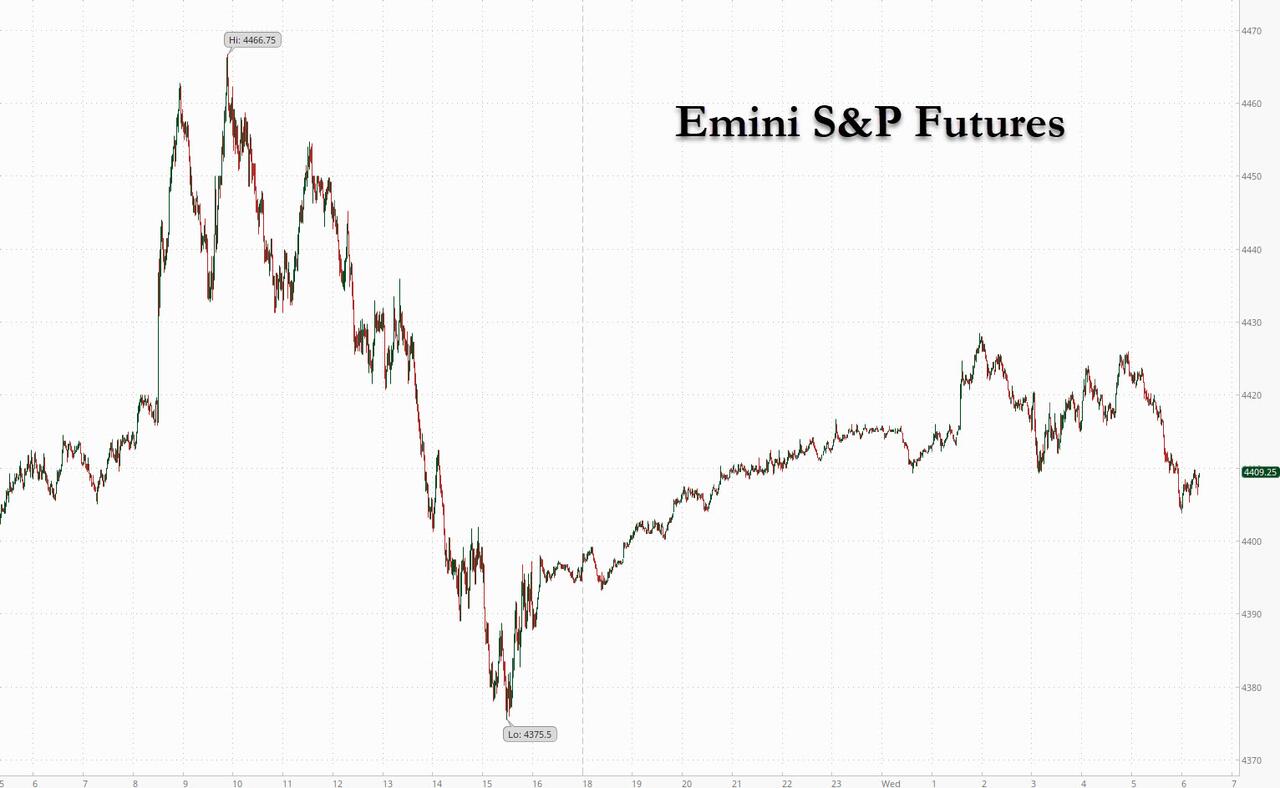
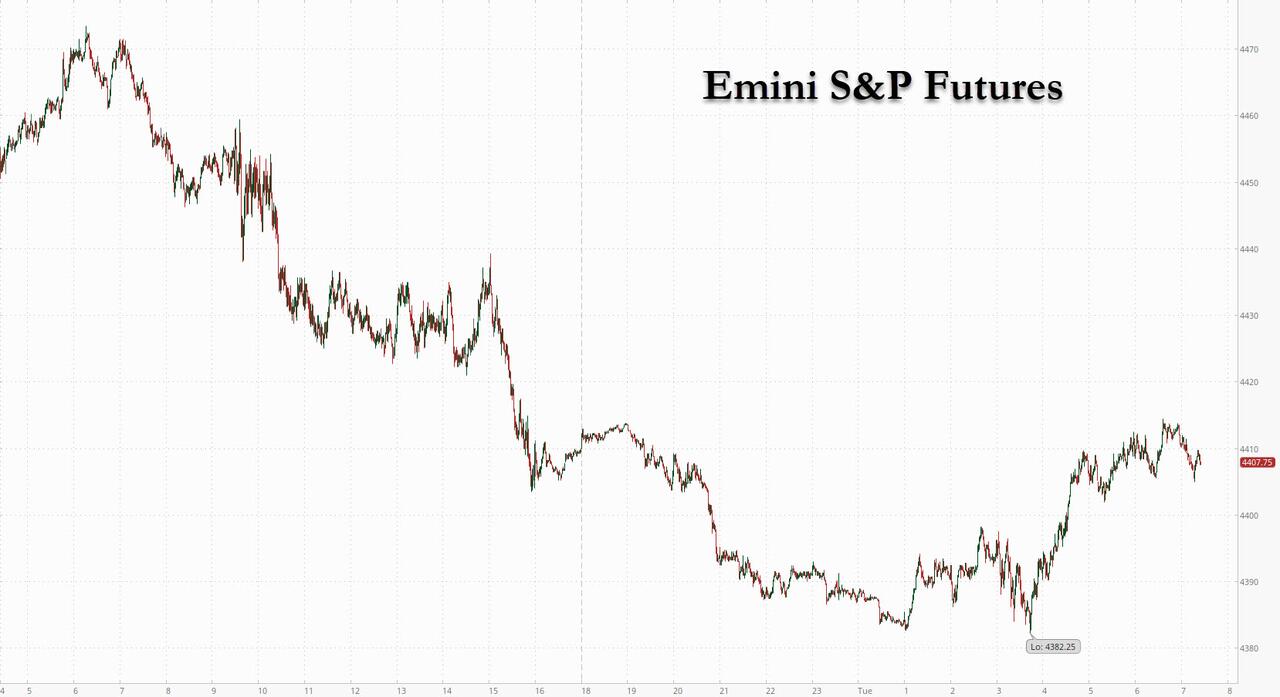
SPX futures declined to 4366.10 overnight and bounced, but remained beneath 4400.00.  Max Pain is at 4420.00 and short gamma may exist beneath 4400.00.  This is not a good combination and may lead to elevated volatility today.

Zerohedge reports, “US equity futures extended their Thursday losses, and were slightly lower on Friday morning as investors fretted over the latest hawkish remarks from Jerome “Crash Stonks” Powell. Nasdaq 100 futs were down 0.1% by at 7:15a.m. EDT after the underlying gauge slumped 2% on Thursday after Powell outlined his most aggressive approach yet to taming inflation, potentially endorsing two or more half percentage-point interest-rate increases, which prompted the market to price in more than six 25bps rate hike by the end of July and 10 hikes by the end of 2022. Shorter-dated Treasury yields surged. The dollar rose to the highest level since July 2020 amid losses for the British pound with data showing the U.K.’s cost-of-living crisis is hampering consumer spending.

The overnight weakness pushed both S&P 500 futures lower by about 0.2% after cash closed down 1.5% Thursday, although trade was muted and range-bound.


VIX futures climbed to an new high at 23.62, then pulled back to a low of 22.62.  VIX is on a buy signal and, should yesterday’s low be the final low, sets up a new Master Cycle lasting up to three months.  This has the appearance of being a monster Cycle.


TNX futures hit a new Master Cycle high at 29.74, although not registered (yet) in the cash market.  Today is day 261 in the Master Cycle and there is room for further gains, possibly through the next week.  Trending strength may not be over, yet.


USD futures hit a new high at 101.10 this morning, on day 266 of the Master Cycle.  Ordinarily one would expect the USD to reverse its trend here.  However, this may be the last gasp for the USD.  In addition, the strength of the USD is still linked to the TNX.  When TNX  declines, so will the USD.


Crude oil futures declined beneath the 50-day Moving Average at 101.50 before a bounce brought it back above it.  This portends a serious loss of support that may result in a further decline.  The Cycles Model suggests a decline may go through the end of June.  In Wave relationships, Wave (C) is often equal to Wave (A), and sometimes greater than (A).  That implies a decline to the lower trendline of the Broadening Wedge at 70.00.  Should it go lower, an extended relationship may take WTIC to 50.00.

ZeroHedge observes, “A full EU ban on Russian crude oil and gas imports could have unintended economic consequences for the United States and its Western allies, U.S. Treasury Secretary Janet Yellen told reporters in Washington on Thursday. The Treasury Secretary added that such a ban could do more harm than good.

Europe does need to reduce its dependence on Russian oil and gas, Yellen said, “but we need to be careful when we think about a complete European ban on, say, oil imports.”


Posted in Published | 1 Comment

April 21, 2022

7:45 am

Good Morning!

SPX futures rose to a morning high at 4501.20, just beneath the mid-Cycle resistance at 4507.80 and the 50% retracement values at 4509.50.  Friday’s options expiration shows Max Pain at 4450.00, near yesterday’s close.  Options gamma turns positive near 4500.00.   Should SPX break above resistance, the 61.8% retracement value is 4439.56.  It is no coincidence that opex closes at or near Max Pain.  This is one of wall Street’s biggest money makers and also the source of greatest risk when the markets break down.

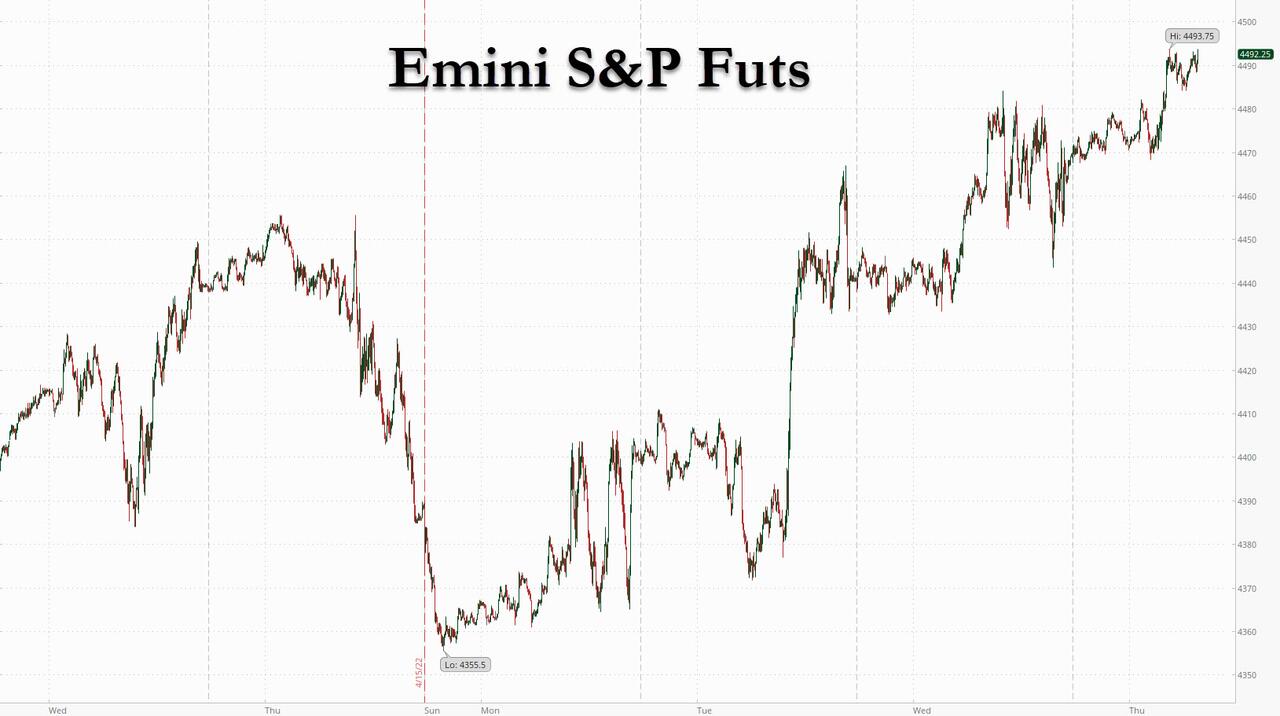
ZeroHedge reports, “US equity futures traded higher led by tech stocks, after Tesla’s results beat expectations boosting hopes for another strong earnings season and allayed fears of an imminent recession. The electric-vehicle maker’s shares jumped 7.2% in premarket trading on Thursday, while United Airlines rose 7% after forecasting it will return to profit this year. By contrast, Alcoa dropped 5.7% after reporting worse-than-expected sales and higher inventories due to supply-chain disruptions. S&P futures rose 0.85% or 37 points to 4,493 while Nasdaq 100 futs rose 1.2% to 14,175. A selloff in Treasuries resumed with a debate raging around whether inflation is peaking: the 10-year Treasury yield added 4 basis points. The euro and German bund yields rose after hawkish comments from European Central Bank officials. The dollar reversed losses, gold slumped to session lows and bitcoin jumped above $42,000.


VIX futures declined to a morning low of 19.81 on day 251 of the Master Cycle.  There is a risk of a new Master Cycle low in the next two days.  Should that be the case, this may launch the VIX into a possible 90-day surge to new (possibly all-time) highs.   I have detected a probable new pattern that may better accommodate what is transpiring.

Max Pain on next Wednesday’s options expiration is at 19.00.  Positive gamma kicks in at 21.00.  This comports with the Cycles Model which offers a buy signal above mid-Cycle resistance at 21.30.


TNX continues to consolidate beneath Tuesday’s Master Cycle top at 29.30.  Should that high persist, we may see TNX decline through the end of May.

ZeroHedge reports, “With yields tumbling all day after the 10Y seemingly peaked just south of 3.0%, many expected that today’s 20Y reopening (of 19Y-10M cusip TF5) would be a tail due to the lack of concession. Well, they were wrong, because moments ago the Treasury announced that it sold $16BN in 20Y paper at a high yield of 3.095%, which while almost 150bps higher compared to the March high yield of 2.651%, stopped through the When Issued 3.125% by 3.0bps, the biggest strop through in the (brief) history of the 20Y auction.

The bid to cover jumped to 2.80, up from 2.72 in March, and also a record high.

The internals were also record, with Indirects taking down a whopping 75.9%, up a whopping 11.5% from March’s 64.4%, and the most on record, not to mention well above the six-auction average of 63.9.%. And with Directs awarded 15.3%, modestly below the recent average, Dealers were leff holding just 8.7%, also the lowest on record!”


USD futures have declined beneath the Cycle Top support at 99.94, making a sell signal.  It as bounced back above the support, but the signal has been given.  Will consumers go on strike and weaken the USD?  The Cycles Model suggests a decline through the third week of June.

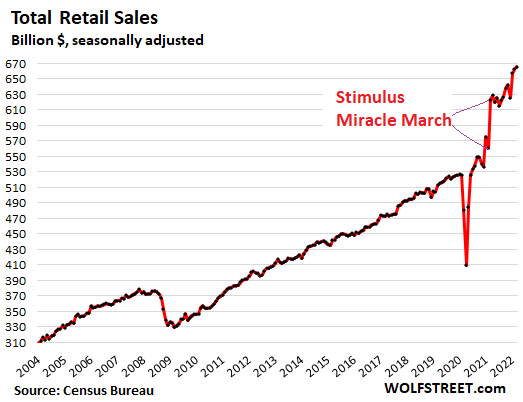
ZeroHedge reports, “American consumers are spending more, getting less, and borrowing more to fund this involuntary spending spree.

Retail sales in March were 7% higher than they were in the stimulus-fueled March of 2021, but thanks to inflation, they didn’t get as much bang for their buck.

Seasonally adjusted, retail sales were up 0.5% month-on-month in March at $677 billion.

As WolfStreet put it, “Stimulus Miracle March 2021 was a very tough month to beat. But Americans did blow by it. What they didn’t do is blow by the now raging inflation.”


Crude oil futures continue to consolidate beneath the trendline at 104.50.  Whatever is about to happen will last through the end of June, so be aware of a major firestorm looming.  The probable target appears to be near the trendline at 70.00.


Posted in Published | 2 Comments

April 20, 2022

9:47 am

The Ag Index continues to retest the neckline at 570.50 in preparation of another move higher.  Today is day 251 of the Master Cycle.  I am not looking for a turn yet, as there is an increase of trending strength due next week.

ZeroHedge reports, “About one-third of Ukraine’s farmlands may not be harvested or cultivated this year as Russia begins the second phase of the conflict in the war-torn country.

The Food and Agriculture Organization of the United Nations (FAO) noted in a report on Tuesday that the “vast destruction of crops and infrastructure due to the war jeopardizes food production.”

FAO estimates approximately 33% of the crops and agricultural land may not be harvested because of the escalating war.

In March, Ukraine President Volodymyr Zelenskyy urged farmers to sow as many fields as possible to protect the food supply, but that appears to be a challenging task considering the displacement of people (labor shortage), bombed-out fields, severely damaged infrastructure, and shortage of everything (diesel, seeds, & fertilizer).

Ukraine is considered the world’s second-biggest shipper of grains and the biggest exporter of sunflower oil. The planting season has already begun — its crop production is vital to the global food supply.”

On the other side of the world, yet another problem arises.  ZeroHedge observes, “Farmers in China, India, Bangladesh, Indonesia, and Vietnam — the largest rice-producing countries could experience reduced output due to soaring fertilizer prices.

The International Rice Research Institute warns that harvests could plunge as much as 10% in the next season, equating to about 36 million tons of rice, or enough food to feed a half billion people, according to Bloomberg.

Chemical fertilizers, such as nitrogen, phosphorus, and potassium, are the most applied nutrients for high-yielding rice cultivation. Farmers have been particularly vulnerable to soaring fertilizer prices as some have reduced the amount of nutrients to save costs. This threatens future harvests as production declines could stoke food inflation for a crop that feeds half of humanity.”


9:35 am

BKX has emerged above the Lip of the Cup with Handle formation.  Unlike the Head & Shoulders formation, in which the neckline is considered impermeable, the Lip of the Cup with Handle formation allows passage through it on a retest.  BKX may resume is decline this weekend, if not sooner.


8:07 am

Good Morning!

SPX futures are reaching for the 38.2% retracement level at 4479.53 this morning.  Today is a day of trending strength in the Cycles.  It may also mean a reversal is at hand once the strength is spent.  Options expiration dominates trading today, as Max Pain is at 4450.00.  Gamma turns positive at 4525.00 and short gamma prevails beneath 4400.00.

ZeroHedge reports, ” US index futures were little changed, trading in a narrow, 20-point range, and erasing earlier declines as a selloff in bonds reversed with investors also focusing on the catastrophic Q1 earnings report from Netflix. Nasdaq 100 Index futures slipped 0.2% by 7:15 a.m. in New York, recovering from an earlier drop of as much as 1.2%; the Nasdaq 100 has erased $1.3 trillion in market value since April 4 as bond yields have been surging on fears of rate hikes. S&P 500 futures also recouped losses to trade little changed around 4,460. Treasuries rallied and 10Y yields dropped to 2.86% after hitting 2.98% yesterday. The dollar dropped for the first time in 4 days after hitting the highest level since July 2020, and gold was flat while bitcoin rose again, hitting $42K.

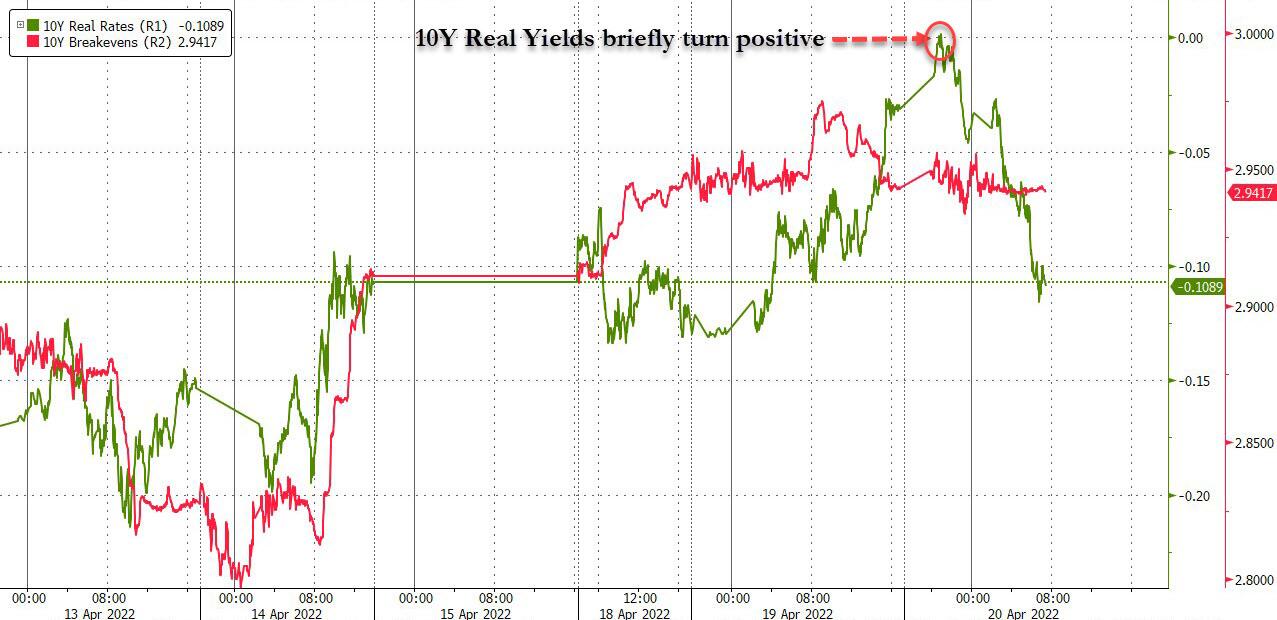
In perhaps the most notable move overnight, US 10-year real yields turned positive for the first time since March 2020, signaling a potential return to the pre-pandemic normal. But that was quickly followed by a global drop in bond yields as investors assessed growth challenges from the Ukraine war and the potential for a peak in inflation.”


VIX futures declined to a new retracement low of 20.21 on day 250 of the current Master Cycle.    Trending strength comes back at the end of this week and continues to build into May, suggesting an extended Master Cycle.


TNX is consolidating just beneath its peak at 29.30 on day 258.  The problem is that the EW pattern is incomplete, suggesting an extension is probable.  The Master Cycles are allowed up to 17 days of variance (plus or minus) while the average remains at 258 days.


USD futures are consolidating beneath the upper trendline and yesterday’s high at 101.03 on day 263 of the Master Cycle.  A reversal is anticipated at a decline beneath the Cycle Top support at 99.98.


Crude oil futures are bouncing back to retest the trendline near 104.00.  It may retest Intermediate-term resistance at 105.58.  A decline beneath the 50-day Moving Average at 101.98 confirms the reversal and may position crude oil for a two month decline.

ZeroHedge reports, “America’s liquefied natural gas (LNG) exports are booming amid a global energy crisis and a European drive to wean itself off Russian gas. U.S. shipments of natural gas have jumped to all-time highs this year as the United States is intent on helping Europe cut its dependence on Putin’s gas.  As demand for natural gas grows, export facilities along the U.S. Gulf Coast are operating at capacity and cannot ship more LNG than they are currently doing—at least not now. ”


Gold futures are trading lower beneath Intermediate-term support/resistance at 1952.54 this morning.  Gold is on a sell signal that may last for another two months, as well.


Posted in Published | Comments Off on April 20, 2022

April 19,2022

2:30 pm

Market Has Reached “Exhaustion Equilibrium”, Gamma-Hedging Flow Impacts Will Only Get Worse From Here

Make sure you are short beneath the 50-day Moving Average at 4420.00.


1:37 pm

The Ag Index is back-testing a probable support line at 570.50 prior to completing its current Master Cycle by the end of next week.  The Support may be a neckline that has been generated in March 2011 during the last Solar Minimum.  Tis one may be considerably worse.

Zerohedge reports, “A confluence of circumstances has come together to create a “perfect storm” for global food production, and now that “perfect storm” is about to get even worse.  For months I warned that this crisis was coming, and in recent weeks I have been documenting how dire conditions have already become all over the globe.  The head of the UN World Food Program is warning that this is going to be the worst worldwide food crisis since World War II, and even Joe Biden is admitting that the approaching food shortages “are going to be real”.  Unfortunately, there have been some new developments which threaten to significantly escalate things.”

ZeroHedge also observes, “A combination of factors has sent corn futures in Chicago to the highest level in a decade as investors fret over dwindling supplies.

Corn futures haven’t exceeded $8 a bushel since September 2012, following a devastating drought that damaged crops across the U.S. Midwest. Now supply risks return but for different reasons.

The global outlook for corn supplies has plunged since Russia’s invasion of Ukraine began in late February. The war-torn country supplies a fifth of the world’s corn and could experience a 50% decline in output this year.

Soaring fertilizer costs have forced some farmers in the U.S. to increase plantings of soybeans this growing season versus corn as the crop requires fewer nutrients. ”


1:10 pm

SPX is nearing the completion of a top-to-top Cycle in 12.9 market days (21.5 calendar days).  Should it go no higher, it will have made a 30% retracement.  Weakness prevails.  The next Cycle may take 21.5 market days (30.1 calendar days) to the bottom.

RealInvestmentAdvice prognosticates, “Is there a bear market lurking in the shadows?

Such seems to be the question everyone is asking me as of late. Over the last couple of weeks, we have reviewed the bullish and bearish cases for the market.

In those discussions, I tried to balance the bullish and bearish arguments into some actionable strategies over the next few weeks. The purpose of analyzing both views is to minimize confirmation bias, which can negatively impact portfolios over time.

“When investors seek out information that confirms their existing opinions and ignore facts or data that refutes them, such may skew the value of their decisions based on their own cognitive biases. This psychological phenomenon occurs when investors filter out potentially useful facts and opinions that don’t coincide with their preconceived notions.” – Investopedia

While analyzing the shorter-term probabilities of a further advance or decline, the case for a more significant lurking bear market within the next 18-months solidified. Such is the context of today’s post.”


8:00 am

Good Morning!

NDX futures were on a roller coaster in the overnight session, ranging from 13828.00 to 14017.90.  Overhead resistance appears to be the Intermediate-term resistance at 14224.45.  It has since then settled back down beneath 14000.00, which appears to be the maginot line.

As for tomorrow’s options expiration, Max Pain is at 14000.00.  There is an especially large number of puts (101) at 13910.00, suggesting a decline beneath that level could spark a firestorm of selling.  In the meantime, the roller coaster continues its mission of frustrating both the bulls and the bears.

ZeroHedge observes, “Morgan Stanley’s runner-up in the “Biggest Wall Street Bear” category (to BofA’s Michael Hartnett whose weekly Flow Show doom and gloom is now a source of inspiration for bears everywhere) is out with his own weekly dose of pessimism and in his latest US Equity Strategy note, Morgan Stanley chief US equity strategist Michael Wilson writes that “Q1 earnings season will be more disappointing than thought” and that “inflation is no longer a net positive for earnings growth.”

Wilson, whose bio and message header speaks for itself, and hints that bulls are now “the greater fool”…

… predicts that “earnings revisions will decelerate amid 1Q reporting season as the MS Business Conditions Index (a survey of industry analysts) just fell further and margin headwinds mount / are not fully reflected in consensus estimates. Stocks should discount this risk via the ERP channel.”

Worse, Wilson argues against of the most recurring (and perplexing) arguments spread by the bears, namely that inflation is actually positive for stocks – which it is, to a point –  and according to Wilson, that point has now been reached and writes that “inflation is no longer a net positive for earnings growth given the impact on costs that are now showing up in margins.”


SPX futures are flat after an overnight range between 4376.70 and 4415.80.  Tomorrow’s expiring options show Max Pain near 4400.00.  Expiring options turn positive at 4450.00, but negative beneath 4390.00.  Gamma turns short at 4350.00 and more so each 25 points beneath it.  Dealers and hedge funds may be walking a tightrope to keep options from spinning out of control.

ZeroHedge reports, “After some jerky rollercoaster moves in Monday’s illiquid trading session, which jerked both higher and lower before closing modestly in the green, US futures resumed their volatility and at last check were trading flat after earlier in the session rising and falling; Nasdaq futures retreated 0.1%. as investors weighed the risks to economic growth from hawkish Federal Reserve comments. Stocks in Europe dropped as markets reopened after the Easter holiday, while bonds around the globe slumped as investors weighed the prospect of aggressive policy action to curb inflation. Asian stocks also dropped as did oil, while the dollar extended its gains .  Treasuries extended declines, with the 10-year yield hitting a fresh three-year peak north of 2.90%. German and U.K. 10-year yields climbed to the highest since 2015 as bonds across Europe plunged.”


VIX futures consolidated in a narrow range between 22.19 and 22.92 as it awaits the breaking of the stalemate in stocks.  Tomorrow’s options expiration shows Max Pain at 26.00 with short gamma beneath 23.00.  Long gamma kicks in at 30.00.

The NYSE Hi-Lo Index closed at -164.00, solidly in bear country.  While on a sell signal, confirmation is added beneath -200.00.


TNX futures made an overnight high of 29.09 before pulling back at the open.  Today is day 258, and we should be looking for a reversal in the next few days.  Getting a sell signal here may be difficult since TNX is so high above support.  However, unless a phase shift occurs, we may see TNX pull back to the 50-day Moving Average over the next six weeks.


USD futures made a new high at 101.01 this morning as it wraps up its Master Cycle on day 263.


WTIC futures made an abrupt reversal at the Cycle Top resistance at 109.46, suggesting that may have been the Master Cycle Top on day 262.  The significance of that is a potential 2-month decline into the end of June.  A 50% retracement of the rally from April 2020 takes WTIC down to 68.20.  A 68.2% retracement may decline to 63.07, near the Wave (4) low of 61.74.  The question is, “What would make crude oil do that?”


Gold futures made a sudden breakdown, declining beneath the Cycle Top at 1966.96, making a low of 1959.85.  That suggests a probable decline to the mid-Cycle support at trendline at 1831.11 may be made over the next two months.


Posted in Published | 2 Comments

April 18, 2022

3:20 pm

SPX could not rise to the 50-day Moving Average at 421.14 today, showing profound weakness.  Should SPX decline beneath 4370.00, it may continue the decline to new lows.  Otherwise, there may be another attempt to retrace more of the decline.

ZeroHedge reports, “There are other types of stock market leverage, and no one knows how much leverage there is in total. Margin debt is the only reported indicator...

Margin debt – the only type of stock market leverage that is reported regularly – dropped by another $36 billion, or by 4.3%, in March from February, and by 12.4% over the past three months, to $800 billion, according to FINRA which collects this data from member brokers. Margin debt has now fallen below the year-ago level. But leverage is still gigantic and has a long way to go.

After peaking in October at $936 billion, margin debt started falling in November, which was also the month that the Nasdaq started falling. Margin debt has since fallen by 14.5%. The Nasdaq has fallen by 17.6%.

And many of the highfliers have collapsed by 60%, 70%, and even over 90%, some of which I track in my collection of Imploded Stocks. Stock jockeys that were margined in those trades got turned into forced sellers to raise the cash to pay down their margin debt. A margined portfolio specialized in these stocks can get wiped out.”


10:44 am

BKX continues to make new lows, with one of two possible outcomes.  The first is a potential stretch of the Master Cycle to day 273, the most likely scenario, as the decline completes its fifth Wave of an impulsive decline.  Should that be the case, BKX may bounce above the Lip of the Cup with Handle, possibly to the 50-day Moving Average at 124.85, in a brief retracement.  The second outcome is that BKX may decline even lower in an oversold panic decline.  Note the Target for the Cup with Handle.  This target may be due by the end of June.


9:58 am

GKX has clearly broken above its previous high at 570.50 made in March 2011.  This may be interpreted as a possible Head & Shoulders formation, although a long one, with a target in the range of 900.00.  There are about two weeks left in the current Master Cycle, after which it may retrace back down to the trendline at 570.50.  The alternate formation may be a Cup with Handle formation, with a slightly lower target.

ZeroHedge reports, “The bird flu outbreak has only been spreading around the US for two months, and some industry experts are warning the rate of spread could be worse than the devastating 2015 outbreak.

On Friday, the US Department of Agriculture (USDA) announced yet another state where the contagious strain of highly pathogenic avian influenza has been detected. Idaho is the 27th state where the virus has been found since February.

WaPo spoke to Gro Intelligence (ag data experts) senior research analyst Grady Ferguson who tracked the last outbreak in 2015, saying this one could be more disruptive to the poultry and egg markets.

Ferguson said that 66 days into the outbreak, 1.3% of all US chickens had been affected, and 6% of the US turkey flock. In 2015, he said, only .02% of total chickens were affected at this same time. The number rose to 2.5% of chickens infected at the outbreak’s peak, and more than 50 million were culled.

So far, the bird flu tsunami wave across 27 states has infected 27 million chickens and turkeys, forcing farmers to “depopulate” or cull flocks to prevent spreading.

ZeroHedge observes, “There is a high probability that a self-perpetuating wage-price spiral will develop in the next few years. Households have already become less resistant to paying higher prices and firms have become less resistant to offering higher wages. Prices and wages will continue to spiral upward until the cumulative erosion in inflation-adjusted incomes causes the economy to collapse in recession. It is like the children’s game of musical chairs: Everyone knows the game will end, but they feel compelled to keep racing around the circle at an ever-faster pace hoping their forced exit will leave them in the best possible position—even if it still means an inflation-adjusted loss.

This situation has been termed “inflationary psychology.” Consumers purposely advance their purchases in order to beat anticipated future price increases. Firms readily pass along higher costs to consumers, including the future cost increases that they anticipate. That’s what happened in the last inflationary age, which started in 1965 and ended in 1982: Expected inflation became a self-fulfilling prophecy. Many commentaries assert that the current situation is nothing like the situation faced in 1978-80. That’s true, but irrelevant. The more apt comparison would be to the five to ten years prior to that period, when inflation had not yet reached crisis levels. Government officials claimed they had the policy tools that could easily reverse inflation, just as they claim now.”

Making for a potentially worse outcome, ZeroHedge reports, “A fertilizer supply shock is imminent for US farmers as CF Industries Holdings, Inc. warned Thursday that rail shipments of crop nutrients would be reduced to top agricultural states, which couldn’t come at the worst time as the Northern Hemisphere spring planting season is underway.

The world’s largest fertilizer company said Union Pacific had hit it with railroad-mandated shipping reductions that would impact nitrogen fertilizers such as urea and urea ammonium nitrate shipments to Iowa, Illinois, Kansas, Nebraska, Texas, and California. Union Pacific told CF Industries without advance notice to reduce the volume of private cars on its railroad immediately. This means CF Industries had to decrease shipments by a whopping 20% to stay compliant.

“The timing of this action by Union Pacific could not come at a worse time for farmers,” said Tony Will, president and chief executive officer of CF Industries.

“Not only will fertilizer be delayed by these shipping restrictions, but additional fertilizer needed to complete spring applications may be unable to reach farmers at all. By placing this arbitrary restriction on just a handful of shippers, Union Pacific is jeopardizing farmers’ harvests and increasing the cost of food for consumers,” Will said. “


8:00 am

Good Morning!

NDX futures continue to lead the stock indices lower.  The weekend low was 13731.70 and the bounce has stayed beneath 13900.00.   In today’s options expiration, Puts currently dominate with an especially large put position (172 contracts)  right at 14000.00.  However, there is also a large position of calls (150) at 13750.00.  Should the NDX slide beneath 13750.00 today, the the outcome may be dramatic.  NDX is on a sell signal.

ZeroHedge observes, “Observations From A Week On The Road

1. General skepticism from the trading community on equity markets. Most conversations center around the deep challenge faced by global central banks: how to move with serious force on inflation, without provoking an asset bust or a recession. While most acknowledge that its hard to foresee a near-term US recession when jobs are so plentiful and wage growth is so strong, the crowd struggles to envision how the Fed can ultimately pull off a soft landing. To be sure, this wariness is reflected in survey work and positioning metrics: AAII bull sits at the lowest level in 30 years, and length held at GS PB by fundamental hedge funds sits at the lowest level since April of 2020.”


SPX futures bounced at a low of 4361.60 only to be repelled at Thursday’s lows.  The outlook for next two weeks appear to be dismal and the decline may last into mid-May.  Today’s expiring options are short beneath 4440.00 and short gamma takes over beneath 4360.00.  While a bounce over the next three days may help to neutralize the effects of options on the markets, there seems to be no willpower to make it happen.  SPX is on a sell signal.

ZeroHedge reports, “Equity futures fell, Treasury yields rose and nat gas prices soared to the highest since 2008 as US markets reopened after a three-day holiday weekend while the U.K. and euro-zone markets remain closed. Nasdaq 100 futures led the retreat, falling 0.3% at 730 a.m. EDT after tumbling as much as 0.8%, and signaling a bearish start to the week after the U.S. market was closed on Friday for a holiday. S&P 500 futures also dropped 0.2%, while European markets remained closed on Monday. Oil was flat, while a cautious overall investor mood bolstered the dollar and gold. The USDJPY was set for the longest winning streak on record.

Nat gas soared another 3%, rising to the highest level since 2008.

“We think inflation is no longer a net positive for earnings growth given the impact on costs that are now showing up in margins,” Morgan Stanley strategists led by Michael Wilson wrote in a note. The effects of soaring prices “are now more likely to be a headwind to growth.”


VIX futures reached a morning high of 24.60.  VIX is on a buy signal above mid-Cycle support at 21.26 with confirmation above 25.00.  Today’s options expiration is dominated by puts from 17.00 to 25.00.  The short-vol trade appears to be very popular.  An emergence over 25.00 is likely to change the tenor of the market with a potential wipe-out of a massive number of puts.

The NYSE Hi-Lo Index closed on Thursday at -136.00.  It is on a sell signal.


TNX futures reached a weekend high of 28.84 before pulling back.  This morning’s high may be the Master Cycle high on day 257 of the current Cycle.  It may take another day or two to confirm it.

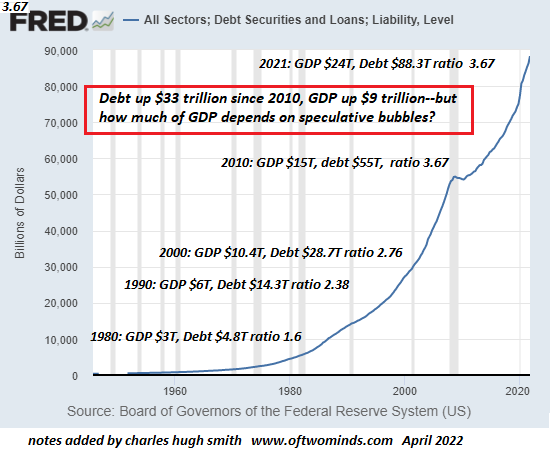
ZeroHedge advises, “When the system can’t borrow more and distribute the insolvency, it implodes

I started writing about debt saturation back in 2011. The basic idea is we can continue to borrow and spend as long as one of two conditions hold: 1) real (inflation-adjusted) income is rising, so there’s more income to service additional debt, or 2) the cost of borrowing declines so the same income can support more debt.

After 13 long years of declining interest rates and stagnant incomes for the bottom 90%, we’ve finally reached debt saturation: after dropping to near-zero, interest rates are now rising, pushing the cost of debt service higher, while wages are losing purchasing power (a.k.a. inflation), so there’s less disposable income left to service debt.”


USD futures rose to 100.76, not overcoming Thursday’s high at 100.77.  Should USD not go higher,  Thursday’s Master Cycle high on day 258 may be confirmed by declining beneath the Cycle Top at 99.66.


Crude oil futures surged to 108.00 this morning, approaching its Cycle Top resistance at 109.95.  There may be a pullback at the Cycle Top resistance, but the trend is higher.  Trending strength returns in May.

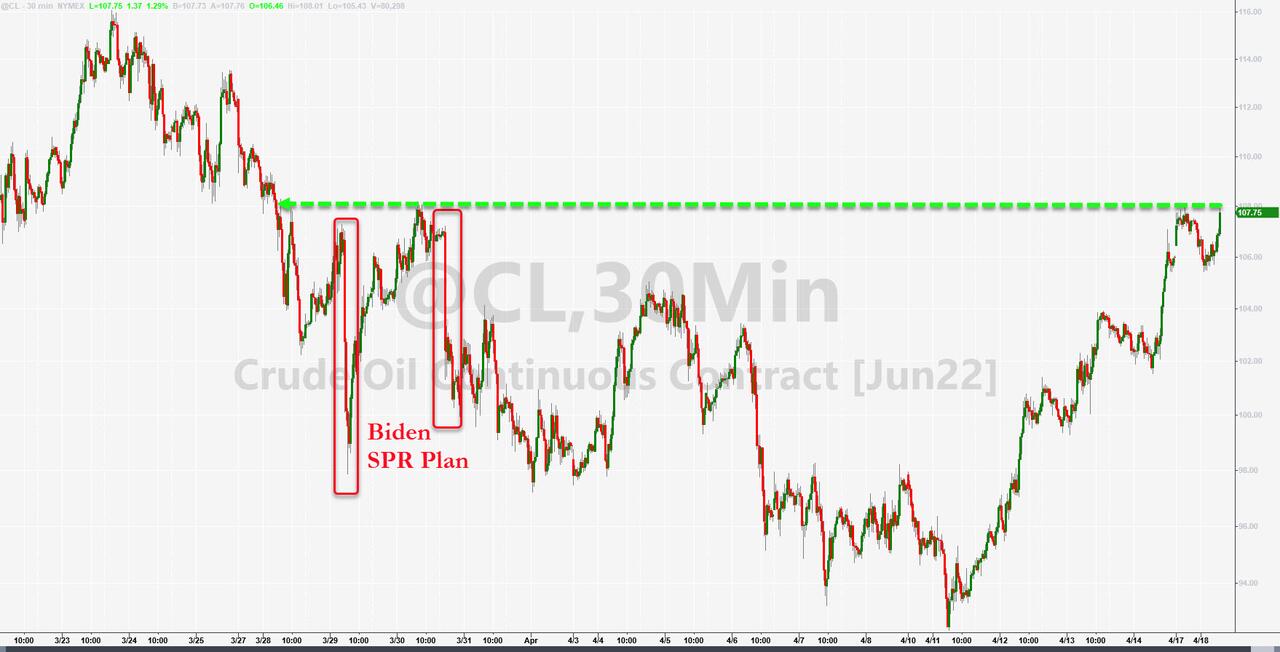
ZeroHedge reports, “On the heels of lower Russia output (sanctions and snubs of Urals crude, despite record discounts) and Libya’s oil production plunging by more than half a million barrels a day amid a wave of political demonstrations engulfs the OPEC member’s energy industry, oil prices have extended their gains this morning, with WTI now erasing all of the lower price benefits from Biden’s SPR Release Plan announced in late-January. It also appears Biden’s relenting on Ethanol and land leases has done nothing at all (for now).

WTI Crude topped $108 this morning..

This is a major problem for President Biden as ‘the largest release’ in history has achieved nothing at all in terms of his endgame hope of reducing gas prices at the pump, which are now turning up once again, following crude and wholesales gasoline prices back towards record highs…



Posted in Published | Comments Off on April 18, 2022

April 14, 2022

8:00 am

Good Morning!

NDX futures attempted to assault the 50-day Moving Average at 14325.05, but failed, pulling back beneath Intermediate-term support/resistance at 14242.77.  While still oversold, the inability to overcome that double resistance may condemn the NDX to a continued oversold decline that may intensify into a panic.  The unfilled gaps give us a clue as to the profound weakness of the NDX.  Attempting to buy the dip here may be sheer suicide.


SPX futures, while still above critical support, also show similar signs of weakness.  Thus far they have managed to stay above the 50-day Moving Average at 4426.50, but once beneath that level, may spin out as well.

Today’s a.m. expiring options must settle near 4450.00 for Maximum Pain.  The majority of today’s options expire in the morning.  The p.m. options show Max Pain at 4430.00, but are considerably lighter, most likely in deference to Passover and Good Friday.

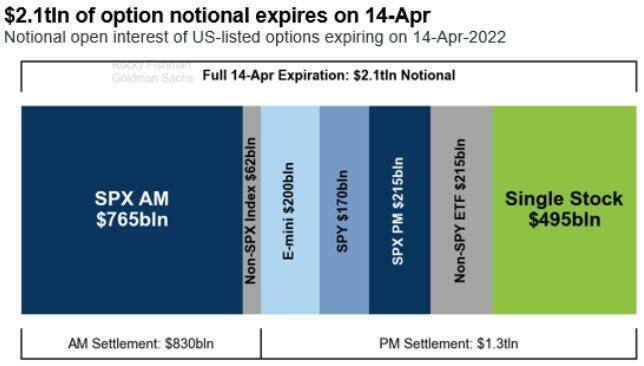
ZeroHedge reports, “US index were flat on Thursday, reversing earlier gains sparked by hopes of imminent easing in China, as investors turned their attention to the ECB which is set to maintain its speedier withdrawal of stimulus, data on retail sales and unemployment claims, and a barrage of earnings from Goldman Sachs, Morgan Stanley, Citigroup and Wells Fargo, and all of this happening as $2.1 trillion in options are set to expire (since tomorrow is a holiday).

At 7;00am ET, S&P futures were unchanged at 4440, Nasdaq futures were down 0.1% and Europe’s Stoxx 600 rose 0.2%. Asian stocks rose after China again indicated looser monetary policy is on the way. Treasuries extended gains as investors dialed back aggressive bets on Federal Reserve interest-rate hikes. The yen bounced from a two-decade low against the dollar. The greenback slipped after snapping its longest winning streak since 2020. Oil fell. Twitter shares soared after Elon Musk offered to buy the whole company for $54.20.”


VIX futures remain flat above the mid-Cycle support at 21.23.  Today’s Cycles Model shows little trending strength, but it may return over the next two weeks, leading into a probable Master Cycle high by the end of April.

YahooFinance restates, ” (Bloomberg) — Strap in for spikes in the S&P 500 index’s so-called “fear gauge” now that the Federal Reserve has flipped from being a friend to something more akin to a foe to markets as it tightens monetary policy.

That’s in essence the view from strategists at Bank of America Corp. for the Cboe Volatility Index, a gauge of implied equity swings for the S&P 500.

“High and persistent inflation is turning the Fed from a suppressor of vol and source of returns to a source of vol and suppressor of returns,” BofA strategists including Nitin Saksena and Riddhi Prasad wrote in a note. They added this kind of backdrop “skews our outlook for equities negatively.”


The NYSE Hi-Lo Index made a probable Master Cycle high of only 58.00 on Tuesday, day 257.  A lower high in this indicator is not a good sign.


TNX may be finishing a shallow retracement as the Cycles Model suggests a return of the rally with strength early next week.  In addition, it may be due for a Master Cycle high by the end of next week.

ZeroHedge reports, “Ahead of today’s last-for-the-week coupon auction, we asked if following yesterday’s unexpectedly ugly 10Y reopening which tailed more than 3bps following a 12bps intraday rally, we would see another chunky tail thanks to today’s repeat rally.

Then, just a few moments later we got the answer, and while not quite as “chunky” as yesterday’s 10Y, we did get another tail in the 30Y: with the auction stopping at a high yield of 2.815%, the highest since May 2019 and 44bps higher than last month, this was a 0.9bps tail vs the 2.806% When Issued. And while the auction was certainly uglier compared to last month’s 2.4bps stop through, it was nowhere near as bad as February’s disaster when as a reminder the 30Y tailed by a record 10.6bps during the initial market shock following the Fed’s furious repricing of rate hike expectations.

The bid to cover of 2.30 was below average, and sliding from 2.458 last month it was also below the six-auction average of 2.32%.”


USD futures appear to be consolidating in range this morning after making a probable Master Cycle high on day 257.  The “Top is In” at the point that USD declines beneath the Cycle Top support at 99.37.

ZeroHedge remarks, “Ever since Zoltan Pozsar started echoing Zero Hedge circa 2010, and in note after feverishly-drafted note, the former NY Fed repo guru has been writing about a coming monetary revolution in which commodity-backed currencies such as the yuan become dominant and gradually displace the world’s reserve currency – the US Dollar – which slowly fades into irrelevancy in a world where commodities are the fulcrum asset and where paper wealth is increasingly meaningless, there have been three reactions: i) those who have no idea what Zoltan is writing about (that would be about 98%), ii) those who agree wholeheartedly and believe that the USD should be dethroned as a reserve currency yesterday, and iii) those who are just a little bit “displeased” with all the attention the strategist (who has correctly called every major crisis and turning point in markets in the past decade) is getting and are starting to lash out at his stream of consciousness.

Rabobank’s Michael Every, himself a geopolitical status quo skeptic yet clearly misaligned with Zoltan as to what happens next (and in reality a believer that the broken system we have now will be the broken system we have for a long, long time to come), is in group three, and following a handful of “subtweet” shots across the Zoltan bow (which have barely registered in the financial media, especially Bloomberg, which Every continuously mocks yet reads religiously) the Rabobank strategist has (bravely) penned the closest thing to a Pozsar rebuttal we have seen.”


Crude oil may be consolidating between the 50-day Moving Average at 100.05 and Intermediate-term resistance at 104.82, going no higher than 104.16 thus far.  Should it go higher, it still has overhead resistance at the Cycle Top at 108.06.  Today is day 258 of the existing Master Cycle.  Should WTIC stall at or beneath the Cycle Top, we may see prices go lower.


Posted in Published | Comments Off on April 14, 2022

April 13, 2022

9:40 am

BKX is making new lows lest than a week after making its Master Cycle low. This is unusual, but may be anticipated in a slingshot move (lower).  We may see another test of the Lip of the Cup with Handle formation as mixed earnings results are announced.  However, the new Master Cycle may run through the end of June before breaking higher.  This is a proxy for market liquidity and a good indicator of what may be coming over the next two months.

ZeroHedge reports, “irst quarter earnings season has officially started with JPM reporting Q1 results which were somewhat mixed (top-line beat, EPS miss) thanks to strong trading offset by weaker than expected IB revenues. The company’s net interest income outlook was also raised for full year 2022 to $53BN from $50BN, and just to make sure that investors were happy, the bank announced a new $30BN share buyback, which perhaps was meant to cover up the fact that JPM reported an unexpected $524 million loss “driven by funding spread widening” as well as “credit valuation adjustments relating to increases in commodities exposures and markdowns of derivatives receivables from Russia-associated counterparties.”

Starting at the top, JPM reported total adjusted revenue of $31.59 billion, above the exp. of $31.44BN resulting in EPS of $2.63, just missing the 2.73 consensus estimate, the lowest earnings since Q2 2020.”


8:25 am

Good Morning!

NDX futures rose overnight to 14092.30 in as weak retracement.  Normally, we would see a retracement ot the 50-day Moving Average at 14329.62.  The weakness appears profound, possibly due to the short gamma effect.

ZeroHedge observes, “Last weekend, when looking at the latest JPMorgan Prime Brokerage data, we noted that the “pain trade” remains higher as unlike retail, hedge funds have been selling every rally aggressively with the largest US bank seeing “net selling in 8 of the past 9 days,” during which stocks have staged a torrid rally.

At the same time, we also observed that the bulk of the recent market meltup has been on the back of a massive short squeeze and covering of puts (creating a delta and gamma squeeze) which makes it especially difficult to predict what happens next as most if not all of the recent market meltup has been due to technicals and positioning, not fundamentals.

Still, we said that the simple conclusion is that that “either hedge funds will reverse their selling soon and jump on board the retail buying bandwagon (at which point it will again be time to short), or retail will run out of buying power amid the hedge fund-to-retail “distribution”, and stocks will tumble once again.”


SPX futures rose to 4432.10 in the overnight session, then gave it all back in the premarket, declining back beneath 4400.00.  The Maginot Line for today’s options expiration is 4400.00.  While calls are marginally higher over 4400.00, puts prevail in volume beneath 4390.00.  The dealers and hedge funds supporting liquidity for this market are walking a very fine line…

ZeroHedge reports, “US index futures bounced, with Nasdaq 100 contracts halting a three-day drop, as investor attention turned to the start of corporate earnings season, which BofA dubbed the “Last big beat for a while” amid concerns over high inflation and slowing growth. Contracts on the Nasdaq 100 were up 0.4% as of 630 a.m. in New York, signaling a pause in the rout that wiped $1.6 trillion from the market value of technology behemoths in just over a week. S&P 500 futures and Dow futures gained 0.4%, with Asian stocks also rising even as Europe’s Stoxx 600 Index dropped; the selloff in U.S. Treasuries also eased with the 10Y yield flat at 2.72% while the US Dollar resumed its advance and the yen fell to a 20-year low as the growing gap between rising U.S. bond yields and perpetually low ones in Japan continued to pressure the currency. Oil rose after Russia vowed to continue the war in Ukraine and China partially eased Covid curbs. Bitcoin continued to trade on either side of $40K.”


VIX futures dipped to 23.13 late yesterday before  moving back to 24.14 this morning.  Should VIX not emerge above the 50-day Moving Average at 25.64 we may see an effort to suppress it back down to the mid-Cycle support at 21.21 to calm the equities market prior to the Easter weekend.  While the Cycles Model is unclear about direction over the next two days, the picture changes dramatically next week.

The NYSE Hi-Lo Index closed at -168.00 yesterday, clearly showing internal weakness.


TNX is consolidating in place, although that may soon change, as trending strength may prevail through the next week.  One reason for investors reluctance to sell stocks is that the “normal” rotation from stocks to bonds may be worse than simply staying in stocks, at least thus far.  It almost appears that there is a buyers’ strike in the 10-year Notes.

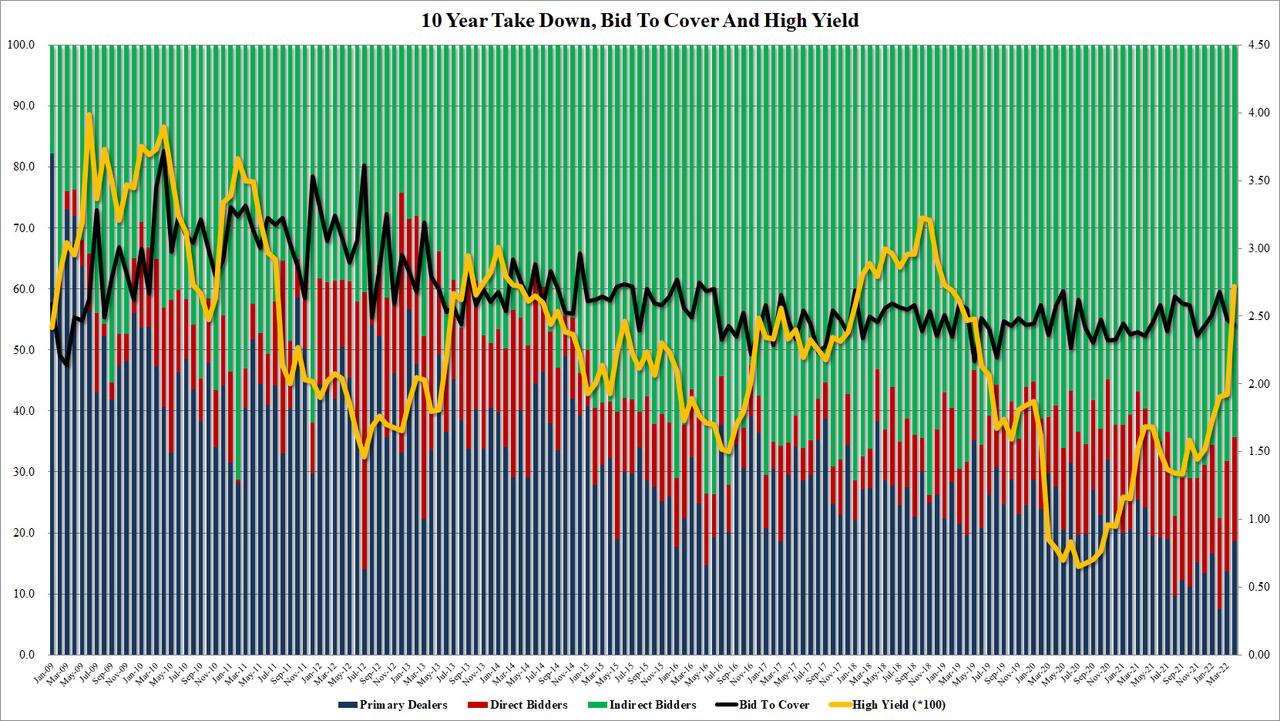
ZeroHedge reports, “Far uglier than yesterday’s 3Y auction, in fact far uglier than any 10Y auction in the past 5 years, moments ago the Treasury sold $34 billion in 10Y paper in a reopening auction at a high yield of 2.720%, 80bps above last month’s 1.92%, and a whopping 3bps tail to the 2.69% When Issued – the biggest tail on our record which goes back to 2016 – as buyers balked at purchasing the benchmark paper with yields trading near session lows following the “not as bad as expected” CPI print.

The bid to cover was also a disappointing 2.43, the lowest of 2022 and well below the 2.50 six-auction average.

The internals were likewise ugly, with Indirects taking down just 64.3%, the lowest since July 2021 and with Directs awarded 18.7% (the most since last July), meant Dealers were left with 18.0%, just modestly above the recent average of 16.7%.


USD futures have hit a new high at 100.51 this morning, as the final surge to the Master Cycle high winds up by the end of the week.


Crude oil is forging higher, to 102.42 this morning.  It appears to have made its Master Cycle low on Monday, day 255, in a flat correction..  The reversal closed above the 50-day Moving Average yesterday at 99.72, creating a buy signal.  Although there is no immediate pattern of strength, the new Master Cycle may run until the end of June.


Posted in Published | Comments Off on April 13, 2022

April 12, 2022

2:44 pm

SPX is now beneath 4400.00 and deeper in short gamma territory.  There may be a final push as high as 4471.00 made this morning to complete the corrective pattern in an expanded flat correction during Wednesday options expiration.  Once completed, the next move lower may take out the March 14 low.  Thursday may be aa different ballgame.

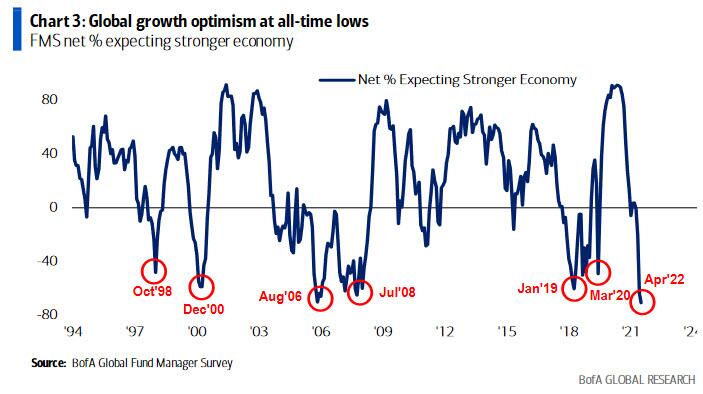
ZeroHedge comments, “One month after the March Fund Manager Survey was downright “apocalyptic” with the majority seeing a bear market and stagflation, and with optimism plunging to levels right before Lehman, today Bank of America published the latest, April FMS (available to pro subs in the usual place) in which the bank’s doom-and-gloomy Chief Investment Strategist Michael Hartnett found that his view is shared by even more Wall Street professionals, because the survey which polled 329 panelists managing $929 billion in AUM, found that global growth expectations plunged even more compared to last month, and dropped to fresh all-time lows (net -71%) …

… even as the percentage of those overweight equities remains stubbornly high (expect this number to slide in the coming weeks alongside stocks) and as BofA notes “The disconnect between global growth and equity allocation remains staggering.  Investors got slightly more bullish on equities. Though still at depressed levels, equities are nowhere near “recessionary” close-your-eyes-and-buy levels.” As a reminder, we first flagged this “rare disconnect” back in September, and since then it’s only gotten worse.”


8:00 am

Good Morning!

NDX futures bottomed out at midnight at 13897.90 before making a bounce.  This morning they have surpassed 14000.00 and may retest the 50-day Moving Average at 14330.93.  What was support two days ago may become resistance.  Should it surpass the 50-day, we may see a reprieve from the decline through the rest of the week.

Wednesday and Thursday are back-to-back options expiration days.  While Wednesday’s options expiration is light, Thursday’s expiration favors puts beneath 14150.00 and short gamma may prevail beneath 14000.00.

ZeroHedge notes, “Hedge fund positioning: Back to lows. 0%-tile

Equity long/short hedge fund leverage is back to mid-March lows. Gross and net leverage both fell about 3% since the end of March which puts both at the 0th %-tile on a 12M basis with gross at the lowest since May 2020 and net at the lowest since September 2020.

Source: JPM Prime Brokerage

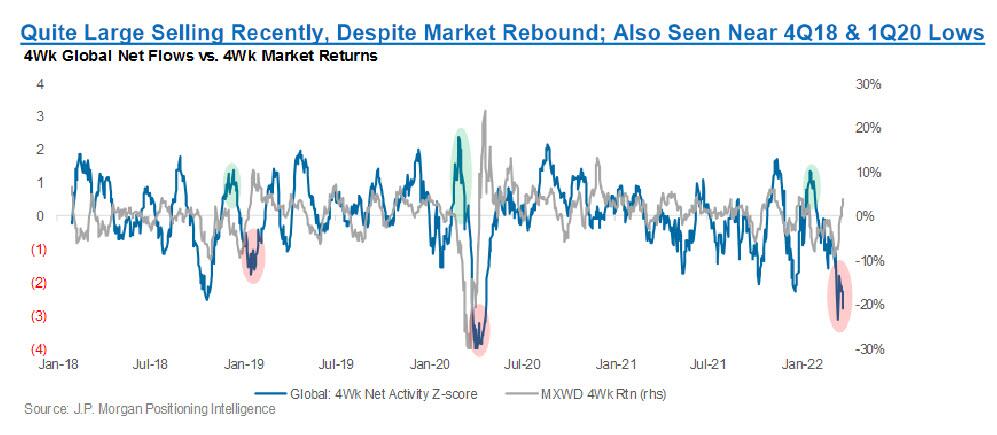
Puke in a Pic

In N. America we’ve seen selling for weeks now and the 4wk net flows z-score is around a -3z level after touching as low as a -4z level in the middle of last week.

Source: JPM PB


The NYSE Hi-Lo Index closed yesterday at -245.00 at day 256 of the Master Cycle.  Regardless of the potential bounce today in share prices, a further decline in the Hi-Lo Index may indicate further weakness through the rest of the week.

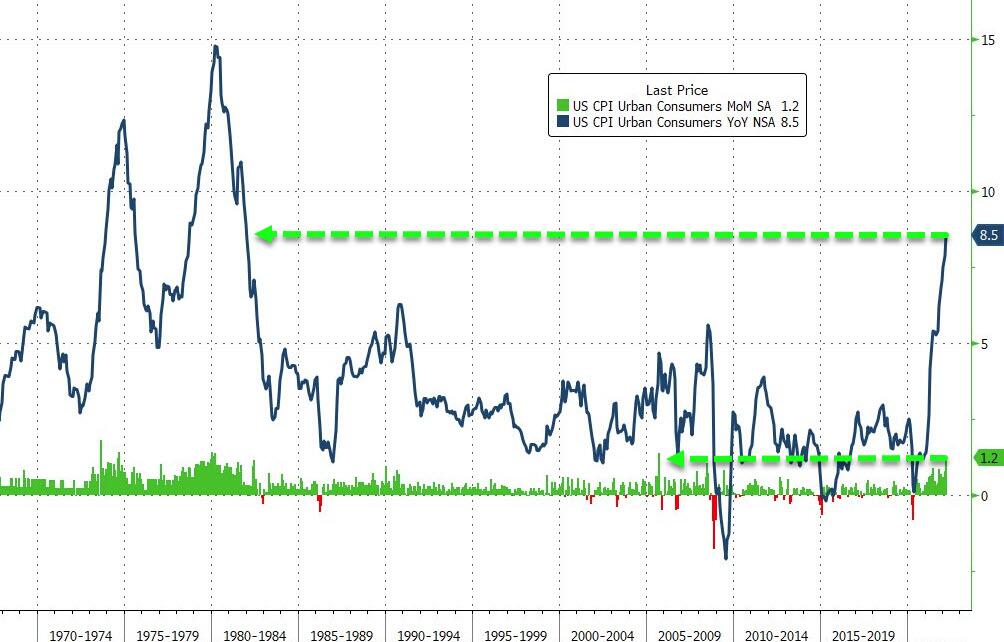
ZeroHedge reports, “Having warned the world to expect “extraordinarily elevated” levels of inflation due to “Putin’s Price Hike”, The White House is likely in shock this morning as headline CPI rose 1.2% in March (vs +1.2% MoM) which sent the headline CPI up a shocking 8.5% YoY (vs +8.4% YoY exp and +7.9% prior) – the highest since 1981.

Source: Bloomberg

The 1.2% MoM rise is the biggest since Sept 2005 and CPI has risen for 22 straight months.

However, Core CPI (ex food and energy) rose just 0.3% MoM (below the +0.5% expected) and was up 6.5% YoY (above Feb’s 6.4% but below the +6.6% exp).

The shelter index was by far the biggest factor in the increase, with a broad set of other indexes also contributing, including those for airline fares, household furnishings and operations, medical care, and motor vehicle insurance.”

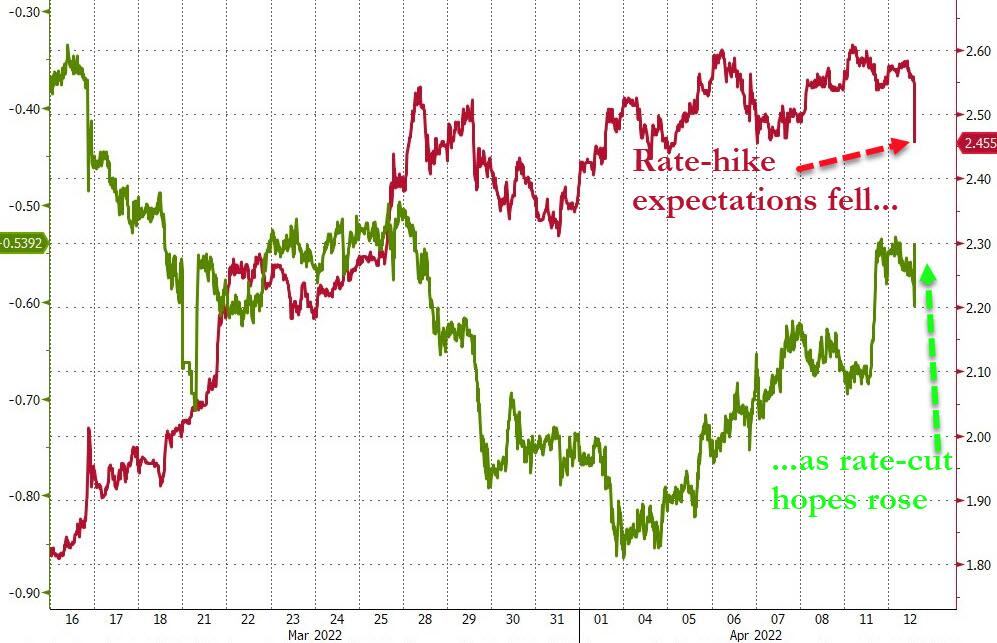
ZeroHedge comments, “On the basis that the CPI prints were “not as bad as they could have been”, US markets have reacted as if The Fed can step back from its hawkish stance and all will be well in the world.

Rate-hike expectations have eased modestly for the year… although the market is pricing in a 97% probability of 50bps hike in May(up from 92%)…


SPX futures also declined to 4387.20 by midnight, only to bounce in the morning back above 4400.00.  The 50-day Moving Average is at 4424.85 and may be challenged this morning.  Should it go higher, strong resistance lies at the mid-Cycle line at 4506.37.

This week’s shortened calendar brings heavy put and call positions every 50 points with calls edging out the puts above 4450.00 and puts prevailing beneath 4400.00 with very large positions on both sides up and down the scale.  this may be a difficult options week to evaluate.

ZeroHedge reports, “US index futures were flat on Tuesday, rebounding off overnight session lows as investors braced for red hot inflation data which the White House yesterday called “extraordinarily elevated” and which will likely boost the argument for aggressive monetary tightening – perhaps even a 75bps or intermeeting rate hike – despite a looming economic slowdown. Nasdaq futures were 0.2% higher, while S&P futures were flat after dropping as much as 0.5%.”


VIX futures rose to 25.36 at midnight, but have retreated since then, especially after the CPI print.  The Cycles Model allows the VIX to correct down to the mid-Cycle support at 21.19.  However, it indicates a probable explosion of strength over the weekend, suggesting a resumption of hostilities in the Ukraine during the Holy Week of Easter.


TNX pulled back this morning from its new high as it takes a breather.  The Cycles Model exhibits too much strength for a sustained or significant pullback for at least another week.


USD futures are consolidating within Monday’s trading range.  Today is day 256 of the Master Cycle A reversal may be made as USD crosses beneath the Cycle Top Support at 99.40.  It may happen at any time.


Posted in Published | Comments Off on April 12, 2022

April 7, 2022

10:15 am

BKX ahs plunged beneath the Lip of the Cup with Handle formation and has entered a bear market with a 22% loss from the all-time high.  Today is day 262 of the current Master Cycle.  Should BKX not reverse here, this proxy of liquidity may show a serious strain on liquidity which may only get worse over the next 10 weeks.

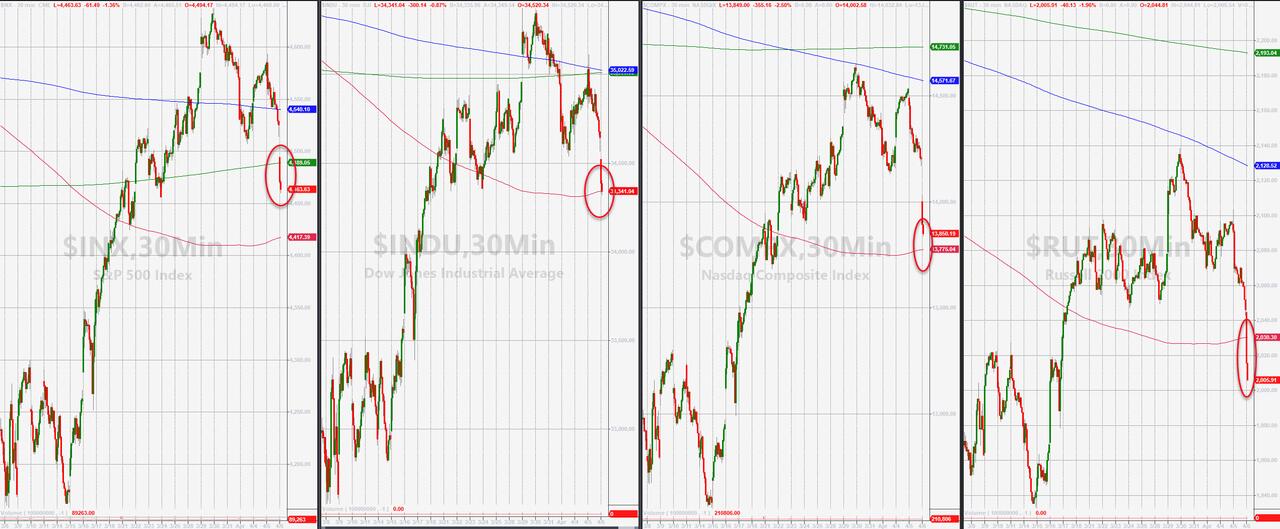
ZeroHedge observes, “The second half of March came to an end and so did the meltup. Building on yesterday’s losses – as we detailed here – this morning’s breakdown has snapped all the major US equity markets below critical technical support levels.

The S&P is back below its 200DMA. The Dow and Russell 2000 are back below their 50DMA, and Nasdaq is rapidly accelerating down towards it 50DMA…

This comes as former NYFed President Bill Dudley issues another post-service op-ed warning that “If Stocks Don’t Fall, the Fed Needs to Force Them”…

It’s hard to know how much the U.S. Federal Reserve will need to do to get inflation under control. But one thing is certain: To be effective, it’ll have to inflict more losses on stock and bond investors than it has so far.”


9:59 am

The Ag Index is held beneath mid-Cycle resistance at 550.95 but may not remain there as Trending Strength is about to make a comeback.  The Cycles Model suggest very strong upward momentum through the end of April, starting tomorrow.  We may see ag prices double by the end of the year.

ZeroHedge reports, “America’s largest farmer cooperative sounded the alarm Wednesday about possible disruptions of fertilizer supplies from Russia due to Western sanctions on Moscow.

CHS Inc., the largest agricultural cooperative in the US, said in an SEC filing that it’s concerned about obtaining Russian fertilizer because of sanctions making it “more expensive and difficult to do business with Russia.” 

CHS warned that sanctions could “cause delays with respect to, or prevent, shipments of fertilizer to us, cause inflationary pressures on and impact our ability to purchase fertilizer, disrupt the execution of banking transactions with certain Russian financial institutions and result in volatility in foreign exchange rates and interest rates, all of which could have a material adverse effect on our business and operations.”


8:15 am

Good Morning!

SPX futures have been consolidating inside yesterday’s trading range, with a midnight low of 4458.80 and a morning high of 4500.40.  Having been repelled by the mid-Cycle resistance at 4503.91, it is now declining to test the 50-day Moving Average at 4418.38.  Options expiration for tomorrow shows SPX in short gamma beneath 4500.00 with the heat turned up dramatically beneath 4450.00.  The Cycles Model shows trending strength increasing on Friday which suggests a breakdown beneath supports.  It also shows a probable six weeks of decline.

ZeroHedge reports, “U.S. index futures edged higher, along with European shares, after the sharpest two-day drop in almost a month, as investors digested Federal Reserve’s hawkish path and were jerked higher by a fleeting moment of Ukraine ceasefire hope when Emini futures initially spiked to session highs on the following Reuters headline:

  • RUSSIAN FOREIGN MINISTER SAYS UKRAINE PRESENTED A NEW DRAFT AGREEMENT TO RUSSIA ON WEDNESDAY – IFX

… only to reverse the entire move two minutes later when the following headline hit:

  • LAVROV: UKRAINE PROPOSALS ON CRIMEA, DONBAS UNACCEPTABLE: IFX

Mini hiccup aside, S&P futures were about 0.1% higher at 4,481 while Nasdaq futures gained 0.5% to 14,574, signaling an end to a selloff in the underlying index that erased $850 billion in market value over two days.  Ten-year Treasury yields were flat around 2.61%, the dollar extended its rally to a sixth day, the longest streak in almost 10 months, and oil rebounded from yestereday’s IEA reserve release-driven plunge.”


VIX futures declined to a morning low of 21.54 and has bounced from mid-Cycle support.  The Cycles Model shows trending strength increasing this weekend (Friday, perhaps?) and gaining momentum through the end of April.

The NYSE Hi-Lo Index fell to -200.00, confirming an equities sell signal.

SeekingAlpha explains, “Summary

  • The VIX ETPs have quite a few quirks and as a result of these quirks and their high volatility, there are considerable risks for both longs and shorts.
  • From the 30,000-foot perspective, the big risk in being short volatility is that a big one-day VIX spike can theoretically destroy the value of your entire position.
  • While the number of VIX ETNs is dwindling, ETNs have their own set of issues, as these are debt securities – essentially a promise to pay the value of the underlying index – rather than a portfolio of VIX futures, as is the case with VIX ETFs.”


TNX continues making new highs this morning.  Normally we may see a pullback to Cycle Top support at 22.96.  However, TNX trending strength comes roaring back on Monday and continues through the end of the Master Cycle shortly after options expiration, suggesting a very short correction, if any.

ZeroHedge explains, “Everywhere we look we see short gamma – TLT edition

TLT is trading around the max short gamma pain level. Expect more erratic moves…

Source: Nomura


USD futures made a new overnight high at 99.85 before easing back.  USD is in the final stage of its Master Cycle with a potential 5 days left.  The potential target for this move may have a minimum of 101.00 and may go as high at 105.00.


Crude oil made a new low at 95.47 before bouncing to test the 50-day Moving Average at 98.83.  The Cycles Model suggests increasing downward momentum through April options expiration.   Wave C may equal Wave A near its trendline at 70.00.  A panic decline may go to the Cycle Bottom at 55.17.

ZeroHedge reports, “Western oil majors have quit Russia altogether, taking billions of dollars in vague impairment charges on Russian energy assets, and now comes the hard math. This morning energy giant Shell Plc said that it will write off between $4 and $5 billion in assets in a first-quarter 2022 outlook.

Thursday’s announcement provides investors with an early glimpse at the costs of fracturing global supply chains for oil majors following Shell’s decision to exit Russia after the invasion of Ukraine.

“For the first quarter 2022 results, the post-tax impact from impairment of non-current assets and additional charges (e.g. write-downs of receivable, expected credit losses, and onerous contracts) relating to Russia activities are expected to be $4 to $5 billion,” Shell said. 

“These charges are expected to be identified and therefore will not impact Adjusted Earnings,” it continued. 

The charge surpasses the company’s earlier estimate of $3.4 billion worth of oil-producing assets in Russia.

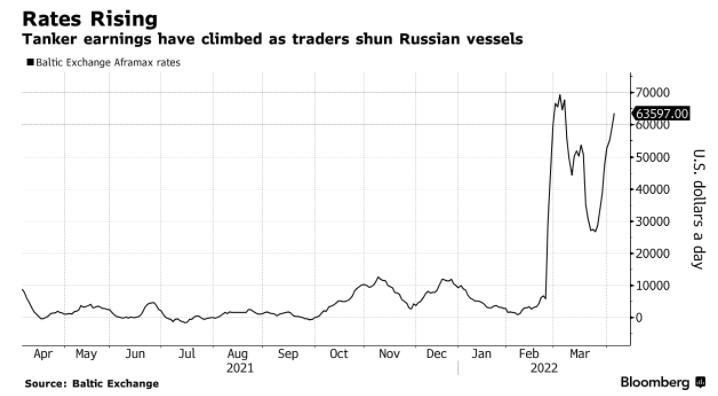
On a similar note, ZeroHedge observes, “Since Russia invaded Ukraine, many Western countries have banned Russian crude imports. Now, however, countries and companies are shunning the use of Russia’s massive fleet of oil tankers, which has driven up tanker rates, according to Bloomberg.

Shipping analyst Peder Nicolai Jarlsby at Oslo-based Fearnley Securities wrote that Sovcomflot PJSC, a state-controlled company with the largest Aframax-class fleet in the world, has been shunned by global oil traders. The result is fewer oil tankers available to haul crude, which has pushed up tanker rates.

Rising freight costs add to inflationary headwinds for the energy market that will only boost costs for refineries and, in return, continue to increase the costs for producing crude products, such as gasoline and diesel.


Posted in Published | 3 Comments

April 6, 2022

2:15 pm

FOMC Minutes Signal Bigger, Faster-Than-Expected QT, Multiple 50bps Hikes

ZeroHedge explains…

…and there it goes…

2:00 pm

SPX bounced at 4460.00 to retest the mid-Cycle resistance at 4503.96.  There is a likelihood that dealers and hedge funds supporting the options market may attempt to keep SPX elevated above the short gamma zone at 4500.00 through closing.  A close beneath that level may create a bloodbath in the options market.  Be aware of the dynamic that may cause a panic decline.

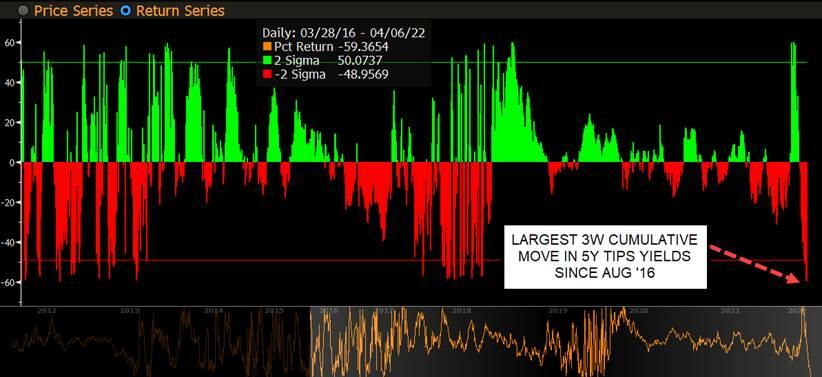
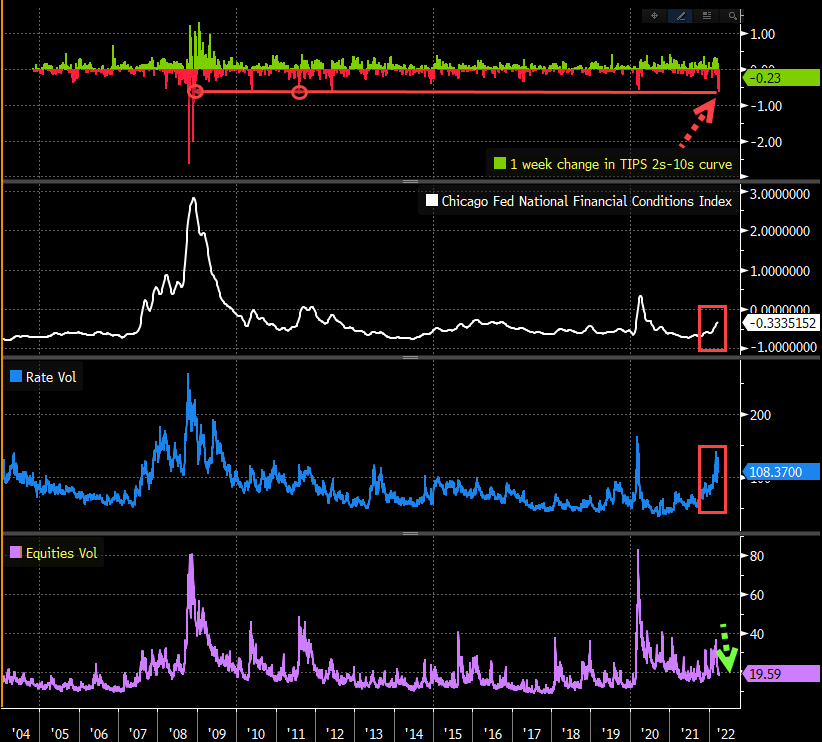
ZeroHedge comments, “The recent rally in stocks is, macro-wise, incoherent with what has been happening in financial conditions. Specifically, the 1w change in TIPS 2s10s curve was just the largest impulse flattening since the US debt downgrade in Aug ’11 and Dec ’08, while the cumulative 3 wk move in 5Y TIPS yields is the largest since Aug ‘16…

…along with tighter FCI and higher Rate Vol…all while Equities iVol has collapsed…

But, as Nomura’s Charlie McElligott points out in a note this morning, this sudden “shock tightening” in Financial Conditions – as Real Yields are exploding higher (5Y TIPS Yields from -1.66 to current -0.59bps over the past 3 weeks!) – is allowing “macro truths” to finally override recent “bullish” mechanical flows in Equities.”


10:30 am

NDX has declined beneath Short-term support at 14530.00 and may threaten the 50-day Moving Average at 14343.00 soon.   It is declining into short gamma which may make the decline self-reinforcing.  Watch what happens at the 50-day.

ZeroHedge remarks, “The second half of March came to an end and so did the meltup. Building on yesterday’s losses – as we detailed here – this morning’s breakdown has snapped all the major US equity markets below critical technical support levels.

The S&P is back below its 200DMA. The Dow and Russell 2000 are back below their 50DMA, and Nasdaq is rapidly accelerating down towards it 50DMA…

This comes as former NYFed President Bill Dudley issues another post-service op-ed warning that “If Stocks Don’t Fall, the Fed Needs to Force Them”…


9:45 am

GKX is wavering between mid-Cycle resistance at 551.00 and Intermediate-term support at 541.90.  However, the Cycles Model suggests a powerful breakout by the end of the week and extending through the end of April.  As mentioned previously, the minimum target appears to be over 800.00 over the current Cycle and may exceed 1000.00 by the end of the year.

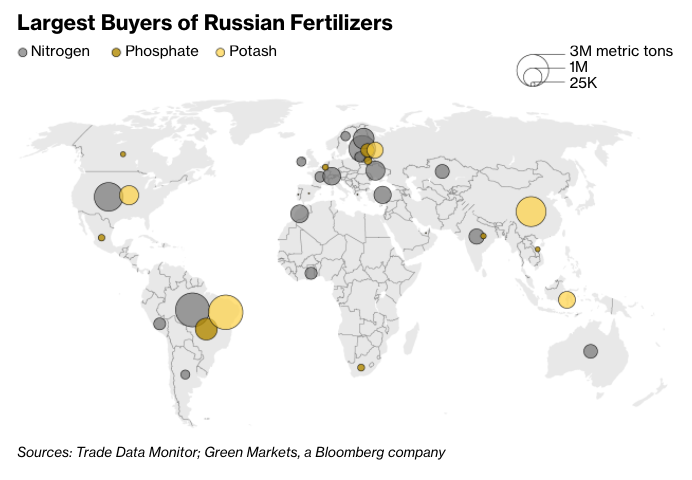
ZeroHedge explains, “The EU is expected to deliver another shock to its agricultural sector by capping Russian imports of potash, a crucial ingredient for growing food, according to Bloomberg, citing a Dow Jones report.

The European Commission is expected to imminently unveil broad new sanctions on Russia. Much of the fertilizer is purchased from Belarus; the landlocked country in Eastern Europe could also be slapped with new sanctions for its involvement in Russia’s invasion of Ukraine.

Potash is a key ingredient for agricultural fertilizers. Europe produces only a negligible amount of the fertilizer, and to potentially cap imports from Russia and or Belarus (top producers) seems idiotic for Europe as the spring planting season is only beginning.

Even if Europe were to rework its supply chains to import potash elsewhere, only a few other countries would export it. The impact of capping imports will send prices even higher and create fertilizer shortages for crops. This can dramatically affect crop harvests at the end of the growing season. ”


8:20 am

Good Morning!

NDX futures are making new lows, having declined beneath the April 1 low at 14723.00.  It may have broken its trading range and descended into short gamma territory and, should it not reverse course, may decline into a doom-loop panic Cycle ending after May options expiration.

ZeroHedge remarks, “Beware the negative earnings revision

Earnings revisions just about to turn negative (so far disguised by commodity upgrades). Credit Suisse shows that in 71% of the times when earnings revisions turn negative the equity market falls (this measured as over the following quarter). (Credit Suisse Equity strategy)

NASDAQ – what was gained is now lost

Our main take remains intact, this market needs to consolidate before anything new big can take place. NASDAQ futs remain trapped in the 15200-14600 range for now. We are not getting short term excited until we break that range. Longer term, the 100 crossing the 200 day moving average isn’t overly bullish, although last time it happened was close to lows in late 2018 (chart 2).”


SPX futures have broken beneath mid-Cycle support at 4503.33 and is now threatening to break the 200-day Moving Average at 4489.23.  Today’s expiring put options may be exploding, since SPX is now in short gamma territory.  The sell signal is confirmed.

ZeroHedge reports, “There is a scene in My Cousin Vinny where Joe Pesci’s puzzled wannabe-lawyer character asks the judge if he was really serious ’bout dat.

On Tuesday and overnight, incredulous algos and 15 year old hedge fund managers had a similar question to the Fed about its market-crushing, rate-hiking intentions, after yesterday the Fed’s in house permadove and Hillary Clinton donor, Lael Brainard, shocked markets when she not only made the case for accelerated rate hikes but also a faster balance sheet drawdown after she said that curbing inflation is “paramount” and the central bank may start trimming its balance sheet rapidly as soon as May.

As a result, investors once again feared out that a more restrictive U.S. central bank could end up tipping the world’s largest economy into a downturn, or even a recession, something which is now Deutsche Bank’s base case for 2024. The virus resurgence in Asia and the war in Ukraine are also clouding the outlook for prices and growth.”


VIX futures leaped above the mid-Cycle resistance at 21.14  to a morning high of 23.43, confirming its buy (SPX sell) signal.  This may be the beginning of a nasty short squeeze in the VIX, especially should it rise above 25.00 where gamma turns seriously long.  It’s ironic that the SEC has approved the re-opening of the short-VIX ETFs in the past couple of weeks.

ZeroHedge remarks, “Remember the “good” old VIX days?

Remember when VIX’s “natural floor” or as quant analysts would call it “longer term average” was around 13/14? The VIX has trended higher over the past 5 years, despite the Fed expanding the balance sheet. You get the point, VIX is “distorted”. Let’s see what happens when they start the “rapid pace” reduction…

Source: Refinitiv

The disturbing trend in VVIX

VVIX and VIX are long term mean reverting assets, but they undergo structural shifts as well. Ever since Fed restarted the presses in 2019, the VVIX has traded well bid, trending higher. VVIX is down from recent highs, but let’s see what happens when the BS starts shrinking and volatility is already distorted.”

Source: Refinitiv


TNX gapped above its current trend channel, suggesting it may be making a running (irregular) correction.  This suggests a move that may be beyond “normal” expectations.  That is why it is important to pay attention to predictive formations, such as the Cup with Handle, which advises the 10-year yield climbing above 3.00 in a very short period of time.

ZeroHedge observes, “The inversion of the two-year and ten-year yields creates more problems for the Fed and the financial markets than for the economy.

That’s because the yield curve inversion has occurred at a relatively low level of interest rates, far too low to slow final demand and squash inflation pressures.

History shows that yield curve inversions offer an accurate negative view of the economy’s future path only when accompanied by a level of interest rates that prove prohibitive. In the past, restrictive interest rates were when the federal funds rate and market rates equaled or exceeded the growth in nominal income.

Notably, that is not the case today. On the contrary, it’s the exact opposite. A record gap exists between Nominal GDP growth of 10% in the past year and the current fed funds of .5%. There is even a record spread between Nominal GDP and two and ten-year yields of around 2.5%.

Yield curve inversion at low-interest rate levels is a nightmare for the Fed.”


USD futures rose to a morning high of 99.74, breaking through the prior high at 99.43 before easing lower.  The current Master Cycle still has a week to go, so the target of “above 100” remains valid until a reversal signals the end of the Master Cycle.


West Texas Intermediate Crude futures may be consolidating today, making neither a new high or new low.  However, the Cycles Model suggest weakness over the next week as the current Master Cycle comes to a close.  A lot may happen in a week’s time, especially when monthly options come due.  The average decline in Wave C may equal the length of Wave A, putting WTI near the mid-Cycle support at 81.25.  Should a panic ensue, crude may decline down to the Cycle bottom at 55.11.

ZeroHedge remarks, “Three weeks ago in mid-March, in the latest confirmation of Zoltan Pozsar’s prediction that commodity trading giants are caught in a “Margin Call Doom Loop” (see Pozsar: “We Could Be Looking At The Early Stages Of A Classic Liquidity Crisis“) Wall Street was stunned to learn that commodity trading houses had – in their view – become “too big to fail” and the European Federation of Energy Traders, a trade body that counts BP, Shell and commodity traders Vitol and the margin-call stricken Trafigura as its members, said the industry needed time-limited emergency liquidity support to ensure that wholesale gas and power markets continued to function.

Translation: the world’s largest commodity traders were calling on governments and central banks to provide a bailout in the form of “emergency” assistance to avert a cash crunch as sharp price moves triggered by the Ukraine crisis strained commodity markets and sparked massive margin calls across the industry.

However, as we noted at the time, it wasn’t immediately clear if central banks would come running to the commodity giants’ rescue. As the FT notes, “some may be reluctant to help trading firms that often make large profits from shifts in commodity prices.” However, senior ECB officials are keeping a close eye on global commodity markets, and as ECB vice-president Luis de Guindos said last week, derivatives, including commodity derivatives, were a very specific market that we are looking at very carefully.

Ultimately, central banks made a decision last Friday afternoon, when a Bloomberg headline briefly flashed only to be buried in the usual firehose of Ukraine news and fake news:

  • *ECB TURNS DOWN ENERGY TRADERS PLEA FOR FUNDING SUPPORT”


Posted in Published | Comments Off on April 6, 2022