November 29, 2021

10:24 am

However, the NYSE Hi-Lo Index only briefly opened positive and has declined since then.  This is not conducive to a strong, sustained rally.  Should the rally not be able to sustain itself in the next few hours, we may see a downturn  by this afternoon.

11:10 am

The Hi-Lo declined even further to -50.00.  Things don’t look good for the rally.

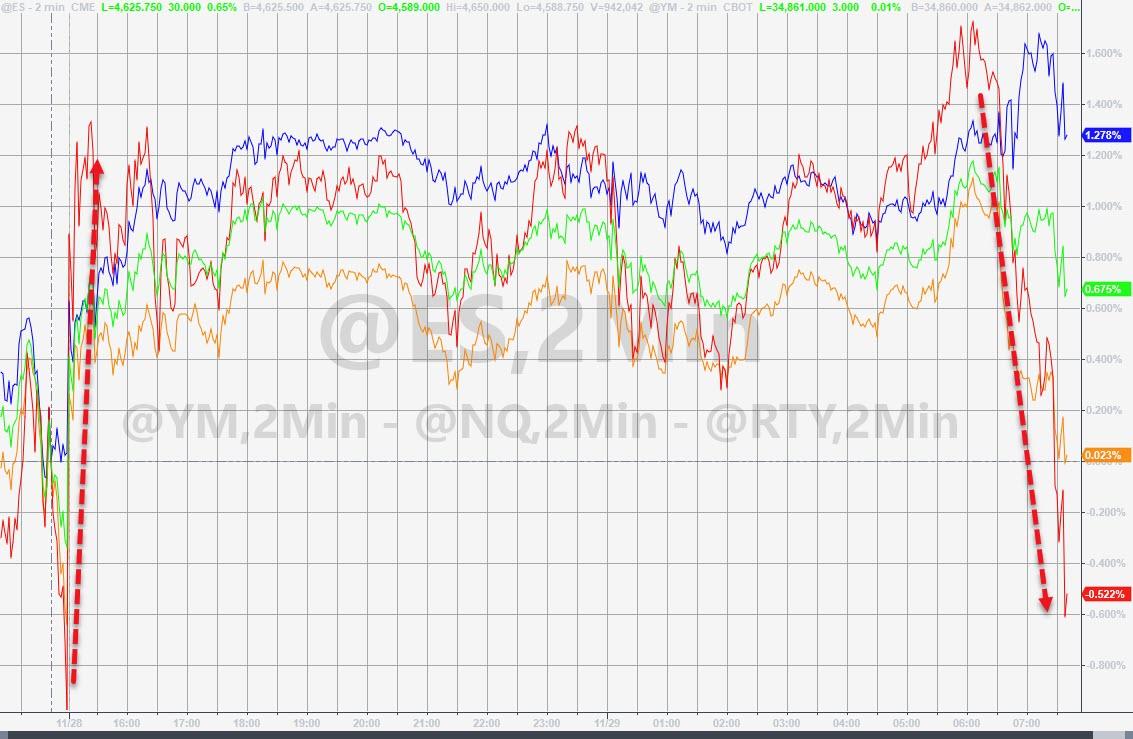
ZeroHedge informs, “While Nasdaq continues to hold rebound gains, The Dow and Small Caps have erased all the weekend’s “Omicron’s not all that bad” gains since the US cash equity open…

Interestingly, there is some building anxiety under the hood as VIX calls expiring on Dec. 22 are among the most active options contracts in early Monday trading.”


10:17 am

SPX is at an interesting crossroad.  It may either go higher, with a possible target of 4680.00 (Short-term resistance) or the 61.8% retracement at 4683.00…

…or it may resume its decline from here.  There are two different Elliott Wave structures that may be indicated simultaneously.

ZeroHedge poses the dilemma, “A lot of investors finally have what they wished for: a chance to buy the dip. The problem is uncertainty is much higher now.

Friday’s selloff, fueled by the emergence of a new Covid-19 variant, brought a firm halt to the market’s exuberance of recent weeks. The Stoxx 600 Index is now more than 5% below its record closing high of mid-November, opening a window for those who have been awaiting weakness to add positions.

“Many investors had been complaining about ever-rising markets that give little entry opportunities,” says Martin Moeller, co-head of Swiss and global portfolio management at Union Bancaire Privee in Geneva. “Here is the next one shaping up, given that in 2022, the easing of supply chains and delayed execution of very strong prior order intake should be supportive for economic growth.”


8:20 am

Good Morning!

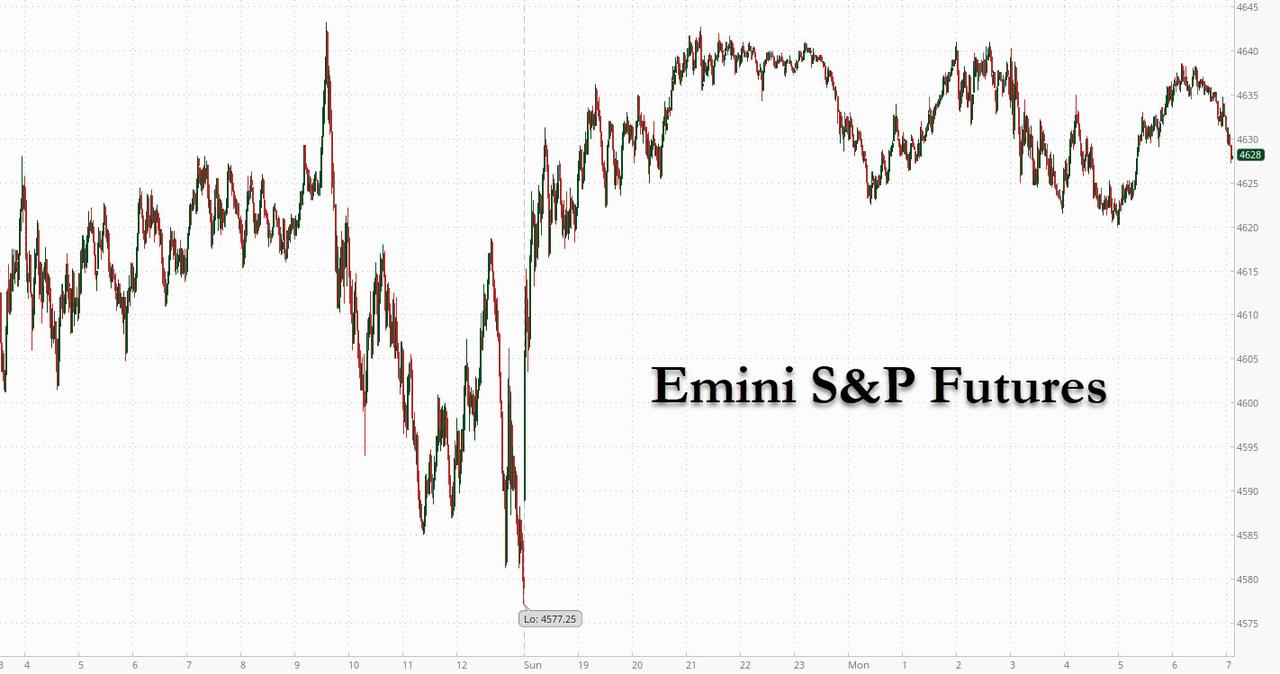
The expected bounce at mid-Cycle support came over the weekend with SPX futures rising to a high of 4646.00, just above the 50% retracement of Friday’s decline at 4644.00.  Pundits blame the decline on the Omicron scare, ignoring the fact that the uptrend may be finished.

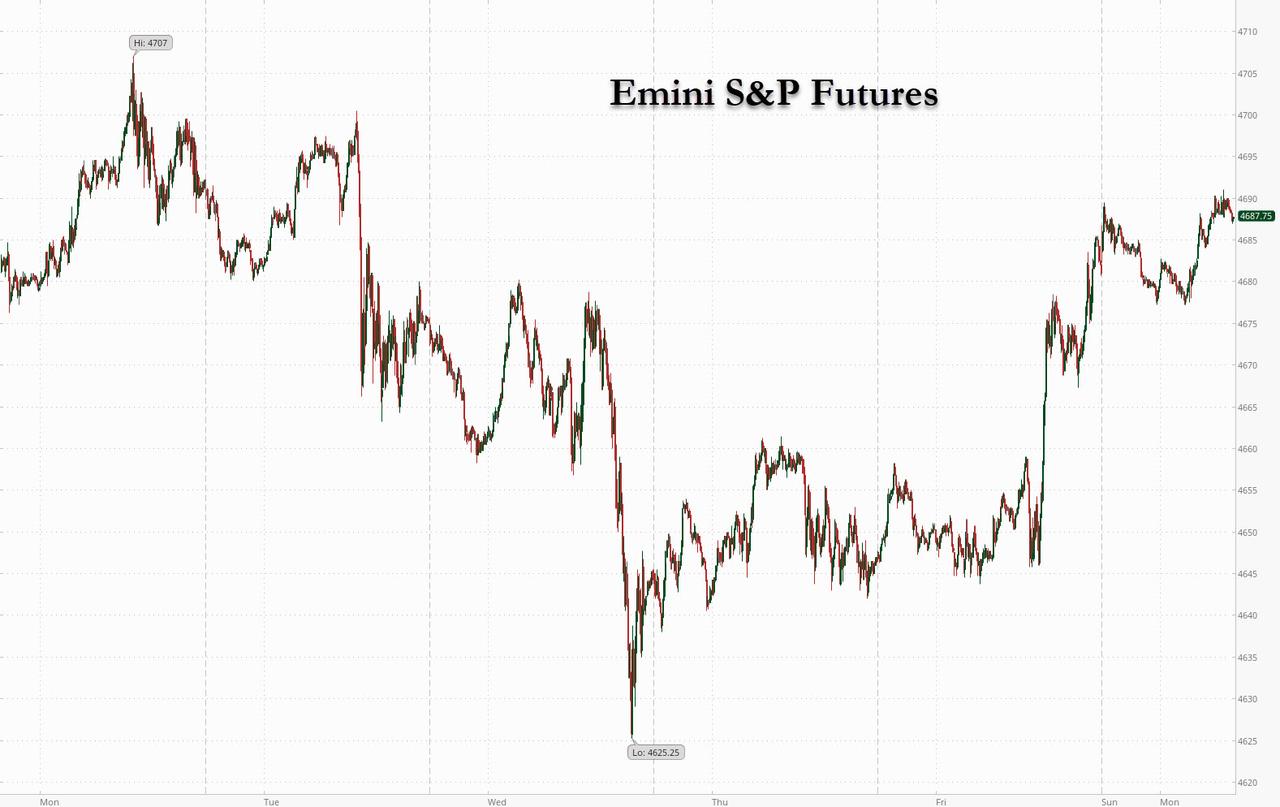
ZeroHedge reports, “As expected over the weekend, and as we first noted shortly after electronic markets reopened for trading on Sunday, S&P futures have maintained their overnight gains and have rebounded 0.7% while Nasdaq contracts jumped as much as 1.3% after risk sentiment stabilized following Friday’s carnage and as investors settled in for a few weeks of uncertainty on whether the Omicron variant would derail economic recoveries and the tightening plans of some central banks. Japan led declines in the Asian equity session (which was catching down to Friday’s US losses) after the government shut borders to visitors. The region’s reopening stocks such as restaurants, department stores, train operators and travel shares also suffered some losses.  Oil prices bounced $3 a barrel to recoup some of Friday’s rout, while the safe haven yen, Swiss franc and 10Y Treasury took a breather after its run higher.”


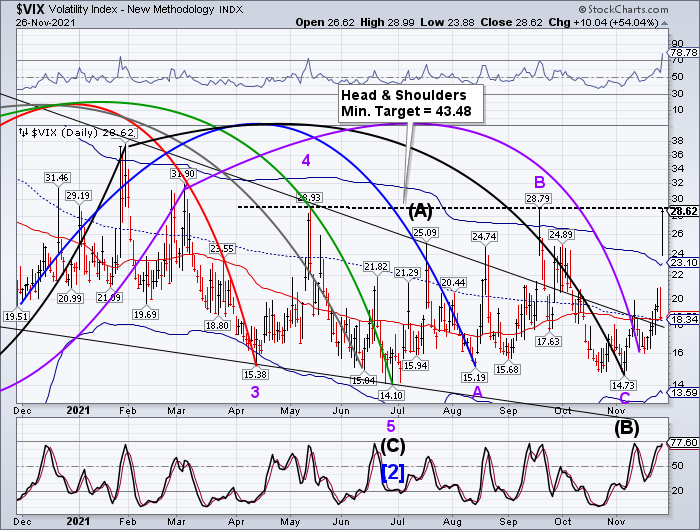
VIX futures declined to 24.45, well above the Cycle Top support at 23.10.   VIX is behaving as it should in a new Master Cycle that may last another month.  Pundits refer to this as a contrived  “fearstorm.”  However, from a Cycles perspective, it was overdue.


The NYSE Hi-Lo Index made an even deeper low on Friday.  It is well into its sell signal.  It is likely that there may be a bounce back.  However, the Cycles Model suggests the decline in the Hi-Lo may last another two weeks, at a minimum.


TNX recovered from its Friday swoon, having completed an irregular correction and beginning its strongest move higher, Wave (C), in the series.  We may see a breakout in the next few days, with a high degree of strength growing in the rally the week of December 6.


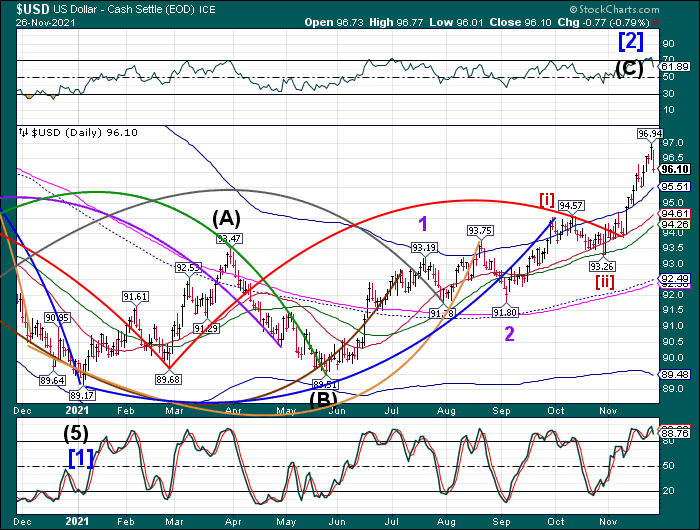
USD futures began a consolidation, rising to 96.39 over the weekend.  It may rise out of the consolidation as early as this week.  If not, trending strength may return the week of December 6.


BKX is likely to retest its 50-day Moving Average at 136.33.  Wednesday may have been the last day of strength in the uptrend.  Trending strength may return the week of December 6, but may accentuate the downtrend.


Posted in Published | Comments Off on November 29, 2021

November 26, 2021 – Red Friday

11:42 am

SPX fell beneath Intermediate-term support at 4599.82 and is back-testing that support/resistance area.  Nearby higher resistance is at 4620.00 -4625.00.  Should the SPX fail to exceed that level, the decline may resume shortly.   VIX is still beneath the neckline at 28.79.  However, the NYSE Hi-Lo has fallen to -118.00, a new low.

ZeroHedge adds commentary, “It’s pretty clear that markets are not having a good day today, and all else equal, it’s likely they will only get worse for the simple fact that gamma is now broadly negative, and more put buying (and selling) will lead to more selling (and put buying).

As our friends at SpotGamma note, for those looking at market support (and resistance), the main levels remain similar to that of Wednesday: support at 4600 and resistance at that 4650 area which is also the gamma flip point. The bulk of positive gamma is positioned up into the 4675-4700 which is where we see major resistance. As gamma is negative we anticipate large directional swings in todays shortened session.”

See you on Monday.


10:50 am

Welcome to “Red Friday.”  I had expected this move on Monday, not today, due to light after-holiday trading.

ZeroHedge reports, “The Friday after thanksgiving is called black Friday because that’s when retailers finally turn profitable for the year. Not so much for market, however, because this morning it’s red as far as the eye can see. The culprit: the same one we discussed late last night – the emergence of a new coronavirus strain detected in South Africa, known as B.1.1.529, which reportedly carries an “extremely high number” of mutations and is “clearly very different” from previous incarnations, which may drive further waves of disease by evading the body’s defenses according to South African scientists, and soon, Anthony Fauci.”


VIX made nearly a 51% spike this morning on the news of the Nu Covid variant.  It appears that the Head & Shoulders neckline may be the next target to fall.  Note that, should the neckline be exceeded, a more likely target may be 48.00-50.00.

ZeroHedge warns, ”

The Market Ear Picture

Welcome to pure panic

We haven’t seen Eurostoxx 50 “VIX”, V2X, spike by almost 50% in a long time. This is pure panic. Having much view on volatility here is naive, but if you ever felt like buying when there is blood on the streets, this could be one of those days…

Source: Refinitiv

VIXplosion

Haven’t seen VIX up by almost 50% in a long time. The situation remains extremely fluid. For now it looks like the big bond guys were right.”


The NYSE Hi-Lo Index may be on its way to a new low today, even on shortened trading hours.

BKX sliced through its 50-day Moving Average at 136.30, confirming its sell signal.

ZeroHedge interviews the bankers, “”Black Friday” has quickly mutated into red Friday for markets, where panicking traders sell first and only ask questions later if at all. So for those who are too pressed for time to read out primer on the “Scared Nu World”, but want to catch up to speed on consensus, here is a snapshot of analyst kneejrek reactions to the market’s latest obsession.”


WTIC futures, which had back-tested the 50-day Moving Average on Wednesday to confirm its sell signal, plunged below 70.00 this morning.

ZeroHedge observes, “The emergence of ‘nu’ has sparked demand anxiety in the crude complex and oil prices are collapsing.

WTI is down 12% testing below a $70 handle, the lowest in almost months as the smell of liquidation is in the air….

That is the biggest single-day drop since the day WTI traded in negative territory and is near 3 month low, and has broken a key technical level – the 200DMA…”


Posted in Published | 1 Comment

November 24, 2021

8:00 am

Good Morning!

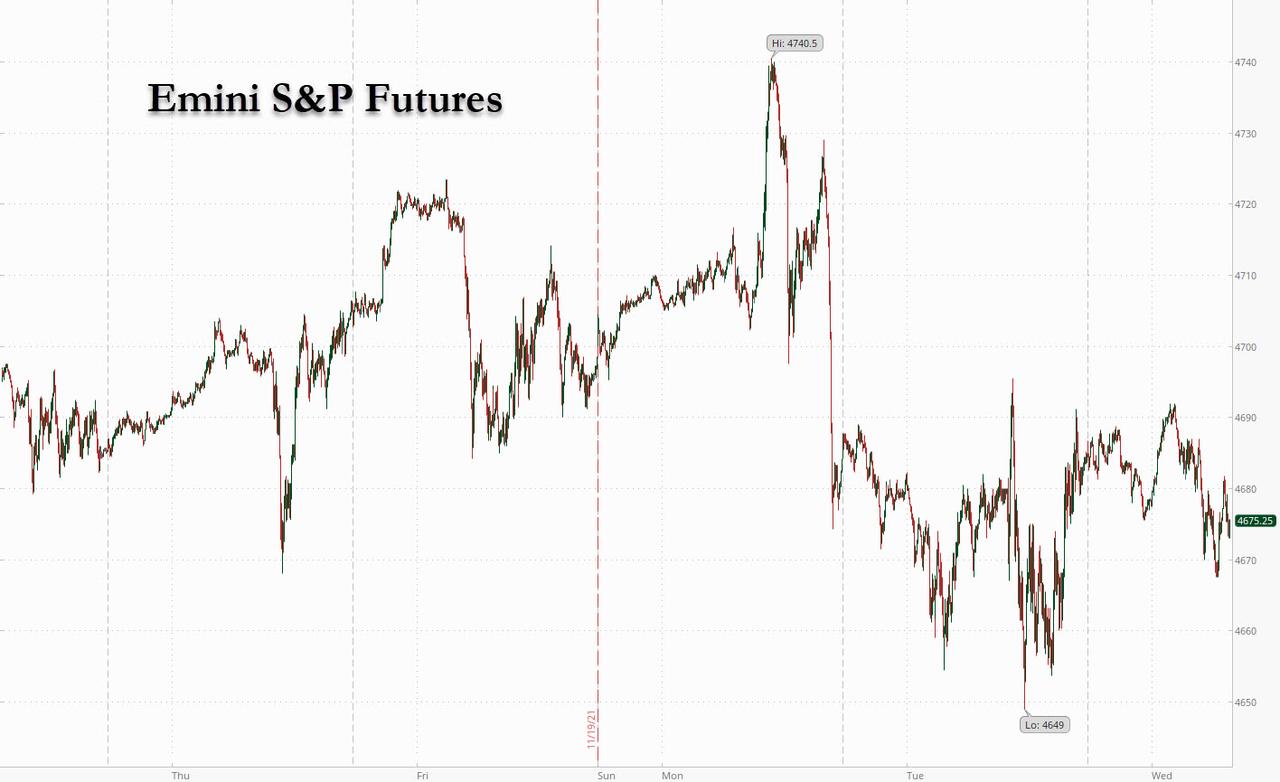
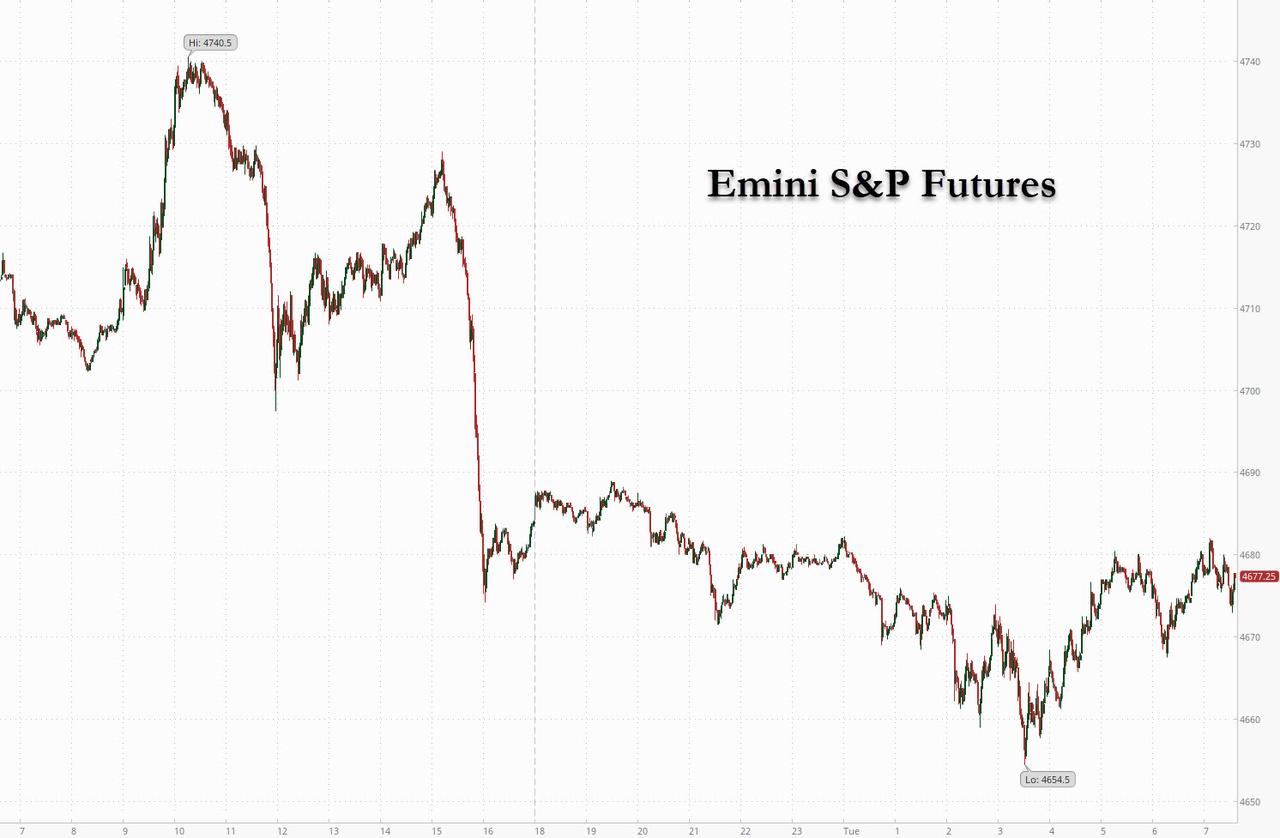
SPX futures have declined to a morning low of 4670.80.  It has already tested overhead (Short-term) resistance at 4689.02 and has since reversed.  Should investors attempt to hold the line at 4652.66, there may be another attempt at Short-term resistance.  Few commentators are worried, although SPX made its closing high on November 18 (day 259) and it’s all-time intraday high on November 22.  From Monday’s high virtually all equities indices made a key reversal, also indicating a probable top.  The Cycles Model indicate a probable 2-month decline into the last week of January.

ZeroHedge reports, “For the third day in a row, US equity futures have been weighed down by rising (real) rates even as traders moderated their expectations for monetary-policy tightening after New Zealand’s measured approach to rate hikes where the central banks hiked rates but not as much as some had expected. Traders also braced for an epic data dump in the US, which includes is an epic data dump which includes an update to Q3 GDP, advance trade balance, initial jobless claims, wholesale and retail inventories, durable goods, personal income and spending, UMich consumer sentiment, new home sales, and the FOMC Minutes The two-year U.S. yield shed two basis points. The dollar extended its rising streak against a basket of peers to a fourth day. At 730am, S&P 500 e-mini futures dropped 0.3%, just off session lows, while Nasdaq futures dropping 0.34%.”


The NYSE Hi-Lo Index made a new low not seen since March 2020.  The Orthodox Broadening Top formation is now being activated to decline to Point 8.  Its average target indicated as many as 80% of all NYSE stocks may make a new 52-week low, possibly by the end of January.  The Cycles Model shows a potentially complex decline with a possible Master Cycle low near December 8.  A potential Christmas rally into options expiration on December 17 is also indicated.  The SPX Cycles do not confirm the Master Cycle low in December, but both agree on the second Master Cycle low in the last week of January.


VIX futures consolidated inside yesterday’s trading range, with a positive result.  VIX peaked 13 (12.9) days from the Master Cycle low and may be due for a pullback to retest resistance (turning to support) at 18.37.  VIX is on a buy signal.


TNX beat yesterday’s high at 16.69 by a point, but may decline for the rest of the week.  We may see TNX revisit the 50-day Moving Average at 15.30 before marching higher next week.

ZeroHedge reports, “After two ugly auctions to start the holiday-shortened week on Monday, when both the 2Y and 5Y auctions tailed badly amid overall poor demand, traders were understandably nervous about the outcome of today’s $59BN sale of 7 year paper: after all, it was the catastrophic 7Y auction back in February that started a cross-asset rout in both bonds and stocks which lasted for weeks and led to billions in losses across various macro investors.

In retrospect, there was no reason to be nervous because moments ago the Treasury announced that the 7Y auction priced at a respectable 1.588%, which while the highest since Dec 2020 as expected, stopped through the When Issued 1.598% by 1 basis point – this was the first stop through since June, and followed four consecutive tailing auctions.

The Bid to Cover was just as solid, rising from 2.245 in Oct to 2.424, the highest since August 2020, and well above the recent average of 2.305.”


USD futures made a new high at 96.88 in the overnight session.  There may be a brief revisit of the Cycle Top support at 95.34 by the weekend as activity takes a breather in the markets.  However, new strength emerges new week that may last to the middle of January.


The GSCI Ag Index continues its rise toward its April high at 474.12.  A breakout is likely, as the Master Cycle may continue higher until mid-December.  A possible minor pullback over the next few days may be indicated.  However, strength may return in early December through the end of the Master Cycle.

ZeroHedge observes, “The real trouble will start when this year’s energy crisis morphs into next year’s food inflation problem.

We’ve all become armchair inflation experts. And why not? It’s almost impossible for anyone to keep getting it as systematically incorrect as professional economists have done this year.

It’s time for the conversation to move beyond the current obsession with eye-catching headline numbers. That we’re in a global inflation regime of a kind not seen for decades, is beyond doubt.

Interest in supply chains is at a 17-year high, according to Google Trends, but it has become a red herring when it comes to forecasting the persistence of inflation.”


Gold futures are taking a breather after two days of nastiness.  We may see a retest of the 50-day Moving Average at 1793.61, or possibly Intermediate-term resistance at 1805.01.  However, a reaction to this decline may arrive on Friday that will indicate whether a change in sentiment is due, or will the bear continue?  The Cycles Model indicates that the trend may continue until the first week of January.


Posted in Published | Comments Off on November 24, 2021

November 23, 2021

2:36 pm

The NYSE Hi-Lo is now on a confirmed sell.  This is the final piece of the puzzle saying, “go short, young man!”


1:05 pm

SPX is looking weak after it has completed an impulsive decline.  Normally we may see a bounce back to Short-term resistance at 4688.70 by the weekend.  This poses a dilemma for those not having made their move, especially over the holiday-shortened week.  For those who have sold long and gone short, it is time to be patient.  Others, who are waiting for the “right moment” may get whipsawed.  For myself, having made my move, I intend to relax and enjoy Thanksgiving with my family.  I may make a shortened commentary tomorrow, but Friday will be very busy from the word “go.”

ZeroHedge explains, “Something odd happened today. Treasury 10- and 30-year TIPS fell to session lows after the Fed postponed Tuesday’s scheduled purchase operation targeting the 7.5- to 30-year sector until Wednesday.

“Due to technical difficulties, today’s Treasury outright purchase operation – scheduled for 10:10 AM in the TIPS 7.5 to 30 year sector for up to $1.075 billion – is being rescheduled,” Federal Reserve Bank of New York says.

“It is now scheduled to take place Wednesday, November 24, 2021 at 11:00 AM,” New York Fed says Tuesday on its website

TIPS prices fell quickly on the news…”


12:30 pm

Yesterday morning I reminded that gold was on a sell signal.  Well. here it is.  Today gold declined further to 1781.85, beneath the 50-day Moving Average at 1790.83.  The sell signal may continue through early January with a likely test of the Head & Shoulders neckline at 1675.00.  Pundits aren’t happy.

ZeroHedge notes, “Good Morning. Monday morning saw a massive sell order hit the Gold futures market with almost reckless abandon. While no-one who is speaking knows why the market acted this way, we do know that it was one of three type players. It always is.

Someone Sold $2.2 Billion of Gold in 2 minutes Monday…” 


7:45 am

Good Morning!

SPX futures are wobbling around the close after declining to an overnight low of 4658.10.  It has made a “Key Reversal” by making a new all-time high, then closing beneath Short-term support at 4688.68 and the Wave (5) trendline at 4725.00 for an aggressive sell signal.

My original thought was that the SPX might flash crash after the November 8 high, then make a comeback to new all-time highs through January.  It appears that this assessment was premature.  The uptrend from March 23, 2202 now appears complete.  The Cycles Model now posits that a 2-month decline awaits the SPX ending in the last week of January.  Should that be the case, it is possible that the SPX may decline to “Point 6” of the Orthodox Broadening Top near 2100.00.  In order to do that, SPX must decline beneath the bold trendline near 4400.00 in the next few weeks.  Fasten your seatbelts.

ZeroHedge reports, “US equity futures continued their selloff for the second day as Treasury yields spiked to 1.66%, up almost 4bps on the day, and as the selloff in tech shares spread as traders trimmed bets for a dovish-for-longer Federal Reserve after the renomination of Jerome Powell as its chair. At 8:00am ET, S&P futures were down 2.75 points or -0.05%, with Dow futures flat and Nasdaq futures extended their selloff but were off worst levels, down 41.25 points or 0.25%, after Monday’s last-hour furious rout in technology stocks.


VIX futures broke out above its November 10 high, rising to 20.83.  It is officially on a buy (SPX sell) signal.  The next resistance appears to be the Cycle Top at 23.40.  VIX has two upcoming Master Cycles, the first in the last week of December and the second at the end of January, while SPX only has the second.  Tis may make for some interesting volatility patterns through the year end.


The NYSE Hi-Lo Index closed at 6.00 after rising to 93 at mid-day.  The item that apparently throws off the Hi-Lo count intra-day is that ETFs may be included, double and triple counting the new 52-week highs and lows.  They are taken off the count after the close, so intra-day measures may be misleading.

Yesterday’s close was low enough to count as a sell signal, pending today’s open.


NDX futures declined to 16276.60 this morning, crossing beneath the trendline at 16350.00 and giving a potential sell signal.  It also made a huge Key Reversal, indicative of a potential change in trend.


The NDX Hi-Lo Index plunged to new lows not seen since March of 2020, confirming a sell signal.  The Hi-Lo Index was negative since last week, despite making new all-time highs.  Tis indicates a lack of confidence in all but the mega-caps.


TNX has broken out above the previous November high and may be overtaking the October high, as well.  The Cycles Model suggests a continued rise in rates through January options expiration.

ZeroHedge observes, “Investors are fretting over the prospect of a “Fed Taper,” but history shows such will likely be good news for the bond market. Currently, it doesn’t seem that way, with rates rising post-announcement. As noted by CNBC:

“While the Fed has gone into policy retreat before, it has never pulled back from such a dramatically accommodative position. For the past eighteen months, it bought at least $120 billion of bonds each month, Such provided unprecedented support to financial markets that it now will walk back.

The bond purchases have added more than $4 trillion to the Fed’s balance sheet which now stands at $8.5 trillion. Roughly, $7 trillion of which is the assets bought up through the Fed’s quantitative easing programs. The purchases helped keep interest rates low. Such provided support to markets that malfunctioned badly during the pandemic, and fueled a powerful run for the stock market.”

Previously, when the Fed began to taper their bond-buying programs, the market buckled as the “risk-on” trade reversed.”


USD futures rose to 9662 in the overnight market before a brief pullback that may last to the end of the week.  Thereafter, a surge of strength is indicated through the month of December.


Posted in Published | Comments Off on November 23, 2021

November 22, 2021

12:45 pm

NDX also made a new all-time high, then threw a tantrum.  The trendline lies at 16400.00.  No signal yet, but its time to be alert.

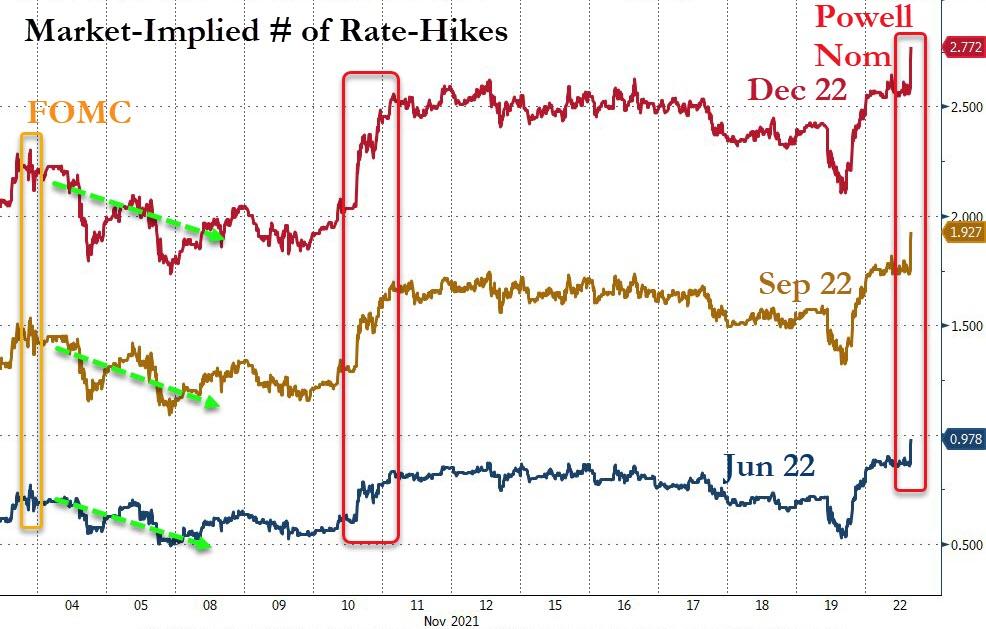
ZeroHedge remarks, “Update (1200ET): After Powell’s nomination, and a tailing 2Y Auction, it appears a combination of spiking yields and hawkish rate expectations finally triggered a tantrum in stocks.

STIRs are pricing in a full rate-hike by June 2022…

2Y Yields spiked to new cycle highs…”


12:37 pm

SPX made a new all-time high, then challenges the trendline at 4700.00.  A breakdown here may give a SPX sell signal.  Confirmation lies below Short-term support at 4688.22.  Critical support lies at the 50-day Moving Average at 4513.62.


12:29 pm

TNX has broken above Intermediate-term resistance.  It is on a buy signal through late January 2022.

ZeroHedge reports, “In a bizarre day for risk assets, one where stocks surged to a new all-time high promptly after the start of trading only to fade all gains and push the Nasdaq into the red, moments ago the Treasury sold $58BN in 2 year paper in a very poor, tailing auction, which was a mirror image of last month’s stellar 2Y sale which only saw tremendous interest due to the buying frenzy by shorts who needed physical paper to offset their futures shorts.

In any case, today’s 2Y auction priced at a high yield of 0.623%, was well above last month’s 0.481% and tailing the When Issued 0.612% by 1.1bps. This was the biggest tail since Feb 2020 when the economy was about to implode.

The Bid to Cover was also ugly, sliding sharply from last month’s 2.686 to just 2.358% and far below the 6-auction average of 2.56.”


8:10 am

Good Morning!

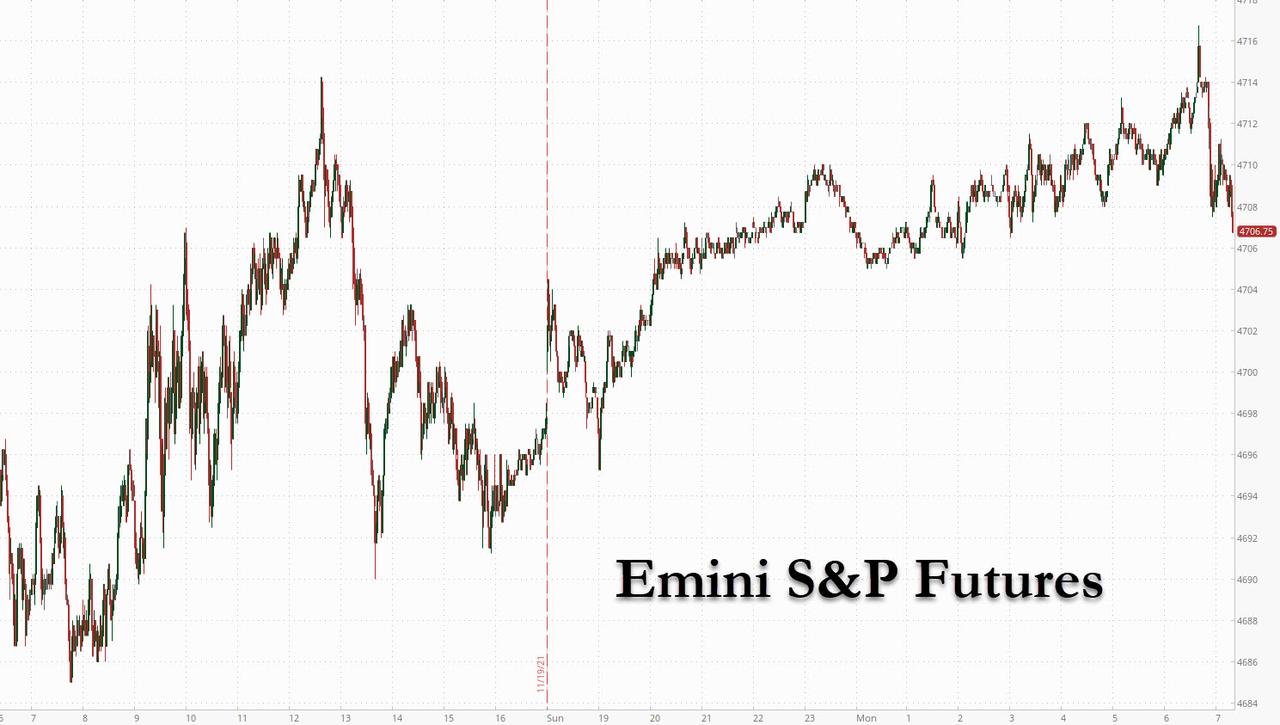
SPX futures rose to 4719.50 (possibly a typo, since corresponding data shows 4717.50) over the weekend session.  Futures have since come down from their high.  SPX closed just under 4700.00 on Friday, leaving the holders of options at a strike of 4700.00 or higher penniless.  That was grand theft of a legal variety on a massive scale.

That leaves Thursday, with a closing price of 4704.54 as the Master Cycle high on day 259.  It was a brilliant maneuver, keeping players glued to their positions with the “hope” of a higher market at expiration.  This week we may see a sell-off as dealers and hedge funds offload their long positions.

ZeroHedge reports, “US equity futures and European markets started the Thanksgiving week on an upbeat note as investors set aside fear of surging inflation and focused on a pickup in M&A activity while China signaled possible easing measures. The euphoria which lifted S&P futures up some 0.5% overnight and just shy of all time highs ended abruptly and futures reversed after German Chancellor Angela Merkel said the Covid situation in the country is worse than anything so far and tighter curbs are needed. At 730 a.m. ET, Dow e-minis were up 95 points, or 0.26%. S&P 500 e-minis were up 12.25 points, or 0.26% and Nasdaq 100 e-minis were up 58.75 points, or 0.357%.”


VIX futures have risen just under the 50-day Moving Average at 18.39, the trendline and the mid-Cycle resistance at 18.44.  The morning high so far was 18.34.  Be prepares for a VIX buy signal.  The Cycles Model suggests rising volatility for the next two weeks is possible.  We may need to monitor it for a breakout above the Head & Shoulders neckline.


The NYSE Hi-Lo Index closed on a potential sell signal on Friday at -19.00.  An opening value in single digits or below zero would alert us to the fact that lower prices are coming.  The fly in the ointment is that Friday was day 253 of the Master Cycle.  Today is day 256.  We may see a bounce soon that may negate the signal.  What comes to mind is a potential 1–2 day volmageddon that shakes out the weaker hands before a resumption of the bull market into late January.  Should SPX stay above 4000.00, the market may continue higher.


TNX is rising, challenging Intermediate-term resistance at 15.74.  It made a 54% retracement of its rally off the MC low and may be prepared to make new highs.  The Cycles Model suggests a continued rally through the third week of January.


USD futures consolidated inside Friday’s trading range as awaits further developments in TNX.  The next resistance to the rally appears to be near 98.00.  The Cycles Model projects a continued rise in the USD until mid-January.


Gold futures made a new low at 1828.50 during the weekend session.  It is on a sell signal with a declining outlook through the first week of January, according to the Cycles Model.


WTI futures declined to a weekend low of 74.83 as it probes lower.  Today is day 259 of the Current Master Cycle.  We must be alert to a reversal which may be imminent.


Posted in Published | 10 Comments

November 19, 2021

7:45 am

Good Morning!

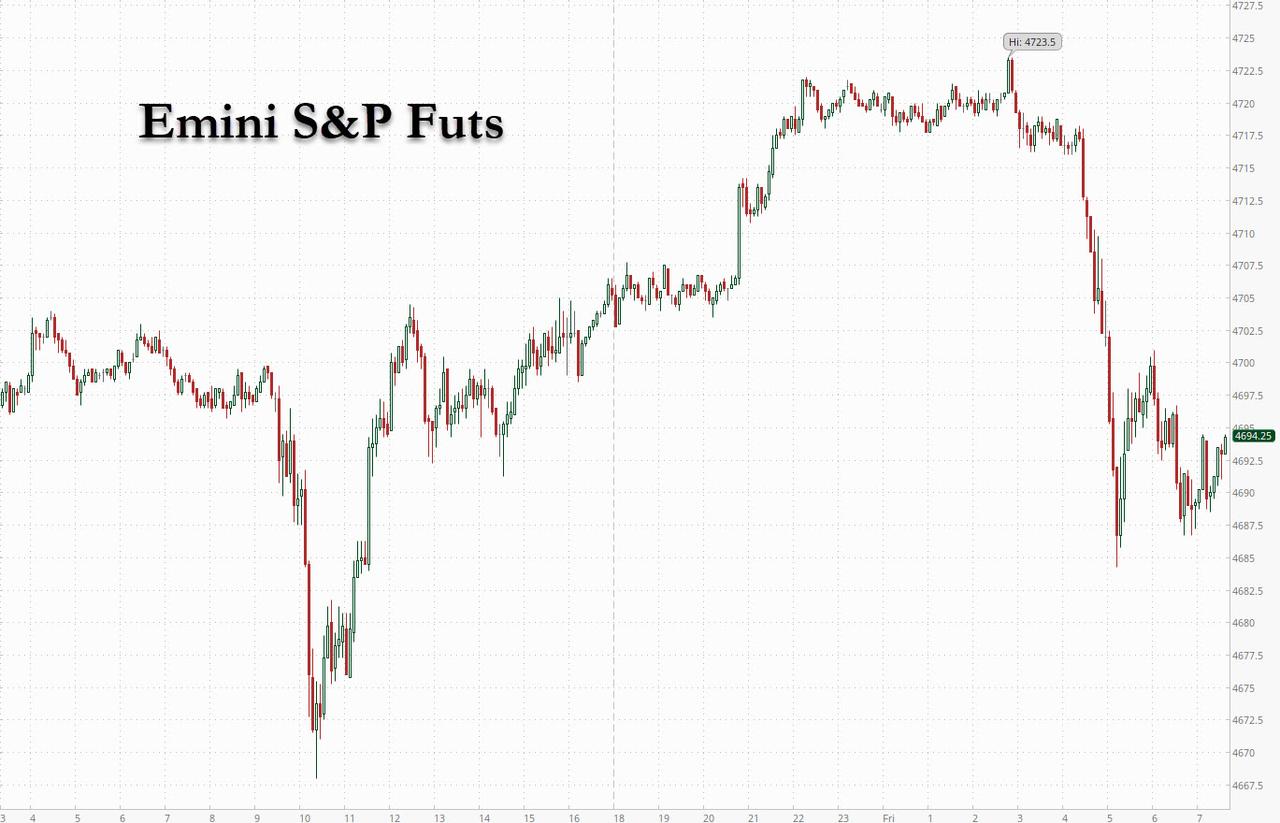
SPX futures touched a new high of 4727.20 overnight, but are sinking away from the gamma-laden options strike at 4700.00 this morning.   The morning low was 4688.40 thus far.  Today is day 260 in the old Master Cycle with the intra-day high on November 5, day 246 at 4718.50.  By all reckoning, thus far in the cash market November 16 may be called a failed MC high at 4714.95.  However, the closing high on November 16 was 4700.90,  higher than the 4697.53 on November 5.  Needless to say, this top has been chaotic.

Open interest at the 4675.00 level is light, while open interest  in SPX puts at 4650.00 is 21,506 vs. 13,464 calls.  The big hurdle is this fternoon’s SPY options with open interest of 90,587 calls at the 470.00 strike vs. open interest of 40,048 put contracts.  The Max Pain zone for SPY is 467.50.  Should SPY fall beneath that level, put gamma may dominate the market.  Wall Street appears to have an “excuse” for its behavior.

ZeroHedge reports, ” Having briefly touched new all time highs of 4,723.5 overnight, S&P futures tumbled shortly after Europe opened as a fourth wave of the pandemic in Europe resulted in a new lockdown in Austria and the prospect of similar action in Germany wiped out earlier gains and forced stock markets down close to 1% as it overshadowed optimism about corporate earnings and the economic recovery. Friday is also a major options-expiry day, which could trigger volatility in equities. Two progressive Democratic senators said they oppose the renomination of Federal Reserve Chair Jerome Powell to a second term, because he “refuses to recognize climate change” joining Elizabeth Warren in urging President Joe Biden to choose someone else.

S&P and Dow futures fell tracking losses in banks, airlines, and other economically sensitive sectors. Uncertainty over rising inflation and the Federal Reserve’s tightening also kept demand for value stocks low. At 745am Dow e-minis were down 218 points, or 0.609%. S&P 500 e-minis were down 12.25 points, or 0.26% and Nasdaq 100 e-minis were up 68 points, or 0.41%.”


The NYSE Hi-Lo closed at 10 yesteday, on the verge of a sell signal.  An open beneath 0.00 may confirm the sell signal.  The Hi-Lo Index reveals a quiet withdrawal out of equities that has not been clear in the price action to date.  Today may be the turning point, as may be indicated in the Hi-Lo.


VIX futures rose to 19.01 this morning, giving us a buy (SPX sell) signal.  That, along with a potential confirmation from the Hi-Lo may give us the confidence to sell/short equities.

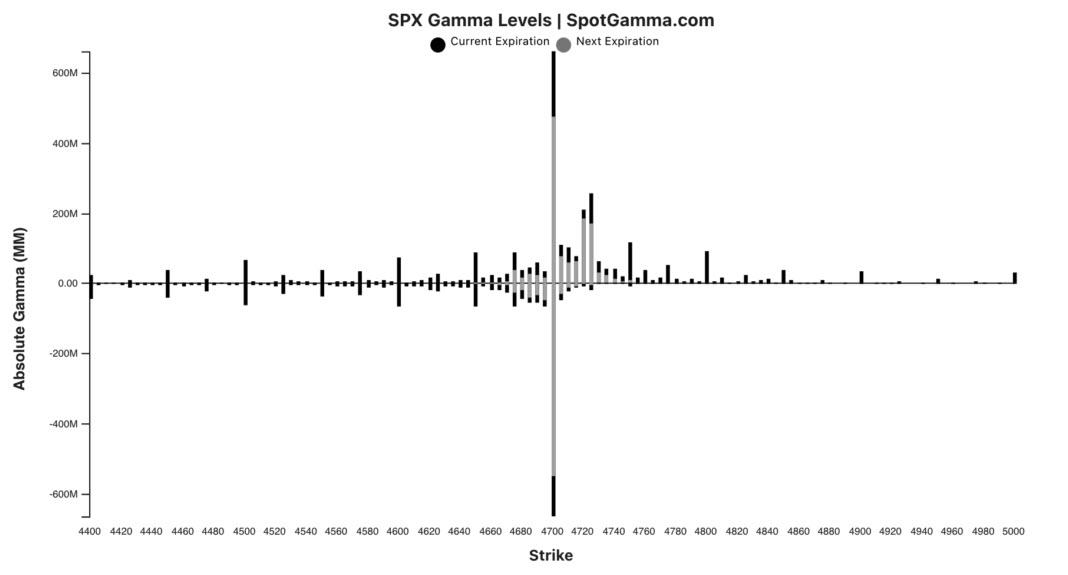
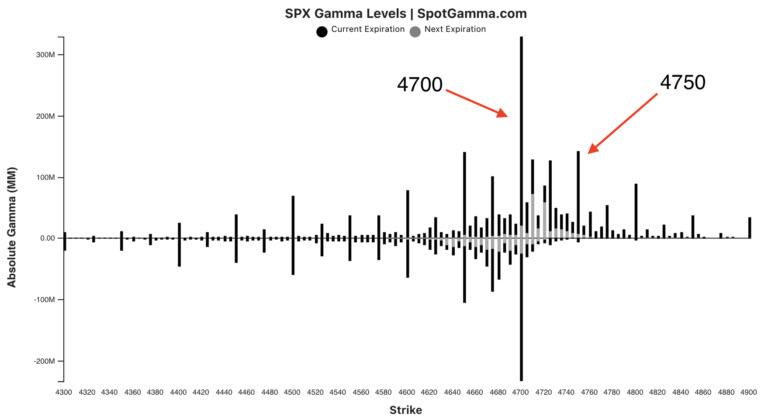
ZeroHedge remarks, “Today’s “elephant in the room” for traders is the fact that 41% of SPX gamma expiring today. As SpotGamma notes, that is a very large number, and may invoke some unexpected volatility today. As we chronicled extensively the past week, we certainly think it will spur volatility next week.

The chart below shows the current distribution of gamma across strikes in SPX, and its rather remarkable.

We cannot recall seeing such a concentration at a single strike before – and this is the result of 18k calls and 23k puts to the 4700 strike.”


TNX declined this morning, approaching the 50-day Moving Average at 15.11, with a secondary target  being mid-Cycle support at 14.92.  This move may be more of an “automatic” migration from stocks to bonds than a reversal in trend.  The move thus far is a 51.5% retracement with a 61,8 Fib retacement at 15.03.


USD futures consolidated in place during the overnight session.  There is room to retest the Cycle Top support at 95.10 before moving higher.  The Cycles Model suggests a continued rally trhrough mid-January.


Crude oil declined to an overnight low of 75.88, well below the 50-day at 78.10.  It is on a sell signal with the current Master Cycle having two more weeks to go.  The Cycles Model suggests a decline to the Cycle bottom may be in order.


Posted in Published | Comments Off on November 19, 2021

November 18, 2021

11:00 am

The Banking Index, proxy for market liquidity, has finally declined beneath Intermediate-term support at 138.44.  BKX declined beneath its Cycle Top support on November 3, but stayed glued to it for almost two weeks.  Today its departure signals a confirmed sell signal, suggesting liquidity may be draining out of the market.

ZeroHedge suggests that market observers are still caught in a “straight line” thinking process, “Being ‘rationally irrational’ one more time

It’s no longer a secret that markets are irrational due to central bank action, and where we see suggestions of less action, they are increasingly volatile. This is taken as a bad thing because we prefer markets under conservatorship, like poor old Britney Spears was until recently. (“Get out there and perform, stocks/yields!”) The establishment loves hearing “Oops, I did it again” and/or “Hit Me Baby One More Time,” and it is rationally irrational to do so given the money keeps flowing to them. Other headlines today also show the same rationally irrational thinking.”


10:55 am

SPX hsd broken away from the trendline, giving us an aggressive sell signal.  confirmation comes at the crossing of Sort-term support at 4672.93.

ZeroHedge observes, “As we contemplate next week’s ‘quiet’ Thanksgiving week, ahead of tomorrow’s options expiration, traders are bracing for the now ubiquitous volatility storm that occurs on the 3rd Friday of the month… and this one will be a doozy!

Bloomberg notes, the total number of outstanding contracts on equity, index and ETF options expiring stands at 95.5 million, a hair away from 95.6 million in July, data compiled by Susquehanna International Group’s Souhow Yao show. That was the most for any month ever, when excluding the expiration of quarterly options or the so-called long-dated options, or LEAPS, that have been listed for longer and accrued a higher open interest.”


7:50 am

Good Morning!

SPX futures rose to 4707.40 this morning without making a new high, but keeping the call options fully funded at maximum gamma.  Today is day 259 of the Master Cycle, the second highest “hit” after day 258 for the Master Cycle.

Tomorrow’s options expiration show the Max Pain zone in the SPX at 4650.00.  However, the index options implying institutional involvement are light, indicating a waning interest.  However, the (retail) SPY options show an open interest in 282,000 call contracts vs 99,000 put contracts above 467.50, its Max Pain level.  By the way, the number of (SPY) put contracts are rising, with less than 70,000 put contracts above 467.50 earlier this week.

ZeroHedge reports, “U.S. index futures rose again, trading on top of the massive 4700 “max gamma” level despite downbeat data out of Chinese tech names, as investors awaited the latest batch of unemployment data and taking comfort from signals that central banks will stay far behind the curve and keep pledges to overlook faster inflation rather than rush into rate hikes.”


The NYSE Hi-Lo Index closed below 30.00 for the first time since October 12 as institutional investors quietly leave the market.  While we await a reading below 0.00 to have a sell signal, this number raises the cautionary flag on market participation.


VIX futures eased down to 16.654 this morning as it consolidates (coils) beneath overhead resistance at 18.53.  Some traders will accumulate shares after the first breakout above resistance, as the probability of going higher is elevated.  Others wait for the “sure thing,” the second breakout above the resistance level.  The “failed” Master Cycle low on November 17 indicates the opportunity for accumulating shares at a lower level.


TNX (futures) made a low at 15.74, near Inttermediate-term support at 15.71 this morning.  It is possible that a Trading (short-term) Cycle may have been made, allowing TNX to continue its rally.  If so, TNX may have made a “running correction, where the bottom of Wave (c) is higher than the top of Wave (a).    The Cycles Model suggest a continued rally to January options expiration.

ZeroHedge comments, “In the usual post-FOMC meeting jawboning circus, today we had not one but two Fed officials discussing not the topic du jour – Fed policy errors and soaring inflation – but something far more ominous: the broken Treasury market. Just days after a catastrophic 30Y Treasury auction which may well be the harbinger of what’s to come as the market realizes that i) tapering is tightening and that without the buyer of first resort we will finally get some price discovery and ii) inflation, contrary to the latest Fund Manager Survey, is not transitory, both Cleveland Fed president Loretta Mester and NY Fed president John Williams warned markets that the Treasury market is “not as resilient” as it should be, and that even modest stress could break it. Unfortunately neither of them admitted that it’s entirely the Fed’s fault that what was once the world’s most liquid market has become a political tool to be abused by central planners and power hungry politicians.”


USD futures pulled back to 95.65 in a short-term consolidation.  The USD may continue to rise with treasury rates through the end of the year, per the Cycles Model.

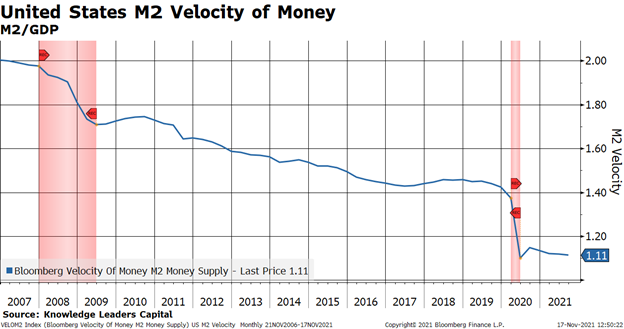
ZeroHedge observes, “A basic tautology that economists consider when thinking about monetary policy is the velocity of money. MV=PQ translates into Money*Velocity=Price*Quantity. Of course, price*quantity is nominal GDP while “M” is the money supply (for example, M2) while “V” is velocity, or the number of times the money supply turns over. A prominent feature of the post-Great Financial Crisis period has been the persistent decline in velocity, which is why the Fed has had to pump so much money into the system for so long. Absent an increase in the money supply, the drop in the velocity, all else equal, would have likely been the backdrop for a long recession.
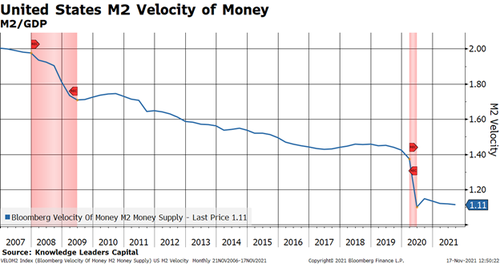
But, it appears that the decade of falling velocity may have ended. Bank loans have made a strong turn upward since June.”


The GSCI Ag Index continues its rally to a potential breakout above its May high to new highs not seen in over 8 years.  A potential overhead resistance level occures at 570.50, its March 2011 high.  It is possible that it may reach that level by mid-December, its next Master Cycle interval.

ZeroHedge reports, “Cargill CEO David MacLennan has changed his mind about “transitory” inflation and now believes it will be more persistent with higher food prices in 2022. He blamed elevated food prices on snarled supply chains, labor shortages, and adverse weather conditions, among other things.

MacLennan highlighted that labor shortages are a significant challenge for the food industry. He said food processing plants across the country operate at less than full capacity, which drives down food output and prices higher as demand remains robust.

“I thought inflation in ags and food was transitory. I feel less so now because of continued shortages in labor markets,” MacLennan said during an interview at the Bloomberg New Economy Forum in Singapore. “That’s one of the inputs to the supply chain that we’re watching most carefully.” 

ZeroHedge also comments, “The era of cheap meat is over.  For those that are carnivores, that is really bad news.  For decades, Americans have been able to count on the fact that there would always be mountains of very inexpensive meat at the local grocery store, but now those days are gone and they aren’t coming back.  As I was writing this introductory paragraph, it struck me that what is happening to meat prices actually parallels what I wrote about yesterday.  Just as the left doesn’t want us to use traditional forms of energy because they believe that doing so is “bad” for the climate, so they also detest that a lot of us like to eat a lot of meat because the production of meat causes levels of certain greenhouse gases to rise. ”


Gold futures continue to consolidate after making its Master Cycle high on Tuesday, day 253.  There’s nothing like a a pullback after a “breakout” to get the bullish juices roaring.  Unfortunately, as the USD rises into the new year, gold may be on the decline.  Sorry, Jim!

ZeroHedge comments, “This is getting ridiculous. And that’s a good thing.

By “this,” I mean the price of gold, and by “ridiculous,” I mean repetitive to the point of absurdity. That’s OK. The prospects for gold from here are highly positive.

By now, readers are tired of my description of gold trading as range-bound between $1,700 per ounce on the low side and $1,900 per ounce on the high side, with $1,800 per ounce as the central tendency. That’s completely accurate but also highly repetitive, since it has held true with only brief and minor exceptions for the past year.”



Posted in Published | 1 Comment

November 17, 2021

3:10 pm

TNX has settled down to its session low after the Treasury auction this afternoon.  It may retest its Intermediate-term support at 15.67 before resuming its rally.

ZeroHedge observes, “After last week’s catastrophic 30Y auction, traders were keeping a close eye on today’s sale of $23BN in 20Y bonds to see if it too would suffer from lack of demand following last week’s historic CPI print.

As Bloomberg’s Alyce Anders wrote ahead of the auction, the Fed and the Treasury “have done everything they can to support the doggy 20-year sector. The lack of a concession today and a well advertised relative value set up might mean the $23 billion offering should go fine even if it tails. That’s because the government cut its issuance size and the Fed left its new purchase schedule for 10-year to 22.5-year Treasuries untouched despite tapering Treasury buybacks by $10 billion per month.”


3:03 pm

If this Wave count is correct, we should see some downside in the final hour.  An aggressive sell signal lies beneath Short-term support at 4669.79.

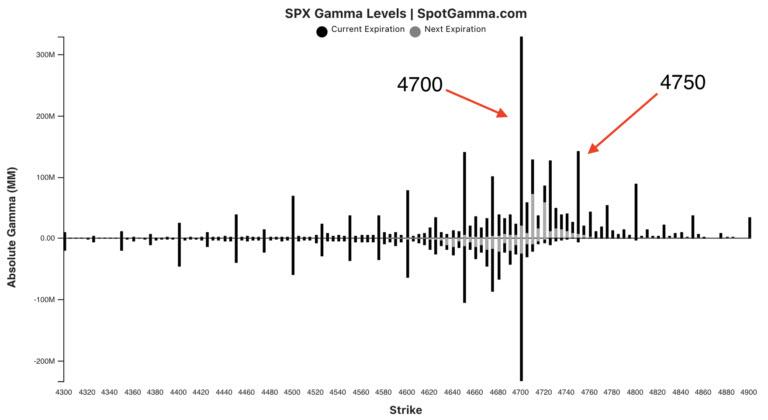
ZeroHedge observes, “Goldman’s quadrupling down on its year-end meltup call has been spot on so far, and the S&P overnight gravitated back up to the 4700 strike which continues to house the most $Gamma on the board at $8.8B, followed by the 4750 strike with $6.7BN.

And, as Nomura’s Charlie McElligott reminds us, heading into Friday’s op-ex, SPX/SPY Net Delta is 99.9%ile (since ’13)…”


8:00 am

Good Morning!

SPX futures made an overnight high of 4704.90 as it “stays in place” on day 258 of the Master Cycle.  Thus far, yesterday’s high at 6714.95 may be the best candidate for the Master Cycle high.  Today 4700.00 appears to be the Max Pain zone with calls dominating at 4710.00 and above and puts dominating at 4680 and below for options at the close of the day.

Friday, on the other hand, is a different problem.  Calls dominate the options expiry all the way down to 4600.00.   Max Pain is a 4595.00.  That would damage the technical landscape, since the Ending Diagonal trendline is at 4675.00 and Short-term support (aggressive sell signal) is at 4662.32.   The way I see it, a Friday close at 4700.00 would cause a lot of dealer pain, while a close beneath 4600.00 would give them an enormous profit.

While SPX is very close to making a new high, NDX and the DJIA are not, unless the enormous “pull” of the calls causes a melt-up to bring all the indices in line.  In March 2000, the SPX and NDX made new all-time highs while the DJIA limped along to a secondary high.  Today’s scenario could be compared to such a case.

ZeroHedge reports, “Price action has been generally uninspiring, with US index futures and European stocks flat after UK inflation climbed faster than expected to the highest in a decade, heaping pressure on the Bank of England to raise interest rates, while Asian markets fell as investors fretted over early rate hikes by the Federal Reserve after strong retail earnings dented the stagflation narrative.  Ten-year Treasury yields held around 1.63% and the dollar was steady. Cryptocurrencies suffered a broad selloff, while oil extended losses amid talk of a coordinated U.S.-China release of reserves to tame prices. Gold rose. At 7:30 a.m. ET, Dow e-minis were down 14 points, or 0.04%. S&P 500 e-minis were up 1.25 points, or 0.0.3% and Nasdaq 100 e-minis were up 24.75 points, or 0.15%, boosted by gains in Tesla and other electric car-makers amid growing demand for EV makers.

At 8:21 am ZeroHedge reports, “Too much of a good thing…

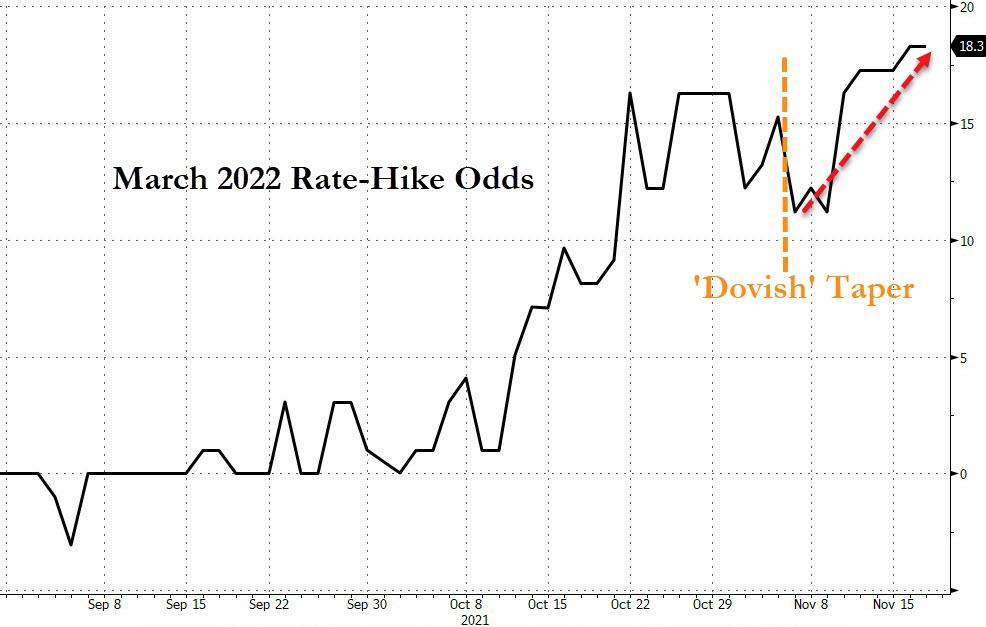
STIRs are continuing their hawkish trend, with the market now pricing a 19% chance of a rate-hike as soon as March 2022…

US Treasury yields are on the rise again this morning, with 30Y yields breaking out to one-month highs…”


VIX futures moves higher, but still within yesterday’s trading range.  Today is day 258 of the VIX Master Cycle and possibly the last day for a new low, due to monthly options expiration for the VIX.  MAX Pain in the VIX options is at 22.00 with puts dominating beneath that level.  This could be a very interesting day.


TNX moved higher this morning, setting off jitters in the equities market.  The Cycles Model suggests rising rates through Janusry options expiration.

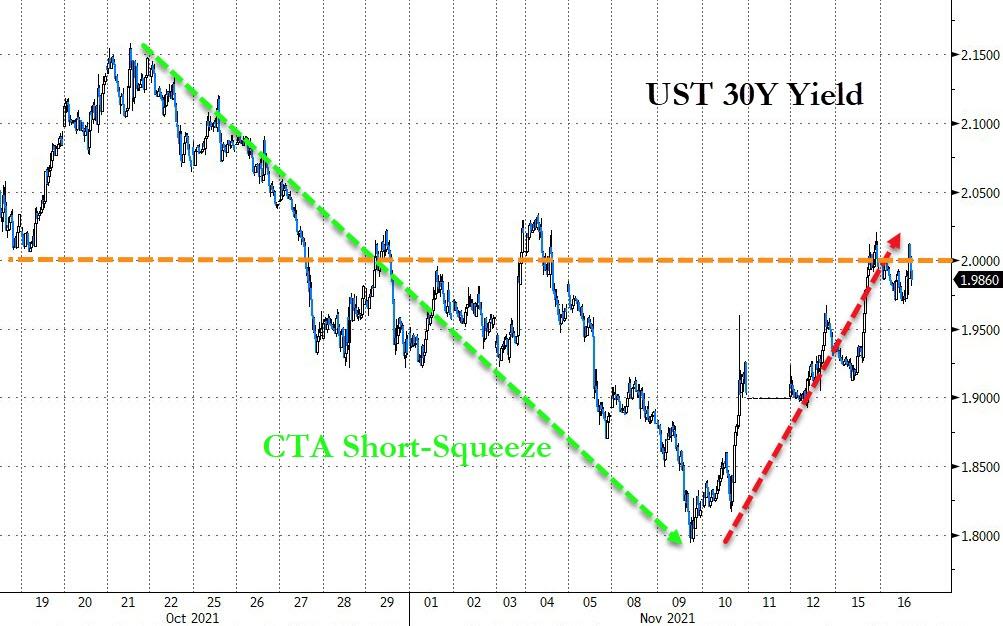
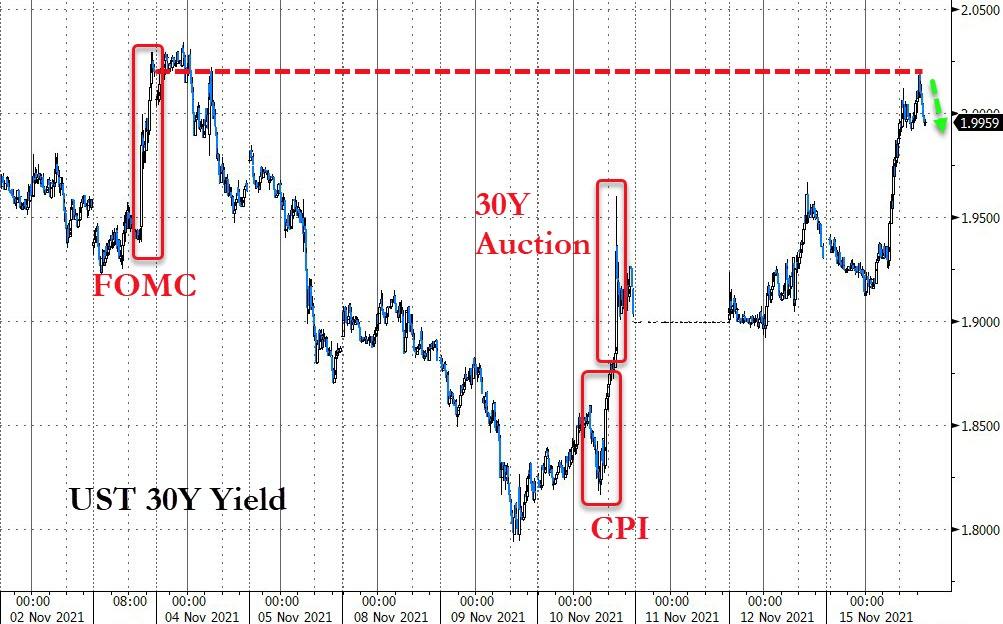
Yesterday, ZeroHedge pointed out, “30Y Yields are back above 2.00% this morning, with rates having jumped notably in the last few days…

Nomura’s Charlie McElligott notes that, after the three week rolling squeeze in bearish fixed-income / underweight duration trades (helped by the epic global CB “rug pull” on prior hawkish rhetoric) has now allowed for resetting of shorts as the buy impulse fades…particularly from Systematic Trend.”


USD continued its melt-up to 96.27 this morning.  The Cycles Model suggests a continued rise in the USD through mid-January.


Gold futures made a partial retracement of yesterday’s decline on day 254 of the Master Ccyle.  This may set the stage for a definite change in trend after a complex sideways consolidation over the past year.  The Cycles Model suggests a decline through the first week of January.  The Triangle formation forecasts the final move before a reversal.  This may be the reversal, not a breakout.

ZeroHedge comments, “Gold’s huge break out

Gold broke out of the huge triangle like formation that has been in the making for a long time. Time for a technical thread. The first obvious observation is that the shiny metal is well above the negative trend line and that the 200 day moving average is not sloping downwards anymore. The short term move has of course been powerful and gold is now somewhat overbought, but the price action in the recent squeeze is nevertheless interesting. First support we have down at the 1830 level.”


Posted in Published | 2 Comments

November 16, 2021

10:33 am

SPX is  in a tug-of-war between the bulls and the bears with the dealers attempting to keep it near Max Pain at 4685.00.  However, the Cycles Model implies a swift decline in the next week, which affords the least amount of pain and greatest profit for the dealers.   Stocks are approaching their next hourly turn by noon today.  A break of Short-term support at 4657.61 offers the 50-day Moving Average at 4495.55 as the next possible support, should a break take place.


8:15 am

Good Morning!

SPX futures rose to a morning high of 4692.40 before easing down.  The Max Pain zone in the SPX is between 4680.00 and 4685.00.  Index options for Wednesday and Friday are on the light side, suggesting little interest in puts or calls by institutions.  However, SPY (467.23) options are monstrous.  Max Pain in Wednesday’s options is at 467.00 with an abundance of puts at 466.00 (and below) and calls at 468.00 (and above).  So at day 257 of the Master Cycle dealers are walking the tightrope to stay at a limited payout at options expiration.  Friday’s options show Max Pain at 467.00 but with 20,000 net put contracts at 466.00 and 465.00 each.   There are 45,000 more put contractss than calls at 468.00, 17,000 more calls at 469.00 and an open interest at 101,802 calls and 34,597 puts at 470.00.  This is one for the record books.  A slip in either direction may engender massive losses.  Although tomorrow is day 258, it appears that the Master Cycle may not be completely over until the aftermath of options expiration is washed out early next week.

ZeroHedge reports, “US equity futures reversed earlier losses, trading slightly in the green, while bonds were lifted as traders awaited a decision from the White House on who the next Federal Reserve head will be amid speculation Fed policy tightening could be slowed down under Elizabeth Warren’s favorite progressive, Lael Brainard. At 730am, S&P futures were up 1.75 of 0.04%, Nasdaq futures were up 2.75 or 0.02% and Dow Jones futures traded 58 points higher or 0.161%. 10-year Treasury yield retreats back toward the 1.6% level after climbing for three days in a row; the dollar was flat and bitcoin tumbled, briefly sliding below $60,000 on no news, before reversing modestly.”


VIX futures consolidated inside yesterday’s range in the overnight futures.  It has already made a 72% retracement and may be ready for a move up.  The VIX has the same Master Cycle as the SPX, so we may see a high in the next 2-6 days.


TNX is moving higher in what may be one of the strongest rallies of the year.  The Wave structure suggests a minimum move to 19/71, its next overhead resistance.  TNX has 10 weeks left in its current Master Cycle, giving it plent of time to accomplish its goal.

ZeroHedge comments, “For all the kerfuffle in the bond markets last week, valuations are still astronomical.

Last Wednesday, we had a double whammy in the U.S. with inflation soaring and an auction of 30-year bonds seeing the ugliest tail in a decade.

Those factors led to a scrum in rates, but like a flop Broadway musical, it seems to have been a short-run performance.”

[ZH: yields extended today, with 30Y topping 2.00% and tagging stops on the FOMC Taper spike, before fading back below 2.00% into Asian trading.]


Posted in Published | 1 Comment

November 15, 2021

2:27 pm

I made a statement in error this morning.  I claimed that there was no Master Cyce terminus in the next two weeks.  I was wrong.  I tagged the November 5 high as the end of the Master Cycle on day 246.  However, today is day 256 and the targeted date of a possible low is too near options expiration for comfort.  It is possible that the decline to the trendline from March 2020 may be tested on Wednesday November 17 or breached on or near day 262 or 263, early in the week after options expiration.  This implies massive pain for the bullish options punters and a possible $2.6 trillion of “low hanging fruit” for Wall Street.  If you are a trader, you may wish to go aggressively short until Wednesday and see how deep this decline may take us.

Another short seller bites the dust as ZeroHedge comments, “Up until now, “the big short” Michael Burry was best known for periodically and inexplicably nuking his twitter account before promptly restoring it. Now, we can also his investment portfolio to the list of things the famous subprime shorter tends to nuke every now and then.”


8:15 am

Good Morning!

SPX futures have risen to 4699.00 this morning as it completed its corrective phase of the decline.  The hourly Cycles Model suggests a reversal in the first hour of the day.  Otherwise, the SPX may rise to a new all-time high.  Today’s and Wednesday’s options expiration are light, but Friday’s opex is massive, with over 30,000 SPX call contracts at 4700.00.  In all, there are $2.6 trillion maturing calls by Friday, which Wall Street does not want to pay.  This suggests a Wave B decline down to the trendline at 4425.00, or possibly lower duirng and shortly after options expiration.  There is no Master Cycle terminus in the next two weeks, suggesting that the uptrend may be maintained. 

ZeroHedge reports, “US equity futures resumed their upward climb (after Goldman quadrupled down on its call for a massive, year-end meltup driven by $15BN in inflows every single day) as major technology stocks advanced, and as investors awaited a slew of retail earnings and economic data this week to gauge the health of consumer spending while keeping an eye on runaway inflation. Better-than-estimated profit growth has led to a rally in markets, helping ease recent concerns over the hottest U.S. inflation in 30 years. At 730 a.m. ET, Dow e-minis were up 94 points, or 0.26%. S&P 500 e-minis were up 9 points, or 0.20% and about 20 points from their all time high around 4,711; while Nasdaq 100 e-minis were up 30.5 points, or 0.19%.”


VIX futures are rising, suggesting a possible turn may be at hand.  All three overhead resistance levels appear to be converging at 18.85.  A breakout here would propel the VIX up to, and possibly above the Head & Shoulders neckline.  Despite the lack of an SPX Master Cycle, the VIX proposes a possible Master Cycle terminus early next week.  This introduces the idea of a recurring volmageddon, as described below.

CharlesHughSmith observes, “It makes perfect financial sense to crash the market and no sense to reward the retail options marks by pushing it higher.

An extraordinary opportunity to scoop up mega-millions in profits has arisen, and grabbing all this free money makes perfect financial sense. Now the question is: will those who have the means to grab the dough have the guts to do so?

Here’s the opportunity: retail punters have gone wild for call options, churning $2.6 trillion in mostly short-term calls–bets on gains now, not later. This expansion of retail options exposure is unprecedented not just in its volume but in its concentration in short-term bets (options that expire in a few days) and in mega-cap tech companies that are commanding rich premiums for options.”


TNX rose above its Intermediate-term support at 15.59.  However, the Cycles Model shows no strength until the end of the month.  That indicates either a modest rally or a possible further pullback to the 50-day Moving Average at 14.89 before resuming its rally.

ZeroHedge opines, “Un-Orthodoxy

“Rising inflation and growing government debt may not seem like the natural ingredients to lower longer-term real yields,” explained Marcel, our Head of Research, our investment team thinking through the opportunities that arise when the vast majority of people dismiss perplexing market movements as being illogical when in fact, they may reflect a paradigm shift. “Yet here we are – longer-term real yields set a historic low last week. It is not that the market has given up the idea of orthodoxy. To the contrary, inflation is imposing orthodoxy on people’s behavior. Despite low interest rates, high asset prices, and record job openings, consumers believe it is the worst time to buy a car ever and the least attractive time to purchase a home since 1982. Demand is strong. Supply is constrained. Prices gains are required to ration demand. This is orthodoxy, just not the variety we are accustomed to.”


Posted in Published | Comments Off on November 15, 2021