November 9, 2023

3:55 pm

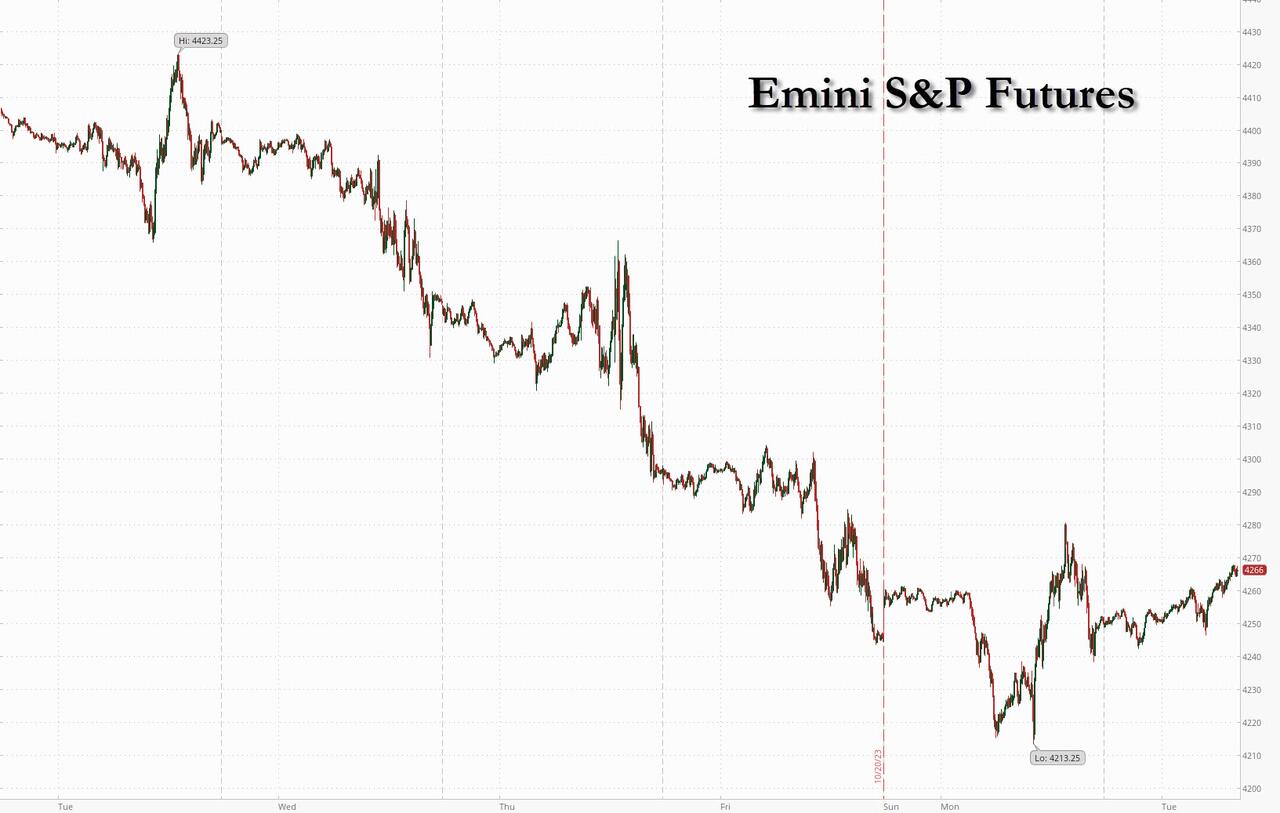
SPX has broken out of the gap, creating an aggressive sell signal.  Once beneath the 50-day Moving Average at 4346.50, the sell signal is confirmed.

ZeroHedge reports, “Complete disaster.

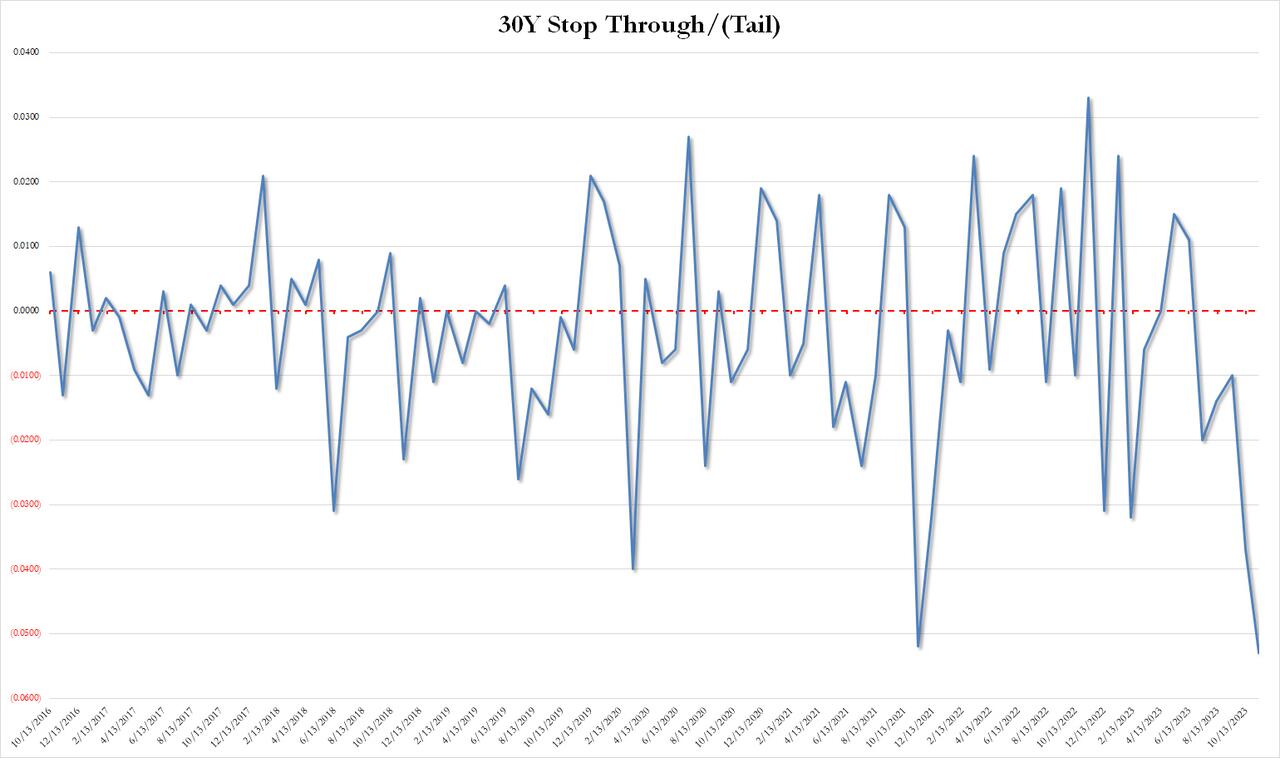
That’s the only way one can describe today’s 30Y auction, which many expected could be challenging after a mediocre 3Y and a subpar 10Y auction earlier this year, but nobody expected… this.

The bond priced at a high yield of 4.769%, which was below last month’s 4.837%, and just shy of the April 2010 high. But more importantly, it tailed the When Issued by a whopping 5.3bps, which was… well… terrible, because as shown in the chart below, this was the biggest tail on record (going back to 2016).”
 

8:15 am

Good Morning!

NDX futures are consolidating just beneath yesterday’s new high at 15343.18.  The new high (above the October 12 high) alters the structure of the Cycles.  Today is day 251 of the existing NDX Master Cycle.  Should the MC high be finalized in the next few days, the new Master Cycle may go immediately into decline lasting to mid-January.  Unfortunately, many investors are influenced by the breakout and being cheered on by dealers who need to sell their book.

Today’s options expiration shows Maximum Investor Pain at 15310.00.  Long gamma starts at 15320.00, but does not have a follow-through.  Short gamma begins at 15310.00 with moderate follow through.

ZeroHedge remarks, “GS repeats: There is no need for a recession

“Despite the good news on growth and inflation in 2023, concerns about a recession among forecasters haven’t declined much. Even in the US, which has outperformed so clearly on growth in the past year, the chart shows that the median forecaster still estimates a probability of around 50% that a recession will start in the next 12 months.This is down only modestly from the 65% probability seen in late 2022 and far above our own probability of 15% (which in turn is down from 35% in late 2022).”

Source: Goldman

2024 will be an “everything up” market

Goldman’s 2024 cross-asset return forecasts. The bull is back.


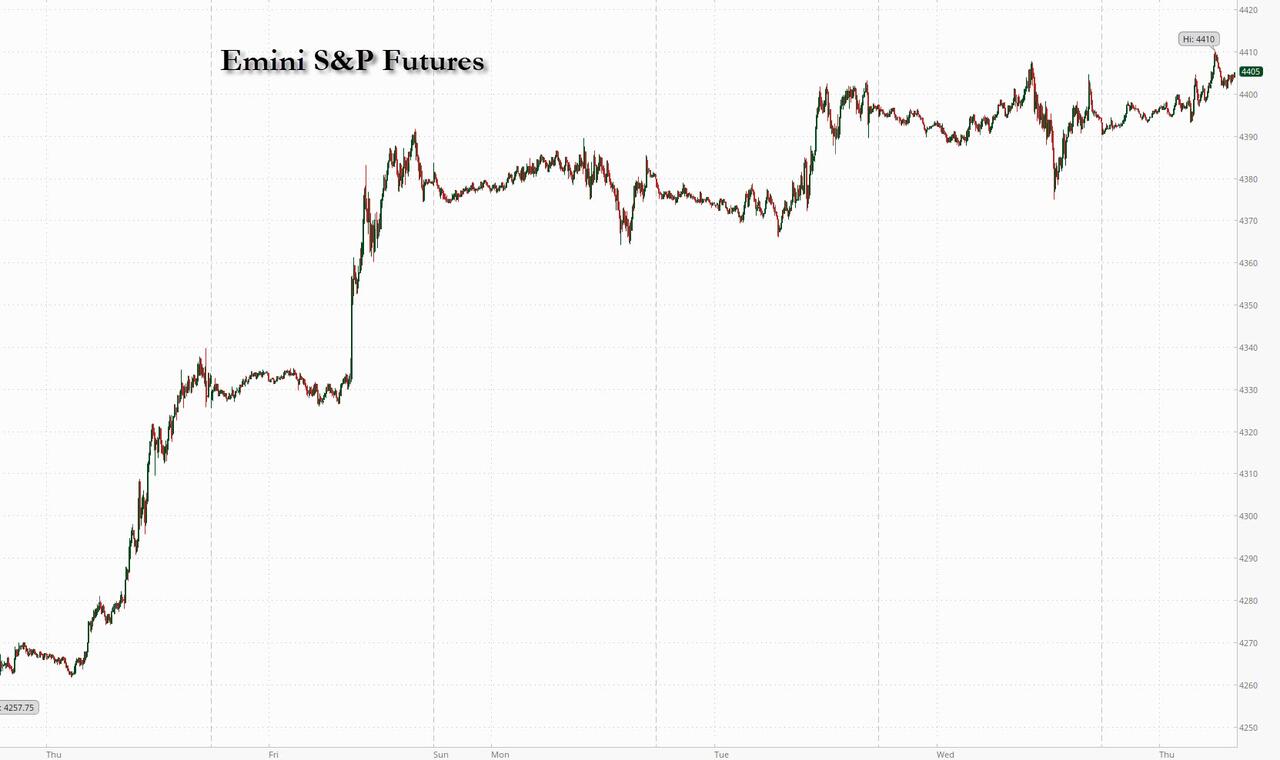
SPX futures climbed to 4394.10, making a new high and altering the Cycle structure.  The correct structure is called an expanded flat, inferring a lower corrective low, but the final (Wave C) high being in proximity to the Wave A high.  The SPX has rallied sufficiently to be complete, once it registers the new high in the cash (daytime) market.  It may not close the gap at 4401.38-4402.20.   It is also in the reversal window for a Master Cycle.  I expect both the NDX and SPX to make their reversal simultaneously.

Today’s op-ex shows high market tension and possible Max Pain at 4370.00-4380.00.  Long gamma starts at 4400.00.  Short gamma begins at 4370.00.

ZeroHedge reports, “S&P 500 futures edged higher on Thursday after notching an eight-day streak of gains, and setting up the benchmark index for its longest winning streak since 2004, as investors monitored bond yields, corporate earnings and the price of oil. Treasuries fell and the dollar rose ahead of more speeches by central bank officials including more remarks by Fed chair Powell. After a listless overnight session, as of 7:45am S&P futures were up 0.1% and Nasdaq was down by a similar amount. Elsewhere, Europe’s Stoxx 600 index rose 0.6%, Asian stocks closed green, oil hovered near a three-month low after plunging almost 7% over the previous two sessions, yields on 10-year Treasuries held below 4.5%, the dollar gained and bitcoin was set to rise above $37,000, an 18 month high.”


VIX futures have made a new low at 14.13 in an expanded correction.  The new Master Cycle is about to begin.  It may last in an historic new high by mid-January.  Nuff said.

Next Wednesday’s op-ex shows Max Pain at 19.00.  Short gamma extends from 13.00 to 17.00.  Long gamma begins at 20.00 and may extend to 70.00.


TNX futures made a low of 44.1while the cash market bottomed at 45.26.  The trading channel trendline appears to be holding TNX, which is deeply oversold.  It may linger near the lows until next week, when trending strength roars back.  The current Master Cycle may resume the uptrend through the end of November.

ZeroHedge observes, “The impressive rally in stocks and bonds over the last week or two is likely to take a breather, with both assets now overbought in the short term.

Bonds have been deeply oversold since last year, but the latest rally to ~4.5% in the 10-year has taken Treasuries to only one standard deviation below their long-term mean growth level (back towards the range they normally inhabited before the extremes of the pandemic).”


Crude oil futures  consolidated above yesterday’s low, but appear poised to make new lows as trending strength may stage a comeback this weekend.  The Cycles Model suggests up to two more weeks of decline, where the Head & Shoulders target may be met.

ZeroHedge poses the question,”Surprising many, the price for crude oil has collapsed in the last few days, with Brent back below $80 and WTI well below pre-Israel-attack lows back at near 4-month-lows…

The question for many is – why, or why now?”


Posted in Published | Comments Off on November 9, 2023

November 7, 2023

2:45 pm

Please note:  I will be absent from this blog for the entire day tomorrow, November 8.  


12:15 pm

On November 3, I mentioned, “SPX is meeting fierce resistance at the September 21 gap beginning at 4375.70 and open to 4401.30.  It spent two weeks trying to overcome it in October, but failed.  Unfilled gaps are powerful resistance points, due to their history of failure, as you can see.  One of the reasons is that most shorts were bought after the gap down, so short covering no longer provides the fuel for SPX to go higher.  On the other hand, you will know a rally has legs when gaps are filled.  That may not happen for a while.”

Today, SPX lurched into the gap, but could not maintain a hold on it.  A failure at the gap (below 4375.00) may be a powerful sell signal.  Those who seek confirmation may wait until the 50-day Moving Average at 4347.71 is breached.

ZeroHedge remarks, “Here we are again, writes Goldman Sachs trader Bobby Molavi.

The market handing out yet another dose of exactly what investors didn’t want.

A dovish, bad news is good news and fed is done (cuts could be coming) mindset which triggered a beta rip that was felt most acute in most shorted, lower quality, higher leverage and duration space.

Macro still rules the roost…and only a week after we hit 5% for 10 year yields…we found ourselves at 4.5% on the back of easing labour markets and slowing inflationary pressure…..only to see this week yields rising once more.”


9:57 am

The Ag Index has risen above its 50-day Moving Average at 396.83, putting it on a buy signal.  The Cycles Model indicates growing strength after completing its Master Cycle low o October 31.  The new Master Cycle may last through late December, giving ample time for a rally with legs.   Harvest season is underway, with mixed results.  Final reports may indicate that food inflation may be back.


9:45am

BKX is declining toward the 50-day Moving Average at 77.94, where a sell signal awaits.  The rally may have provided some relief to bank  investors while lower rates have temporarily eased pressure on bank portfolios.  However, that may change quickly.  Regional banks went all-out selling mortgages when rates were considerably lower.  The pressure to unload those mortgages have widened credit spreads, preventing banks from easing their pain by unloading their mortgage holdings during the crisis.  Now the Federal Home Loan Banks have weighed in with bad news.  See the articles below.

ZeroHedge observes, “The growing divergence between mortgage and credit spreads is highly unusual and counter-intuitive: it’s not obvious why corporates should be getting less risky and mortgages more when rates have risen for everybody. It turns out the ultimate cause is inflation.

It has been said that anyone who says they understand quantum mechanics doesn’t understand quantum mechanics. That applies equally to markets. Just when you think you have a handle on things, a new head-scratcher pops up.”

2:55 pm

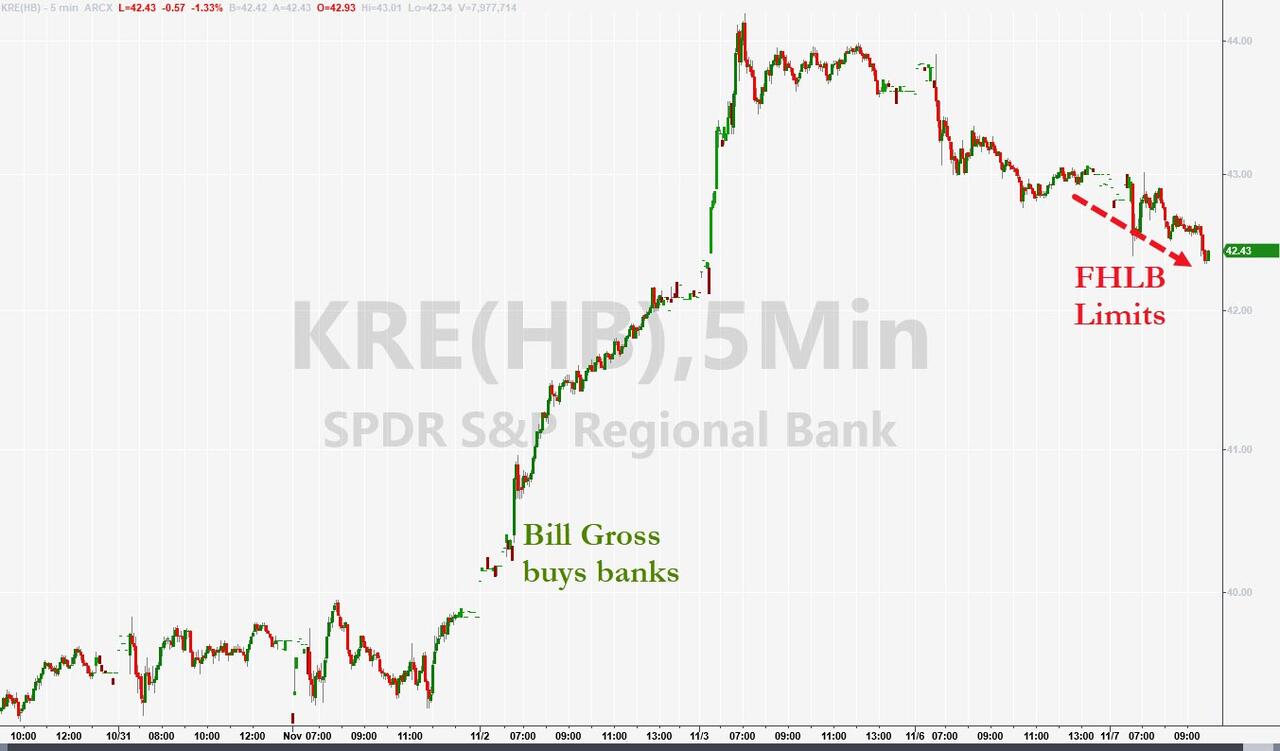
ZeroHedge writes, “Is Bill Gross about to face another big loser? On Nov 2nd, the former ‘bond king’ wrote on X that “regional bank falling knife has hit bottom” adding that he was buying shares of Truist Financial, Citizens Financial Group, KeyCorp, and First Horizon.

The Regional Bank Index soared for two days after that, but the last two days have seen the index give some of those gains back…

And today, we get headlines that – on their face – would seem like very bad news for smaller banks as regulators push to close the cookie jar of cheap rescue cash that access to Federal Home Loan Banks has provided.”


8:10 am

NDX futures consolidated near yesterday’s marginal new retracement high just above the trendline at 15150.00.  The first support under the NDX is the 100-day Moving Average at 15085.00, which may yield an aggressive sell signal.  The 50-day Moving Average is just beneath at 14953.09, yielding a possible confirmed sell signal.    The Cycles Model calls foe a decline that may last to the end of November,

Today’s options expiration shows Maximum Investor Pain at 15180.00.  There is virtually no long gamma.  Short gamma starts at 15170.00.  Sentiment is beginning to lean toward the short side.

ZeroHedge remarks, “This does not look like a top

This does not look like a bear market squeeze top. Chart shows average percentile of 16 equity market sentiment & positioning indicators.

Source: Goldman

This does too not look like a top

This too does not look like a bear market squeeze top. Risky vs. safe assets fund flows.”


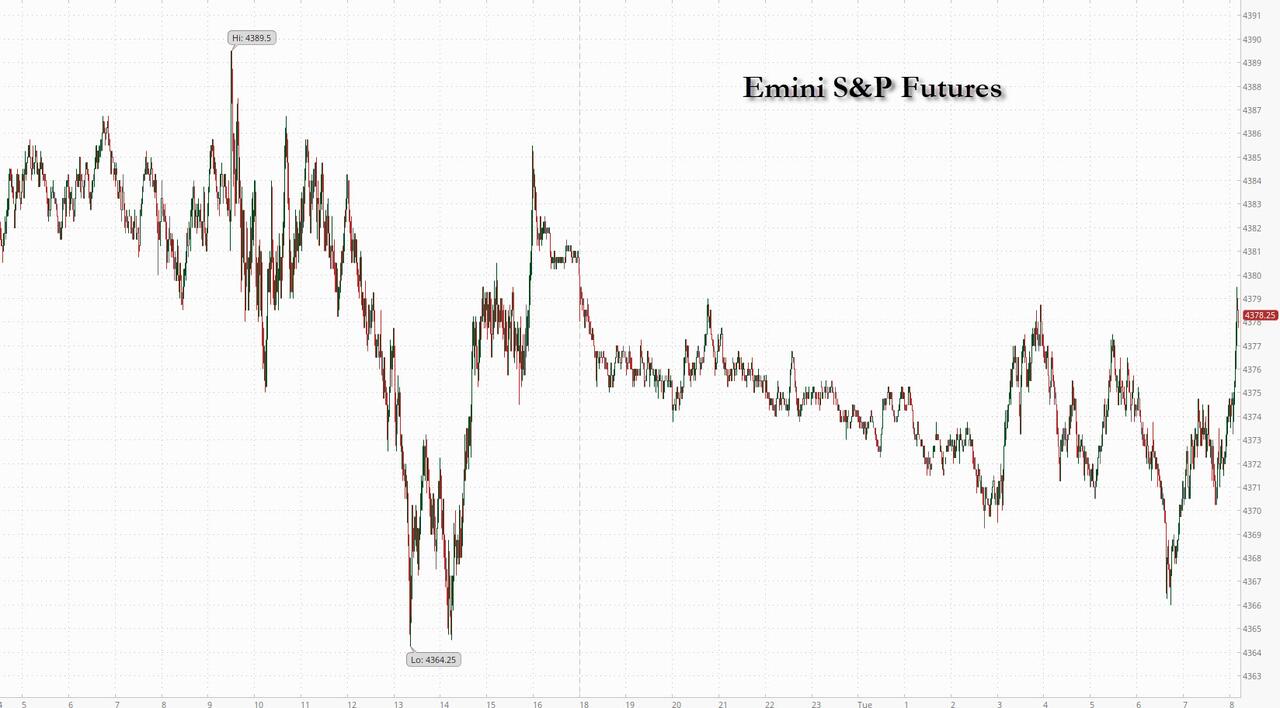
SPX futures are consolidating just above the 50-day Moving Average at 4348.54. A break down beneath it may produce a sell signal.  The Cycles Model infers a decline may follow lasting to the end of November.  This decline has the capability to go beneath the October 2023 low at 3491.58.

Today’s options expiration is heavily fought at 4350.00, which may also be Max Pain.  Long gamma starts at 4390.00, while short gamma begins at  4300.00-4320.00.

ZeroHedge reports, “US stocks were set to snap a six-day rally on Tuesday as traders reassessed expectations of Fed interest-rate policy after hawkish comments Monday by Minneapolis Fed President Neel Kashkari dampened hopes of speedy interest rate cuts from the US central bank. Kashkari is back today for round two; Indeed, traders appear to be awaiting more from Fed officials on the rate path outlook following Kashkari’s comments, with Fed Chair Jerome Powell also set to speak later in the week, but first we have to get through today’s calendar:

  • 07:30: Kashkari
  • 08:00: Goolsbee
  • 09:15: Barr
  • 09:50: Schmid
  • 10:00: Waller
  • 12:00: Williams
  • 13:25: Logan

As of 7:50am, S&P 500 futures are down 0.3% to 4372 with Nasdaq futures dropping by the same amount, while Europe’s Stoxx 600 index posted a similar loss.”


VIX futures are also consolidating near their lows.  A return to trending strength ma be imminent, with (positive) momentum increasing by the weekend.

Wednesday’s op-ex shows Max pain at 17.00-18.00.  There is no real short gamma.  Long gamma starts at 20.00 and may extend to 50.00.


TNX may be pulling back to retest the 50-day Moving Average at 45.60 before resuming its climb.  This may be an opportunity to lighten up long bond holdings.  The Cycles Model suggests that we may see a steady climb this week with supercharged performance beginning next week.

ZeroHedge remarks, “Just a furious bounce?

The move in Treasury futures has been extreme, but note we are hitting the negative trend line around these levels. Also worth noting is the 50 day moving average. We closed above it on Friday, but we are very close to it again. The 100 day remains “way” higher.

Source: Refinitiv

Too quick

“As usual, we’ve moved a long way very quickly. I think it may get harder to keep pushing yields a lot lower…” (Dom Wilson, GS).”


USD futures rose to 105.85 this morning, overcoming the 50-day Moving Average at 105.46, putting USD on a buy signal.  The Cycles Model shows increasing strength over the next two weeks, suggesting a possible breakout.


Crude oil futures made a new low this morning, approaching the mid-Cycle support at 78.23.  It is on a sell signal tat may last to early December.  The Head & Shoulders formation has been activated that should take crude to its Cycle Bottom at 65.24.

ZeroHedge reports, “The European oil and gas majors, which are also the world’s top LNG traders, reported a mixed bag of third-quarter results, with some beating or meeting estimates and others missing expectations amid diverging gas trading opportunities in Europe and Asia.

Shell and TotalEnergies, the world’s largest and second-largest LNG traders, respectively, reported strong gas trading earnings thanks to the open arbitrage to Asian markets in the third quarter. But BP, another major with a typically strong gas trading business, saw weak results in the division between July and September, which dragged overall earnings below analyst estimates. ”


Gold futures declined to 1962.90, on their way to test the mid-Cycle support at 1950.36.  The Cycles Model suggests gold may decline through the end of the year.  The Head & Shoulders formation poses an interesting target.  The Cycles May allow enough time for that to happen.

ZeroHedge gives a history lesson, “Public Law 93-373 was supposed to be so boring that Congress didn’t even bother to give it a name.

You know how most laws passed by Congress have some fancy name– like the “Inflation Reduction Act” or the “USA PATRIOT Act” or some such nonsense?

Well, on November 7, 1973, US Senator James Fulbright introduced a very short bill– it was only ONE page– that didn’t even have a name. But Fulbright’s unnamed bill ended up being one of the most important pieces of legislation in US history.”


Posted in Published | 1 Comment

November 6, 2023

11:13 am

BKX (refresh to update) may have begun its reversal after making a Master Cycle high on Friday.  The Cycles Model infers a month of decline lies ahead.

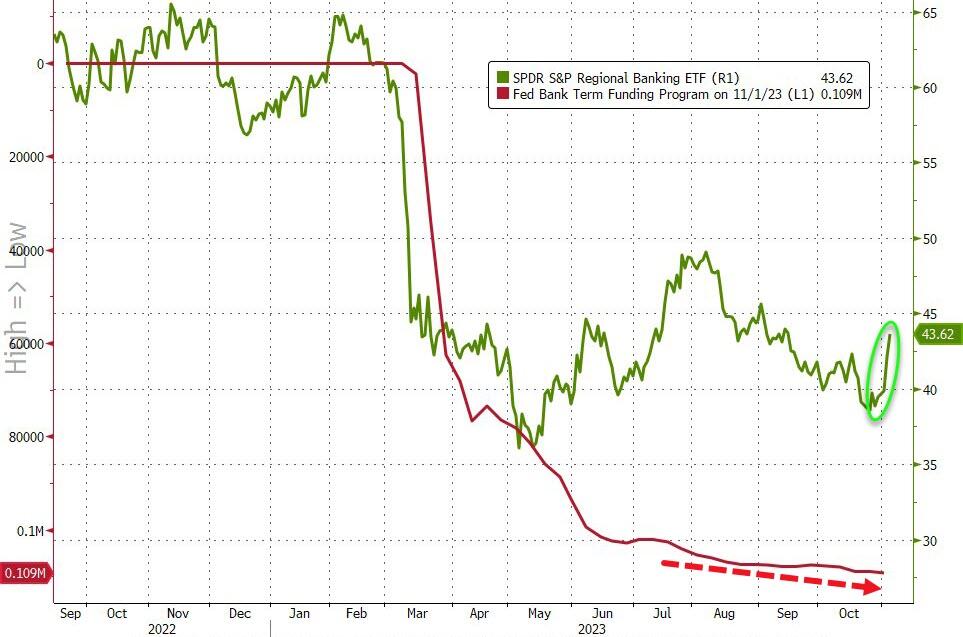
ZeroHedge remarks, “Bank stocks soared this week (along with everything else) despite another jump to a new record high for bank’s usage of The Fed’s emergency funding facility, and the massive deposit run the prior week.

Probably better not to show Bill Gross this chart…

Source: Bloomberg

So, what fun and games will The Fed do this week to ‘adjust’ the data so we don’t panic about a sudden bank run?”


7:45 am

Good Morning!

NDX futures are consolidating just beneath Friday’s intra-day highs and trendline at 15150.00.  The 100-day Moving Average is at 15083.54.  A decline beneath that level creates an aggressive sell signal.  A further decline beneath the 50-day Moving Average at 14953.00 confirms the sell signal.  NDX is at maximum resistance.

Today’s options expiration shows Maximum Investor Pain at 14900.00.  Long gamma begins at 14975.00.  Short gamma starts at 14850.00.

ZeroHedge observes, “Easy tiger

SPX’s perfect short term trend channel has stayed intact. The huge squeeze has taken the index back to channel highs. 4400, give or take, is a big resistance area. Note the 100 day coming in around 4425. The “easy” part of the “bounce” is over, now comes a much more tricky phase.

Source: Refinitiv

NASDAQ – show me the trend

NASDAQ is trading at the same levels we traded at in mid June. The index has actually been stuck in a range, with one bigger overshoot, and one bigger undershoot. We are right at the 100 day post the furious bounce.”


SPX futures are also consolidating just beneath the trendline at 4375.00.  You will notice that the last three Master Cycles ended at the upper trendline.  The current Master Cycle has nearly another month to go.  For the first time since March, it may end up at a new low.

Today’s op-ex shows Max Pain at 4350.00.  Long gamma may begin at 4370.00-4380.00 while short gamma may start at 4330.00.

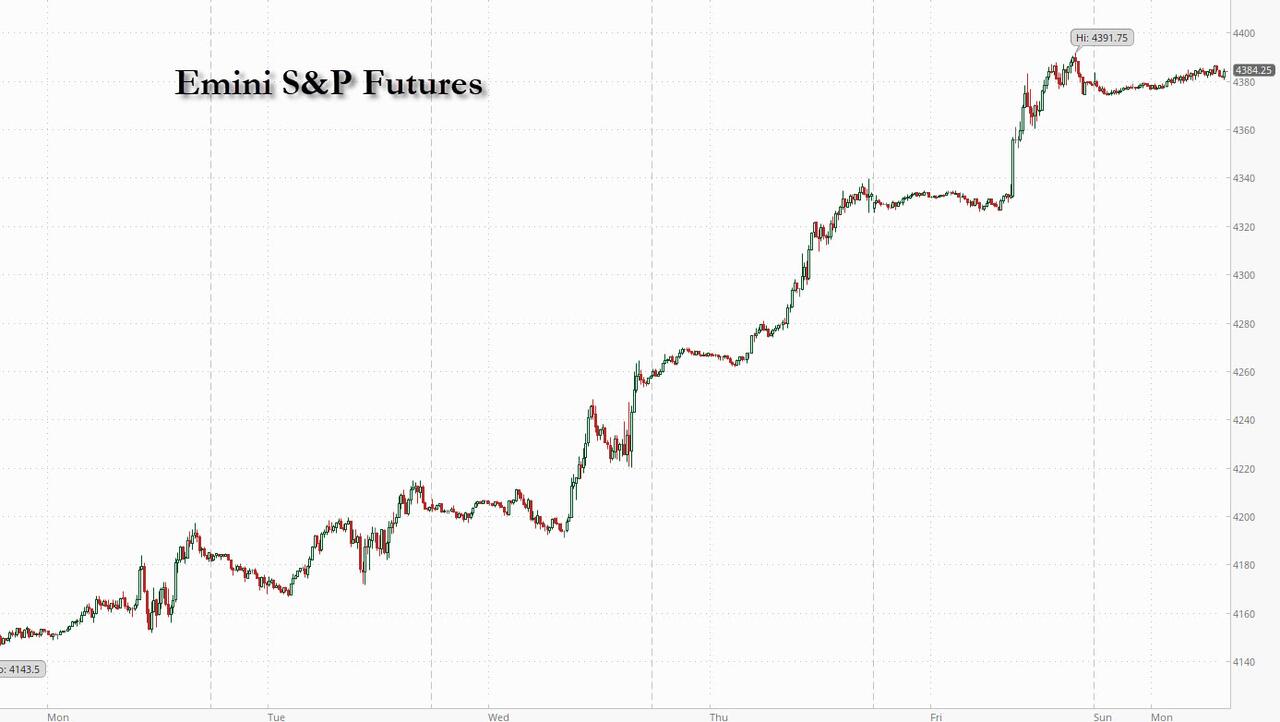
ZeroHedge reports, “US equity futures extended gains after last week’s blockbuster rally, the biggest of the year, despite some weakness in bonds, as traders remained optimistic that US and European central banks may start cutting interest rates as soon as next year. As of 7:40am, S&P emini futures were higher by 0.2%, near top of Friday’s range, while Europe’s Estoxx 600 dropped 0.2% with materials leading declines. South Korea’s Kospi soared more than 5% after regulators banned short selling. The dollar fell for a fourth day. Crude futures rose more than 1.5% after Saudi Arabia and Russia reaffirmed they will stick with their supply curbs through year-end. Bitcoin continued its ascent, last seen above $35K, with Ethereum rising above $1900. ”


VIX futures are consolidating near their low.  While the Cycles Model only suggested a half-Trading Cycle low on Friday, the depth of the decline was unusual.  The Cycles are making a comeback with trending strength returning at the end of the week.

Wednesday’s op-ex shows Max Pain at 15.50.  There is no short gamma beneath 15.00.  Long gamma may start at 17.00 and extends to 50.00.


TNX has bounced from Friday’s low and is climbing as I write.  It is back above the 50-day Moving Average at 45.52 and is on a buy signal.  The Cycles Model shows a steady rally out of the low with strength returning next week.  A possible high at the end of November may be 53.00.

ZeroHedge comments, “The ‘smart’ money may not be…

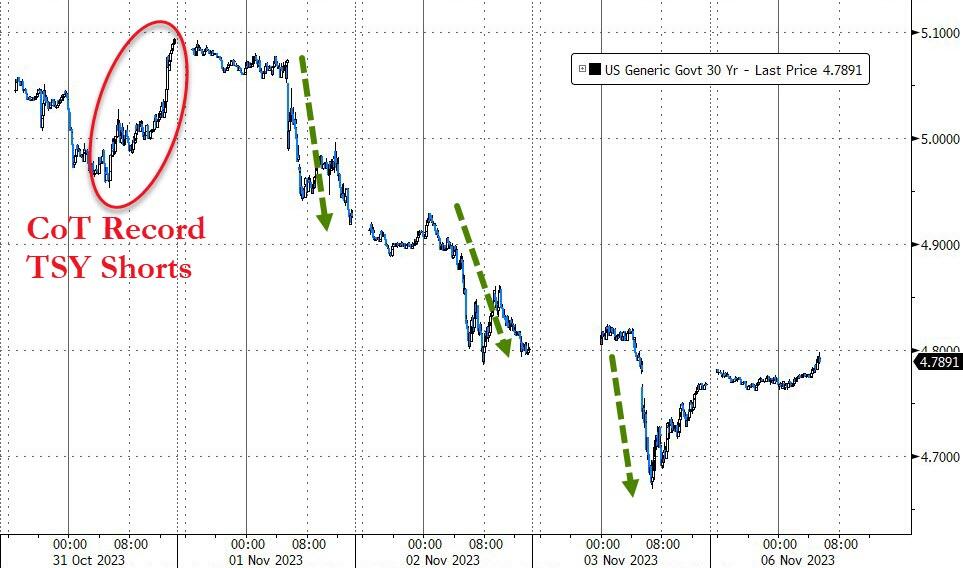
Just before US Treasury bonds saw their best week of 2023 (with the last 3 days seeing yields crash at the fastest pace since the COVID lockdowns of March 2020), hedge funds decided to add to their TSY Futures shorts (to a new record high).

Source: Bloomberg

A trifecta of terrific news for treasuries – smaller-than-expected Treasury refunding, more dovish than expected Powell, weaker than expected jobs data – triggered three massive waves of buying in bond-land right as hedge funds ramped up their net short Treasury futures positions to the most in data going back to 2006, according to an aggregate of the latest CFTC as of Oct. 31.”


USD futures consolidated inside Friday’s trading range.  The 50-day Moving Average lies at 105.43 and presents a possible buy signal once it is overcome.


Posted in Published | 9 Comments

November 3, 2023

2:25 pm

SPX is meeting fierce resistance at the September 21 gap beginning at 4375.70 and open to 4401.30.  It spent two weeks trying to overcome it in October, but failed.  Unfilled gaps are powerful resistance points, due to their history of failure, as you can see.  One of the reasons is that most shorts were bought after the gap down, so short covering no longer provides the fuel for SPX to go higher.  On the other hand, you will know a rally has legs when gaps are filled.  That may not happen for a while.


10:50 am

SPX rallied above the 50-day Moving Average at 4350.00, then reversed.  A decline beneath the 50-day (may have already happened) produces an aggressive sell signal.  Confirmation may come beneath the mid-Cycle support at 4292.23.  The rally may have turned into a bull trap.


7:30 am

Good Morning!

NDX futures rose to 14890.70 this morning, but have recently reversed into the red.  There are two possible outcomes.  The first is to reach the 50-day Moving Average at 14949.30, prolonging the rally, or decline through Intermediate support at 14778.52, creating a possible sell signal.  The Cycles Model infers that the decline may resume imminently and continue to the last week of November.

Today’s op-ex shows Maximum Investor Pain at 14750.00  Long gamma starts at 14800.00 while short gamma begins at 14700.00.   The dealers have squeezed out the shorts.  Will the longs pick up the baton?

ZeroHedge speculates, “More legs to the squeeze?

As we have been highlighting in our past few emails, there are reasons to be tactically short term bullish:

1. Massive buybacks

2. Retail participation

3. CTAs can have to buy a lot

4. HFs generally low positioning

5. Technical picture better with SPX above its 200-day moving average

6. Earnings now coming in better after a somewhat weaker start”


SPX futures have stopped short at 4317.60 and consolidated above 4300.00.  A break beneath Intermediate support at 4291.00 may produce a sell signal.  The original retracement target at 4259.92 may provide confirmation of the reversal and sell signal.  The Cycles Model suggests a clear reversal may occur by mid-day.

Today’s op-ex shows possible Max Pain at 4290.00.  Long gamma begins at 4300.00 while short gamma starts at 4285.00.  4300.00 appears to be the line in the sand for this tug-of-war.

ZeroHedge reports, “Equity futures are pointing to a slight pullback in US stocks, which are on track for their best week in a year, as Apple’s disappointing outlook anmd weaker than expected China sales weighed on markets. At 7:40am, S&P 500 futures were down 0.1% but off the worst levels of the session while Nasdaq 100 futures lost 0.3%. The pullback follows US stocks’ best day since April in the wake of the Federal Reserve’s decision to hold rates steady. The subdued session is also due to nerves around the US nonfarm payroll data later today as traders look for further confirmation that the Federal Reserve’s tightening cycle is nearing an end.”


VIX futures are consolidating near the low end of its range.  The consolation is that VIX may have stopped its decline, or very nearly so.    After being out-of-sync with the SPX for some time, it appears to be ready to re-engage.

Next Wednesday’s op-ex reveals Max Pain at 17.00-18.00.  There is no short gamma.  Long gamma begins at 20.00 and extends to 50.00.

ZeroHedge comments, “Sell low buy high

GS Prime book was sold for the third straight month in October. Main reason is heavy shorting. GS notes: “…the combined net selling from August to October across global equities was the second largest over any three month period in the past 10 years (only Q1 ’22 was larger) and ranks in the 99th percentile.”

Good luck explaining to your boss you shorted the recent lows in size and intend to keep that into year end…”


9:04 am

TNX is probing its target (the 50-day and trend line) at 45.45 tis morning, in a likely completion of its retracement.  Should that be the case, we may see a reversal this morning to higher yields.

ZeroHedge remarks, “TLT – the break out

TLT closed “well” above the negative trend line for the first time since the TLT bear started in July. Note it also managed closing above the 21 day by a margin not seen in a very long time. The 50 day is still higher, not to mention the 200 day.

Source: Refinitiv

Not seen in “modern” times

We have not seen the VXTLT vs VIX ratio at these levels in “modern times”.

Source: Refinitiv

TLT panic in a pic

The crowd is piling into TLT calls. Yesterday was the largest TLT call volume ever.”


USD futures have declined to a new retracement low at 105.08 thus far this morning.    I am studying whether today May be the Master Cycle low instead of 10 days ago.  The Cycles Model suggests the USD will be higher by year-end.


Posted in Published | 1 Comment

November 2 2023 All Souls Day

1:03 pm

SPX has made a very irregular retracement, as shorts get squeezed mercilessly.  By most standards, the retracement should have ended yesterday.  The retracement has taken back 70% of the decline since October 17 thus far.  It may be on its final legs, but now that it has gone this far, the 50-day Moving Average at 4352.55 offers a challenge.  What’s not to like, especially when BofA and Goldman Sachs are cheerleading?  As I said multiple times, this Wave can be treacherous.

ZeroHedge pronounces, “Equities (and bonds) are extending gains this morning with a massive short-squeeze. ‘Most Shorted’ stocks are up over 5% for now, the biggest daily squeeze since February…

Source: Bloomberg

And, as Goldman Sachs Partner, flow-trader John Flood warns, “this squeeze has momentum”.


8:10 am

Good Morning!

NDX futures have hit a morning high at 14811.50, on their way to the 61.8% Fibonacci retracement at 14945.00 or possibly the 50-day Moving Average at 14949.82.  Some traders and analysts have decided that the NDX isn’t bearish enough and is due for new highs.  The Cycles Model suggests the NDX may linger at the highs until mid-day, then resume its decline.

Today’s options expiration shows Maximum Investor Pain at 14725.00.  Short gamma begins strongly at 14710.00, while long gamma may take hold above 14800.00.  Long gamma does not have a lot of conviction, leaving the rally in a tenuous position.

ZeroHedge notes, ”  One week ago, BofA’s Michael Hartnett drew a lot of heat from the permabears when Wall Street’s most accurate strategist of the past decade predicted that a tactical rally was in the cards as one of his closely-followed buy signals had just been triggered. And while stocks did initially dip lower following his Oct 20 note as a result of aggressive mutual fund year-end tax loss selling, the S&P is now back to green from his reco following today’s “dovish at the margins” Fed statement (in Goldman’s words), which may have just given the green light for a year end rally.”


SPX futures have rallied to a morning high at 4269.80, thus far.  It has surpassed the mid-Cycle resistance at 4258.64 and may reach Intermediate resistance at 4295.00 or round number resistance at 4300.00.  Today may be a trading Cycle (60-day) high, a lesser inflection point that may be finished by mid-day.  If so, there may be a month of decline to follow.  As mentioned earlier, Wave Bs can be treacherous.

Today’s op-ex shows Max Pain at 4235.00.  Long gamma begins at 4270.00 while short gamma starts at 4200.00.

ZeroHedge reports, “US equity futures, and global stocks and bonds extended gains Thursday as traders bet the Federal Reserve is ending its historic tightening campaign, and that easing may not be too far behind. As of 8:00am, S&P 500 futures rose 0.5%, while Nasdaq 100 futures gained 0.7%. Both underlying indexes had jumped on Wednesday after the Fed held interest rates steady and the Treasury announced plans to slow the pace of increases in quarterly long-term securities sales. The dollar weakened and Treasuries steadied after sharp gains following Powell’s comments yesterday. In Asia, the yen extended its gains from Wednesday, while the South Korean won led emerging-market currencies higher. The 10-year TSY yield dipped two basis points after falling below 4.75% for the first time in two weeks. Elsewhere, the latest major company earnings also provided a dose of good news.Commodities are mixed with WTI adding 1.5% in the morning while base metals are for sale. Today, macro calendar is quieter: we have some second-tier labor data (Challenger Job Cuts, Nonfarm Productivity, ULC) and Factory Orders. We will receive AAPL’s earnings after the bell. All eyes on Friday’s NFP and ISM-Srvcs releases.”


VIX futures have declined to 16.12 this morning.  A further decline is possible to 15.44 to form an expanded flat formation.  The Cycles Model offers little short-term guidance.  However, the indications are that trending strength may come roaring back next week.

Next Wednesday’s op-ex shows Mas Pain at 18.00.  Short gamma has little advantage over long gamma beneath 18.00.  Long gamma starts at 20.00 an had high conviction to 40.00.


TNX plummeted beneath Intermediate support at 47.01 and may be destined to test the 50-day Moving Average at 45.39 by early  next week.  TNX may be due for a Trading Cycle low at that time.  The Cycles Model then suggests the resumption of the rally until the end of November.  A possible target at the end of November may be greater that 52.00.  By year-end, the 10-year yield may be in the range of 54.00-55.00.

ZeroHedge remarks, “In a clear sign we are reverting to a system where fiscal policy dominates monetary policy, the Treasury’s refunding announcement is probably more consequential than the Federal Reserve’s meeting today. An increased skew away from bill issuance is a headwind for liquidity and risk assets.

The refunding announcement is in focus due to the US’s huge fiscal deficit. It comes when rising yields – i.e. loose fiscal policy meets tight monetary policy – means the government’s interest-rate costs are soaring.

The rapid rise in US yields to ~5% points to the government’s annual interest-rate bill rising to 4.5-5% of debt outstanding in the next six months. That’s in the region of $1.7 trillion – or the GDP of Australia – each year.”


Posted in Published | 1 Comment

November 1, 2023 All Saints Day

10:30 am

The retracement of the BKX only amounts to 17%.  Yet, the correction may be complete, or nearly so.  This bounce is not to be trusted.

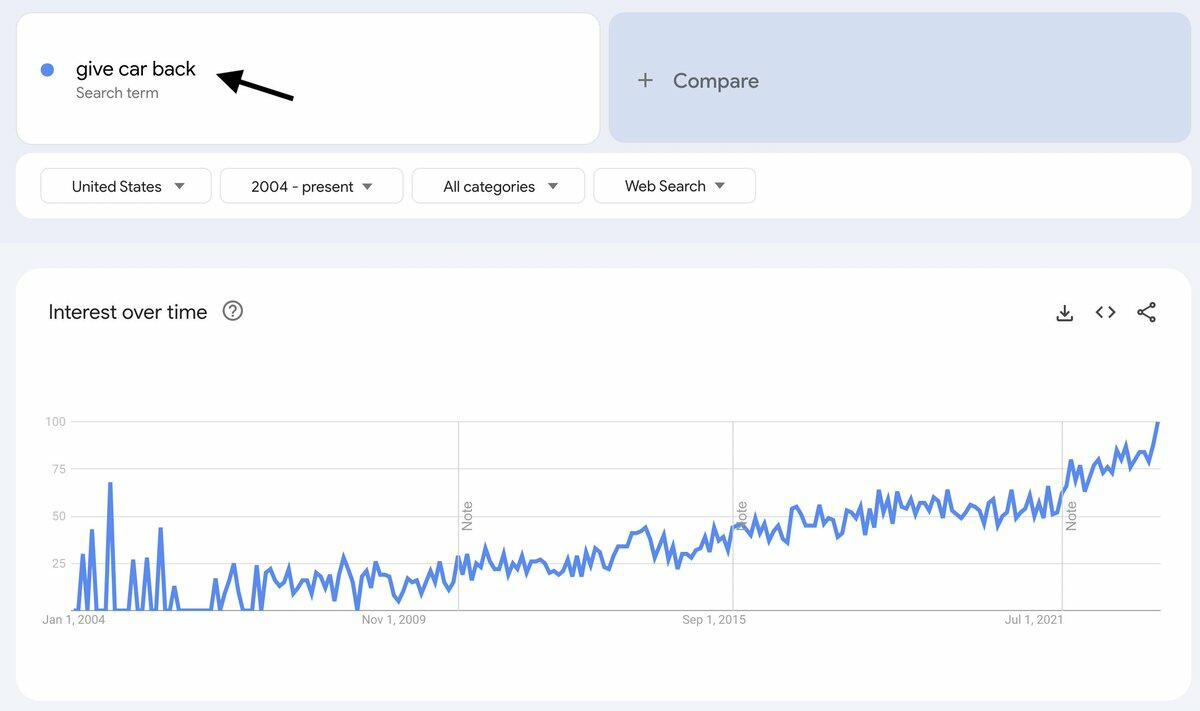
ZeroHedge notes, “Recent data from Edmunds reveals that an unprecedented 17% of American car purchasers now have monthly car payments of $1,000, a significant increase from just 7% three years ago. This trend highlights the extent to which consumers, despite being financially stretched, are willing to take on massive auto debt in these uncertain economic times as macroeconomic headwinds pile up.

New Google data, first revealed by X user CarDealershipGuy, shows Americans are searching “give car back” on the internet has soared to a record high.

CarDealershipGuy added, “For everyone DMing me: No, you can’t “give back” a car – That’s a repossession.”


9:52 am

TNX has slumped beneath the Cycle Top at 48.28, suggesting an extension of the pullback.   Should that be the case, the rally in yields may resume shortly.  It may also create a new buy signal at the re-crossing of the Cycle Top.

ZeroHedge observes, “We already knew – after its publication on Monday – that in the current quarter, the Treasury expected to issue $776BN in debt in the current quarter, or some $76BN below the previous forecast published last quarter, a welcome slowdown in debt issuance as a result of slightly higher than expected tax receipts in October.

Today’s Treasury Refunding Announcement gave the details of what the composition of this issuance would be, with a focus on Coupon vs Bill sales.”

9:41 am

SPX has breached the 4200.00 (Max Pain) level and is likely to continue to the 38.2% Fibonacci retracement value at 4215.00.  Dealers may have induced the short covering at the open.  The 50% retracement value at 4250.00 may also be in sight.

ZeroHedge reports, “US equity futures are weaker to start the new month ahead of today’s Fed meeting (which as we previewed earlier will be a nothingburger now that the Treasury itself is raising yields with its relentless debt issuance and doing the Fed’s job for it) as well as macro data dump which includes the Treasury’s Q4 refunding statement. As of 8:00am, S&P and Nasdaq 100 futures dropped by about 0.4%. The USD is stronger with bonds catching a bid. Commodities are mixed with crude/base metals up, while natgas, gold down, and both softs/grains mixed. Today’s data focus includes the Fed, ADP, JOLTS, ISM, vehicle sales; Treasury refunding announcement at 8.30a ET. We also get a deluge of consumer-sector earnings today. ”


7:30 am

Good Morning!

SPX futures have declined to 4173.60 thus far this morning after making a mere 32% retracement.  I am a bit hesitant to call the bounce over, but all the ingredients may be present for a completed retracement.  If not complete, the turn may occur near mid-day.

Today’s options expiration shows Maximum investor pain at 4200.00.  Long gamma starts at 4220.00, while short gamma begins at 4180.00.  This morning we are exploring the potency of short gamma.


VIX futures have risen to 18.38 thus far this morning.  The trend line and confirmed buy signal occurs near 18.60.

Today’s op-ex shows Max Pain at 18.00-19.00.  There is no short gamma.  Long gamma extends from 22.00 to 45.00.

ZeroHedge reminds, “VIX has come down

VIX printed an intra day high of just above 22 on Friday. We are now trading around 18. We have actually seen one of the bigger 2 day down candles in the VIX in a long time…but volatilities still remain elevated given the fact we are not realizing much volatility.”


Posted in Published | Comments Off on November 1, 2023 All Saints Day

October 31, 2023

8:00 am

Good Morning!

NDX futures have risen to an overnight high of 14368.00.  Overhead resistance may lie at the 38.2% Fibonacci level at 14542.40 or possibly higher, at 14643.70, where an unfilled gap may stop the retracement.  The NDX Hi-Lo Index closed yesterday at -396.00, indicating that nearly all of the strength of the rally lies in the mega-caps.  Showing a smaller loss at month-end is critical.  Afterwards, anything goes.

Today’s options expiration shows Maximum Investor Pain at 14500.00 and the most contested space for both puts and calls.  There is virtually no long gamma above 14500.00, while short gamma is held at 50-point intervals down to 14100.00.

ZeroHedge notes, “A deteriorating outlook for corporate earnings offers little support for the S&P 500 reeling from its worst October since 2018.

While data from Bloomberg Intelligence show US firms are on pace to report a surprise increase in third-quarter earnings, forecasts for future quarters have been marked down as companies warned of tepid demand and an uncertain macroeconomic outlook. Deutsche Bank Group AG said analysts’ estimates for the fourth quarter have been cut by a “more than typical” 1.9% since the start of the reporting season.”


SPX futures made an overnight high at 4180.10, only ticks higher than yesterday’s intra-day high at 4177.47.  The uptick is weakening, suggesting a possible pullback to 4120.00-4130.00 before another attempt at a higher retracement.  A lower retracement target is possible.  The 38.2% retracement lies at 4215.00.

Today’s op-ex shows Max Pain at 4205.00.  Long gamma starts at 4220.00, while short gamma begins at 4200.00.  Dealers must close today’s market at or above 4200.00 to achieve minimum payout.

ZeroHedge reports, “Futures were higher and European bourses were solidly in the green on the last day of the month, extending yesterday’s blistering rally which sent the S&P 1.2% higher and which took place after most of the mutual-fund year-end tax loss selling had exhausted itself during last week’s rout. As of 7:45am, S&P futures were higher by 0.2%, Nasdaq 100 futs gained 0.1%, while Europe’s Estoxx 50 outperforms, higher by around 1% on the day with materials sector outperforming. Treasury yields are lower after the US Treasury reduced its estimate for federal borrowing for the current quarter, citing stronger-than-expected revenue; the dollar was weaker against most major currencies, except the yen. Oil prices are edging higher after dropping in the prior session. Israel stepped up ground operations in Gaza and struck more targets in Lebanon and Syria overnight.”


VIX futures declined to a morning low at 19.20.  Support appears at the trendline at 18.80.

Today’s op-ex shows Max Pain at 20.00.  Short gamma starts at 19.00, but is hemmed in there.  Long gamma begins at 21.00 and extends to 45.00.


TNX may have bounced from the Cycle Top at 48.13 as it completes a minor Trading Cycle.  If so, the rally may resume quickly.  The Cycles Model suggests another month of rising rates.

ZeroHedge comments, “One quarter ago, when reporting on the Treasury’s latest marketable debt issuance forecast, we pointed out something striking which sparked a historic selloff in Treasuries over the next 90 days: the US Debt Tsunami had Begun as the “US Was Set To Sell $1 Trillion In Debt in Q2, 2nd Highest In History, As Budget Deficit Explodes“, while the forecast debt sale for Q3 was also an eye-watering $852 billion. The numbers were big enough that even the bond market – which had long since habituated to seeing huge debt issuance forecasts every quarter without batting an eyelid – cracked.

Since then it’s went from bad to worse when as we first noted, the US quickly added some $600 billion in total debt in just one month after breaching the key $33 trillion level.”


USD futures are rising toward the Cycle Top at 106.77.  It may still be in a period of trending strength, which may be enhanced by the FOMC meeting.


Posted in Published | 2 Comments

October 30, 2023

3:05 pm

Crude Oil had dropped beneath the Head & Shoulders neckline at 82.50 to a low of 81.84.  It is on a sell signal.


10:00 am

BKX, our liquidity proxy is due to bounce after making a Master Cycle low on October 25.  The retracement may only take a few days.  The potential target may be   Intermediate resistance at 76.96 or the 50-day Moving Average at 78.37.  From that point we may see a waterfall decline much like the  March decline, but larger.  The Cycles Model suggests the decline may continue into the first week of December.  Since this is a liquidity event, it may affect all markets.

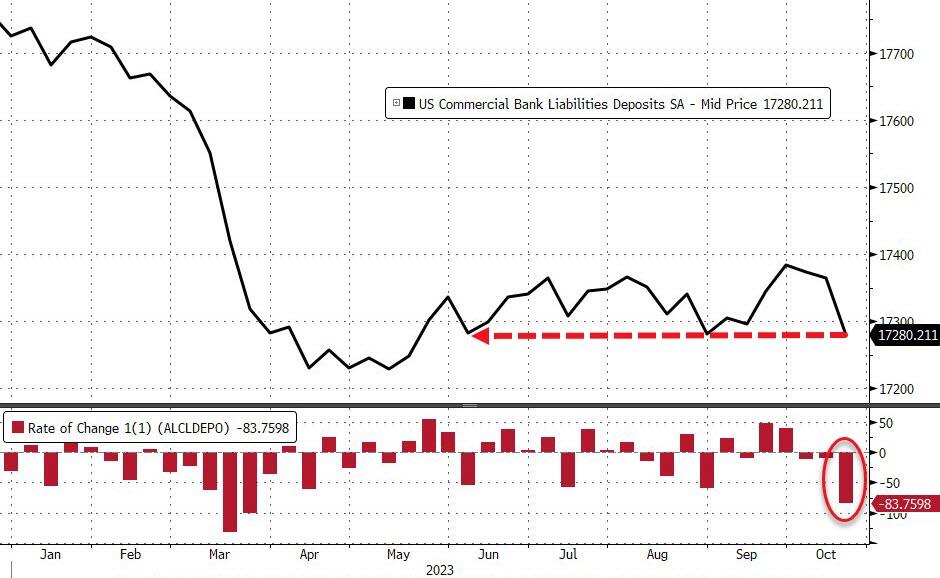
ZeroHedge reveals, “With usage of The Fed’s emergency funding facility rising once again to a new record high last week – and banks stocks clubbed like a baby seal – all eyes are once again on just what The Fed can do to ‘seasonally-adjust’ the data to avoid the admission of any deposit run fears in domestic banks.

Total bank deposits – on a seasonally-adjusted basis – crashed by a massive $83.7BN last week (the biggest outflows since SVB) to the lowest since June…”


8:15 am

Good Morning!

NDX futures are testing the lower trendline/channel boundary at 14320.00.  More likely than not, there may be a breakthrough to 14750.00-14780.00, testing the prior high.  The Cycles Model suggests that this retest may be short, but sharp, squeezing out weak hands.  The institutions have an incentive to shore up the month-end visuals.

Today’s options expiration sows Maximum Investor Pain at 14230.00.  Long gamma begins at 14250.00, while short gamma starts at 14220.00.

ZeroHedge remarks, “Boo

“The strategy for the discoverers and entrepreneurs is to rely less on top-down planning and focus on maximum tinkering and recognizing opportunities when they present themselves,” wrote Nassim Taleb. “So, I disagree with the followers of Marx and those of Adam Smith: the reason free markets work is because they allow people to be lucky, thanks to aggressive trial and error, not by giving rewards or ‘incentives’ for skill. The strategy is, then, to tinker as much as possible and try to collect as many Black Swan opportunities as you can.””


SPX futures are testing the descending trendline at 4150.00.  The window for this rally may be short, but should it break through, the next level of resistance is at 4260.00.  The over-arching signal remains on a sell, since Waves B can be treacherous.  That being said, the bounce may go as high as the mid-Cycle resistance at 4257.83 in the next few days.

Today’s op-ex shows Max Pain at 4150.00, so there may be the dealers’ incentive to close at that level.  Long gamma starts at 4160.00 while short gamma begins with a wall of puts at 4140.00.

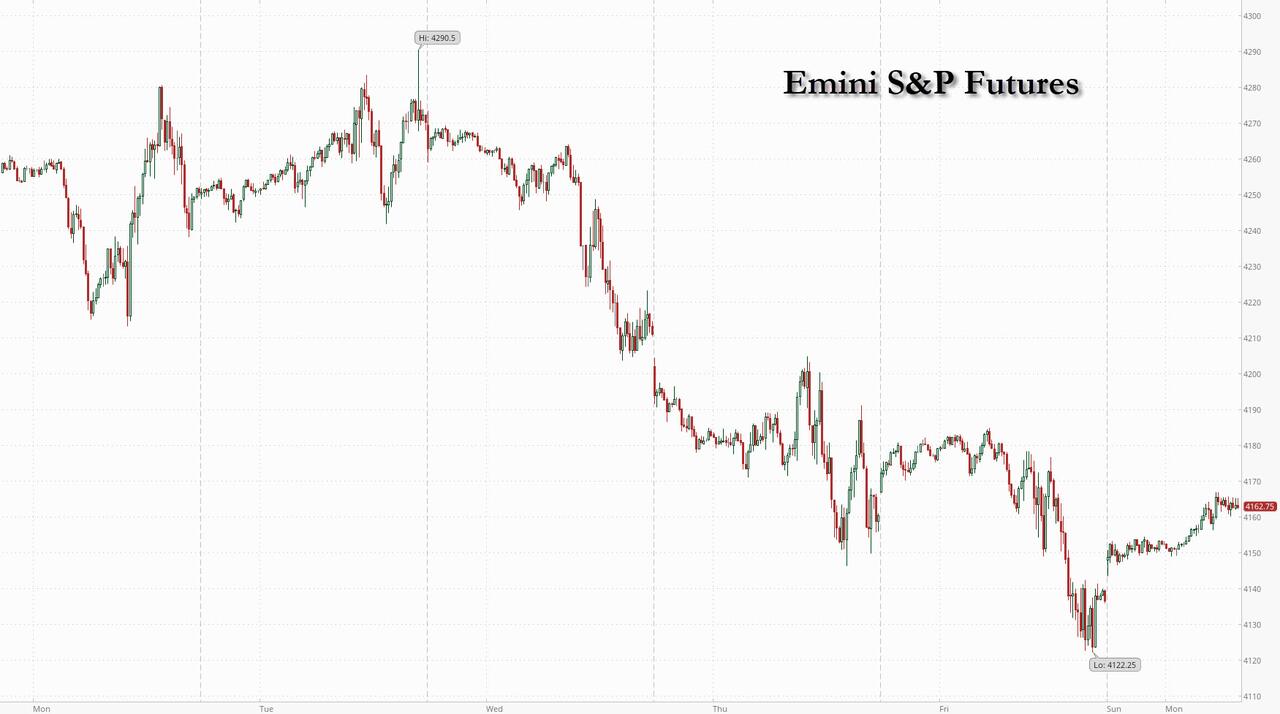
ZeroHedge reports, ” Ending a week that saw the S&P be the most overshorted in history, with Goldman PB reporting that its HF clients had shorted stocks for a record 12 consecutive weeks, it was inevitable that we would get an oversold bounce at some point and this morning we are seeing just that, with stocks in Europe broadly higher, and US equity futures also rising and reversing all of Friday’s loss. As of 7:45am, S&P futures were higher by 0.7%, Nasdaq futures gained 0.8% and the Estoxx rose  0.8% in early London session with gains led by utilities and energy; WTI futures were lower by 1.1% on the day because the complacent market downplayed the Israeli ground offensive into Gaza as “less aggressive than feared.” Ahead of a very busy week, JPM summarizes sentiment as follows: “are futures potentially setting up a relief rally into month-end or does the selling pressure continue with SPX under its 200dma.” Gold slipped below $2,000 an ounce, the dollar dropped as bitcoin gained and ten-year Treasury yields resumed their grind higher to 4.86% ahead of today’s Treasury issuance projections statement.”


VIX futures are consolidating inside Friday’s trading range.  Support lies at the trendline at 18.60.  Alternate support lies at the mid-Cycle line at 17.24.  Something is afoot here, since today is a high trending strength day.  Should that strength reveal, the Cycle Top at 23.15 may be tested again.

Wednesday’s op-ex shows Max Pain at 20.00.  Short gamma may begin at 19.00, with a healthy collection of longs at 18.00.  Long gamma begins at 21.00 and is heavily populated to 450.00.

11:00 am

ZeroHedge observes, “VIX remains above 20 this morning, but has followed the pattern of the last 3 weeks with VIX/vol bid into Friday due to weekend risk… and when WW3 does not actually occur, VIX/vol is sold in relief.”


ZeroHedge informs, “Corrections

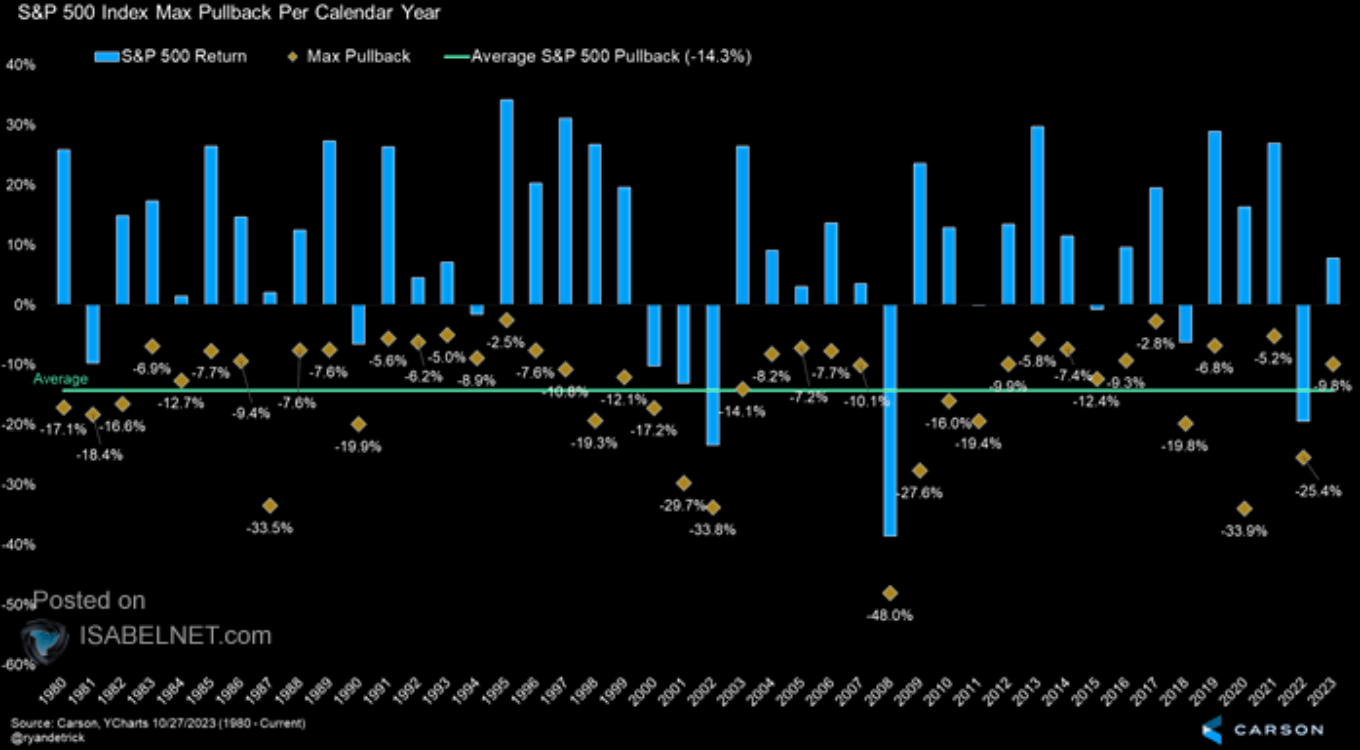
Corrections are common. On average, the market declined 10% or more every 1.2 years since 1980. It is of course not clockwork, but the following charts and tables are good to put things into perspective when we are in the middle of a correction (perhaps aspiring to become a crash…)

Corrections, we had a few…

1. Since 1980, the peak-to-trough pullback within a given year has averaged 14.3% in SPX

2. It is feature not a bug….over the last four decades, the NDX has averaged a peak-to-trough drawdown of 20% in each year


TNX rose to 49.11 this morning on a possible high strength day.  Should the correction be over, it may rest the upper trendline near 50.50.  Regardless of today’s outlook, yields are destined to rally higher through the end of November.  This rally may use the Cycle Top as support during that time.  Advisors and investors are showing too much enthusiasm for trying to find the top tick in treasuries.

ZeroHedge remarks, “The ongoing schism over the fate of the most important and liquid market in the world, US Treasuries, has reached never-before seen levelk.

Consider the following: with 10Y yields rising above 5.00% last week for the first time since 2007, ETF traders have been aggressively trying to bottom tick the selling in rates. They are doing so in two ways.

On one hand, as Goldman’s Derivatives traders Brian Garrett and Cullen Morgan write, demand for TLT calls and call spreads exploded this week. That’s because “this is a cheap way to play for a snapback in bonds.” As shown below, average TLT call volume this was over 350k contracts per day, an all-time highs…”


USD futures have pulled back to test Intermediate support at 105.83.  The test may not be completed, as today is a day of trending strength.  The trend is higher, so we may see the Cycle Top at 106.74 tested instead.  The Cycles Model suggests the uptrend may last another three weeks.


Crude Oil futures made a morning low of 83.75 as it retreats from its high at the 50-day Moving Average at 85.85.  Support lies at the Head & Shoulders neckline near 82.50.  Should it break through, we may see a waterfall decline down to the Cycle bottom at 65.11.


Posted in Published | 2 Comments

October 25, 2023

8:00 am

Good Morning!

Please Note:  This will be my last entry for the week, as family concerns take precedence.  I will return on Monday with more updates.

NDX futures are consolidating this morning after a completed 38.8% retracement.  While there may be room to go higher, a decline beneath 14600.00 may confirm the reversal.   A further decline beneath 14200.00 establishes a new downtrend.

Today’s options expiration shows Maximum Investor Pain at 14875.00.  Long gamma may begin at 14900.00.  Short gamma starts at 14850.00.

ZeroHedge notes, “Microsoft shares are soaring after hours following a top- and bottom-line beat

  • Revenue was $56.5 billion (better than the expected $54.54 billion) and increased 13% (up 12% in constant currency).
  • Diluted earnings per share was $2.99 (better than the $2.65 expected) and increased 27% (up 26% in constant currency).”

ZeroHedge comments, “The big question into Alphabet’s earnings was what, if any, progress they had made on monetizing the AI promise without cannibalizing the company’s main moneymaker – search advertising; and just how much capex they blew on NVDA chips to feed the LLM-processing beast.”


SPX futures may be consolidating after making a 34.3% retracement.  Despite the energy consumed to make this correction,  mid-Cycle resistance at 4259.00 appears to be holding.  A decline beneath 4219.00 suggests the correction may be over and the decline resumed.

Today’s op-ex shows Max Pain at 4265.00.  Long gamma begins at 4275.00.  Short gamma may begin at 4260.00 but strengthens beneath 4225.00.

ZeroHedge reports, “US equity futures are sliding – but off the lows of the session- setting up Wall Street for a lower open, with underperformance driven by Alphabet, whose shares have tumbled premarket after its cloud unit revenue disappointed. As of 8:00am ET, S&P futures were down -0.3% while Nasdaq futs drifted -0.5%, after Microsoft and Google delivered a mixed picture of big tech earnings, setting the stage for peers still reporting this week. The dollar is stronger for a second session tracking Treasury yields which also rose, while oil was little changed and there was a bounce for iron ore following the Chinese stimulus measures. In Europe, stocks reversed earlier losses as a 55% drop for French payments firm Worldline offsetting a gain for Deutsche Bank. Asian markets were also broadly higher on hopes that a new 1 trillion yuan in debt issuance will provide a fiscal stimulus for China’s struggling economy. Today’s macro data focus is on new home sales and mtge applications”


VIX futures dipped to a morning low of 18.86, remaining above the trendline at 18.60.  The Cycles Model allows the VIX to decline to its mid-Cycle support at 17.20 from which the next probe higher may be launched.  Otherwise, a breakout above 23.07 confirms the rally higher.

Today’s op-ex shows Max Pain at 18.00.  Short gamma is in short supply while long gamma begins at 20.00 and extends to 50.00.

ZeroHedge remarks, “Stress remains elevated

VIX and MOVE have “parked” at rather elevated levels.

Source: Refinitiv

Mexican butterflies

Risk is global, and watching some of the more risk sensitive FX pairs, such as the MXN, is a must. The short term gap vs SPX remains very wide…


TNX futures have risen to 48.93 this morning and appear to have resumed their rally after a brief respite.  The Cycles Model indicates a return of trending strength by the weekend.  If correct, the rally is rates may continue to the end of November.

ZeroHedge observes, “US households are becoming the buyer of last resort in Treasuries, meaning yields may need to rise by as much as 1.5 percentage points to meet the sector’s elevated and rising inflation expectations.

The world is once again having to acclimatize to higher rates. US 10-year yields this week rose above 5% for the first time since 2007. But they may need to climb even further to clear the market as other sectors continue reduce their Treasury exposure, leaving households as the only net buyer.”


Posted in Published | 1 Comment

October 24, 2023

12:30 pm

SPX has risen to the mid-Cycle resistance currently at 4257.38, then reversed down beneath the 200-day Moving Average at 4236.85.  It may be back on a sell signal, but with confirmation beneath 4200.00.  Too many pundits are not convinced of a bear market potential.  See below.

RealInvestmentAdvice opines, “The “pain trade” continues to be higher into year-end. We made Such a point in January, suggesting the 2022 “correction” was complete. Let’s review what I wrote, and then we will expand on why we believe the “pain trade” is higher over the next few weeks.”


8:00 am

Good Morning!

NDX futures rose to 14723.20 this morning in an extension of its bounce as it may aim for Intermediate resistance at 14982.62, a 61.8% Fibonacci retracement.  An alternate (lesser) possibility may be at short-term resistance at 14886.00, a 50% retracement.   The Cycles Model suggests another day (or more) of rally before the decline resumes.

Today’s options expiration shows Maximum Investor Pain at 14625.00.  Long gamma starts at 14650.00 while short gamma begins at 14600.00.

ZeroHedge observes, “It’s about get really busy.

This week we get 162 companies, or 39% of S&P market cap, reporting…

… with the highlights being the biggest giga-cap tech names such as Microsoft and Alphabet tomorrow, Meta on Wednesday and Amazon on Thursday, which together make up over $6tn in market cap, and nearly 17% of the S&P 500.”


SPX futures rose to a morning high of 4243.80.  It may continue to rise to the mid-Cycle resistance at 4256.23, a 32.8% retracement.  A positive earnings surprise may boost the bounce to 4282.00-4300.00, as much as a 50% retracement.  The decline may then resume until November 17 options expiration.

Today’s options expiration shows Max Pain at 4245.00.  Long gamma starts at 4250.00 while short gamma begins at 4225.00.

ZeroHedge reports, “Global stocks rose, US index futures jumped and bitcoin erupted higher ahead of closely-watched earnings from tech gigacaps Microsoft and Alphabet later today (full preview here). As of 8:00am ET, S&P futures were up 0.6%, at session highs and set to snap a five-day losing streak with Nasdaq futures also higher by 0.6%. Treasuries stabilized, with the US 10-year yield dropping as low as 4.80% before reversing gains, amid growing speculation that the recent selloff was excessive. Treasury 10-year yields slipped as much as five basis points to a one-week low before paring the move. Europe’s Stoxx 600 index edged higher.”


VIX futures fell to 19.66, hovering at the trendline.  An especially positive report from one or more of the giga-cap companies may drive the VIX down to the 50-day Moving Average at 16.49.  However, the Cycles Model suggests that trending strength may come back near the end of the week.

Wednesday’s op-ex shows Max Pain at 19.00.  Short gamma has an anemic sowing at 17.00-18.00.  Long gamma begins at 20.00 and extends to 50.00.

ZeroHedge remarks, “What is the risk of a short squeeze now?

“Still present, but potentially delayed…A squeeze might not accelerate unless we get 1) evidence consumer spending isn’t slowing too much, 2) relatively good earnings season, 3) Fed communicating they’re on hold. Given the conditions that might have to be met, a sustained move higher in shorts seems like a greater possibility in Nov than right now” (JPM Position Intelligence)

Lowest beat level

As for earnings, we’re only ~17% of the way through results for the SPX and the beat rate is coming in at its lowest level so far in ’23. The 73% reading is still 2ppts above the LT average, and decently above the 2 Qs it broke below 70% last year. That said, stocks are getting punished. The poor tape is definitely a big contributing factor, but misses (of which there have been plenty) are being punished the hardest vs. every other quarter since 2010, averaging -3.7% 1D moves.”


TNX made a new retracement low this morning at 47.98.  Should TNX not decline beneath the Cycle Top at 47.31, the rally may resume with increased trending strength by the weekend.  This may clear some “noise” in the Cycles Model.

ZeroHedge remarks, “US yields likely need to climb further as retail investors become increasingly attuned to hedging inflation. Bond rallies are likely to be transient as the primary trend for Treasuries remains down.

After decades of real and nominal levels being almost indistinguishable, it’s not a great surprise that both professional and retail investors will take time to adapt to the new normal. Countries used to unruly inflation, like Argentina, are well accustomed to their currency’s actual value (not the official value), and how rampant price growth can decimate the real value of financial assets.”


Crude oil futures declined to 84.92 thus far this morning.  Crude is on a sell signal beneath the 50-day Moving Average at 85.66.  The Cycles Model suggests that the decline may gain trending strength over the next few weeks with a potential low in about 4 weeks.


Posted in Published | 1 Comment