April 15, 2024

10:15 am

BKX broke beneath its 50-day Moving Average at 98.19 on Friday, but recovered above temporarily.  Today it may make a permanent break beneath the 50-day, confirming its sell signal.

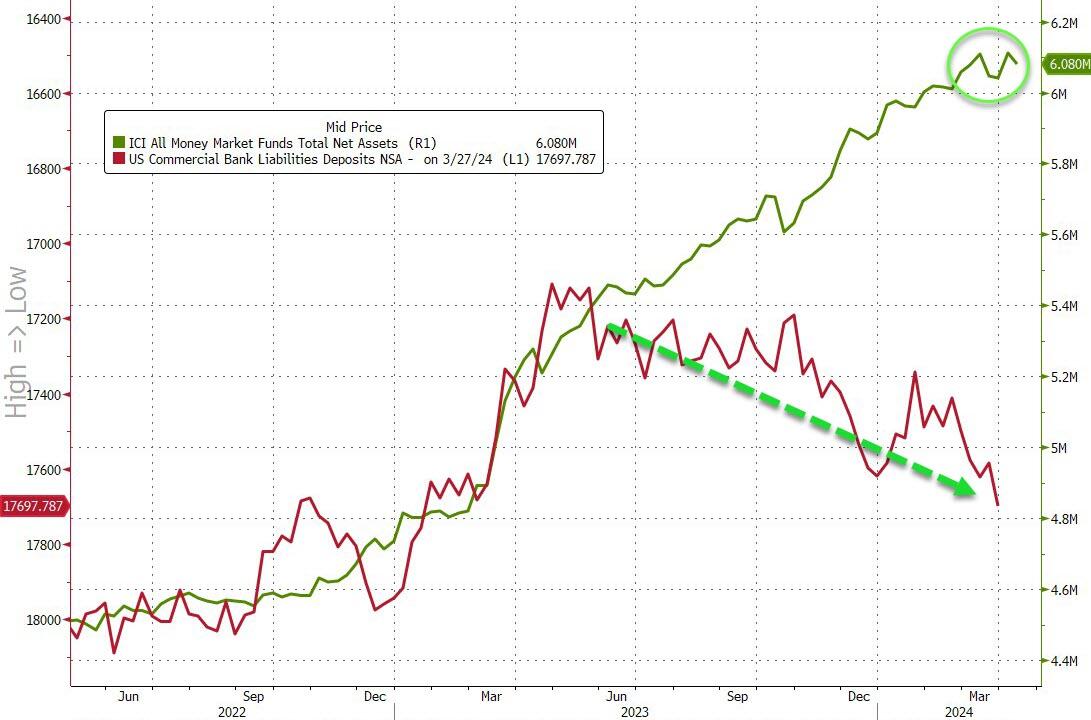
ZeroHedge reports, “Money-market funds saw a small outflow last week (surprisingly small given how close to Tax-Day we are), leaving them still near record highs over $6 Trillion (and the trend of increased deposits at banks has been accelerating)…
Source: Bloomberg

Interestingly, amid all the talk of tapering QT, The Fed balance sheet was basically unchanged last week (-$1.4BN)…”


8:40 am

Good Morning!

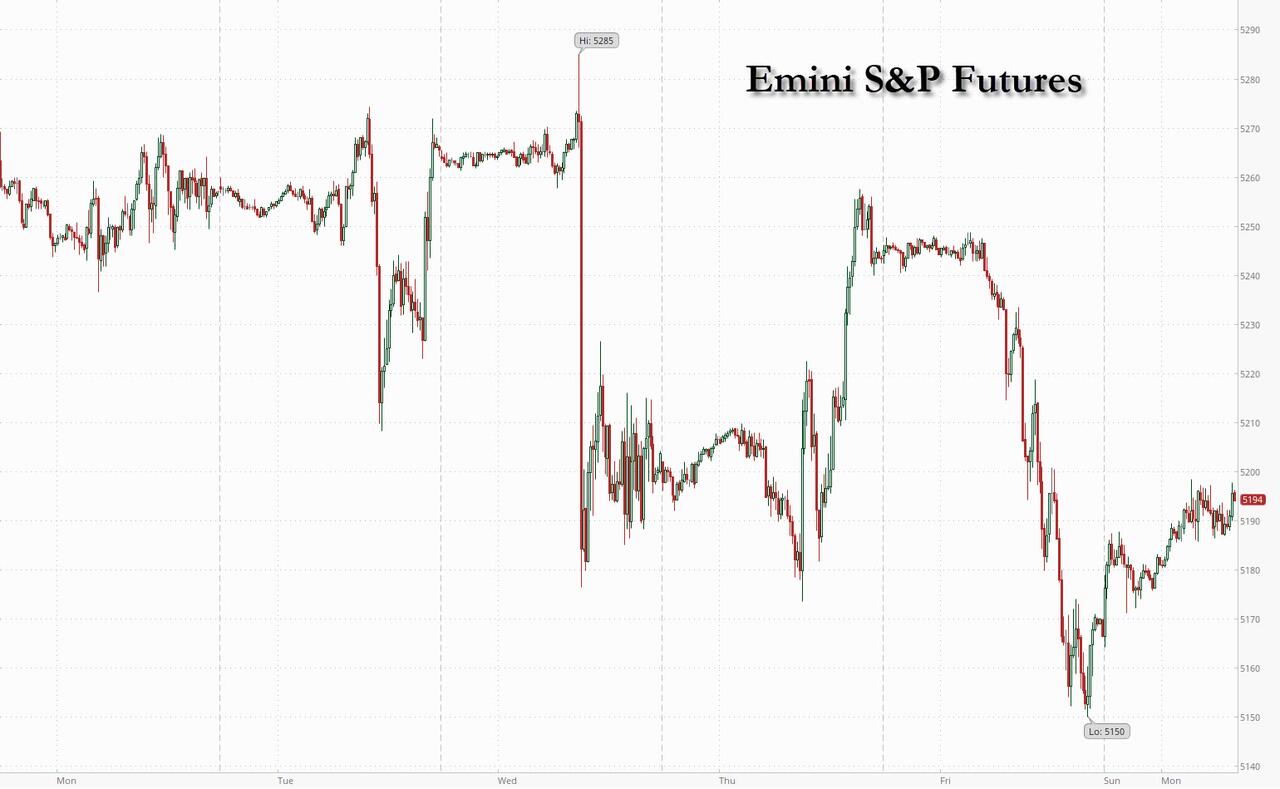
SPX futures have risen to 5158.90 thus far this morning.  The likely target may be Intermediate resistance at 5165.68.  The bounce is likely to be over this morning or early afternoon.  Should the SPX decline back toward the 50-deay, it may be poised for a panic decline either this afternoon or tomorrow.

Today’s options chain shows Maximum Investor pain at 5150.00.  Long gamma begins at 5165.00 while short gamma may start at 5140.00.

ZeroHedge reports, “Following the emotional rollercoaster of this weekend geopolitical “straight to DVD” soap opera, in which Iran pretended to retaliate to Israel’s embassy bombing with an attack that was meant to be a dud (and succeeded), which in turn was followed by an even more dramatic de-escalation by Israel in which after much saber rattling Netanyahu did…nothing, futures and yield are predictably higher, while oil is lower. That’s right: after digesting the weekend’s news and realizing that what just happened was one giant farce, global markets are broadly higher (except for Asia which is always a few steps behind), with European stocks ticking higher and US rebounding from Friday’s 1.5% selloff in the S&P 500. As of 7:30am, S&P futures were 0.5% higher with Nasdaq futs rising 0.6%; Treasuries slipped along with the dollar. West Texas Intermediate crude dropped below $85 a barrel, while base metals rallied with Aluminum at one point surging more than 9% after Russian supply was hit by US and UK sanctions. Gold reversed Friday’s losses to rise above $2,350 an ounce and bitcoin – which was the weekend’s only operating market and saw the initial risk-off reaction – reversed all losses and is back to unchanged. Today, the macro focus will be Retail Sales release. Feroli expects headline Retail Sales to print +0.3% vs. +0.4% survey vs. +0.6% prior. China will release key macro data at 10pm ET tonight.”


VIX futures declined to 16.60 this morning, near the 61.8% retracement value at 16.57.  The VIX Cycle may show strength through the rest of the week.  The Current Master Cycle may run into early May.

Wednesday’s monthly options chain shows Max Pain at 15.50.  Short gamma resides from 13.00 to 15.00.  Long gamma starts at 16.00 and may run up to 60.00.  The options market is on a hair trigger.

ZeroHedge observes, “VIX & MOVE have exploded

After months of a low volatility world we finally see some action in both VIX and MOVE. It is safe to say that derivatives markets are seeing more perceived risk than how actual equity markets are trading. Some even say that there is more upside to VIX from here. Our belief is that there is “catch-down” potential for equities from here, but that especially VIX probably has gone a little too far too fast.

What goes down must come up

Bond volatility has put in the biggest up move since September last year. Just when everybody agreed bond volatility was dead…


TNX has risen above 46.00 this morning as it journey’s toward the Cycle Top at 48.30.  The Cycles Model indicates that strength may persist through the week.

I have family matter to care for today.  Regular reports may resume tomorrow.


Posted in Published | Comments Off on April 15, 2024

April 12, 2024

3:05 pm

SPX appears to be declining through the 50-day Moving Average at 5102.22 today. There is still an opportunity for a bounce above that level.  However, a decline beneath that support may bring a waterfall event on Monday.


2:15 pm

Gold futures may have made their Master Cycle high this morning at 2448.75.  Since then it has fallen back to 2363.25.  This appears to be a Key Reversal, known to indicate a change in a major trend.  The blow-off top is known to to attract even the staunchest of investors, but seldom last forever.  Sell-side banks are all predicting higher gold prices.  

ZeroHedge remarks, “In investing, “Buy low, sell high” is among the most well-known sayings, and generally, it’s good advice. But with gold still holding near its historic all-time highs, central banks led by China are bucking the classic adage and smash-buying more, buying the top to fortify themselves against a global monetary and financial blow-up.

Last month marked the 17th in a row that the People’s Bank of China (PBOC) continued stacking gold. Notably, the bank typically reports lower numbers than its actual buying volume and is now also introducing a digital yuan to facilitate cross-border gold settlements.”


9:39 am

BKX has been on a sell signal for the past week after is crossed beneath the trendline at 100.50.  Today it sits above the 50-day Moving Average at 98.18, the final support before the dam bursts.  A bad report from a smaller bank would have been expected.  However, a miss by JPM does not set a happy tone for banks across the board.

ZeroHedge comments, “Q1 earnings season officially opened moments ago when JPM became the first mega bank to reports results, and even though JPM beat on across the board – and even unexpectedly released reserves instead of setting money aside for yet another quarter – the stock is lower by ~3% after Jamie Dimon had some gloomy words about the bank’s net interest income (which dropped in Q1) and the bank’s NII outlook for 2024 missed estimates. But before we get to all that, let’s start with the Q1 historicals which were solid across the board:”


9:10 am

Good Morning!

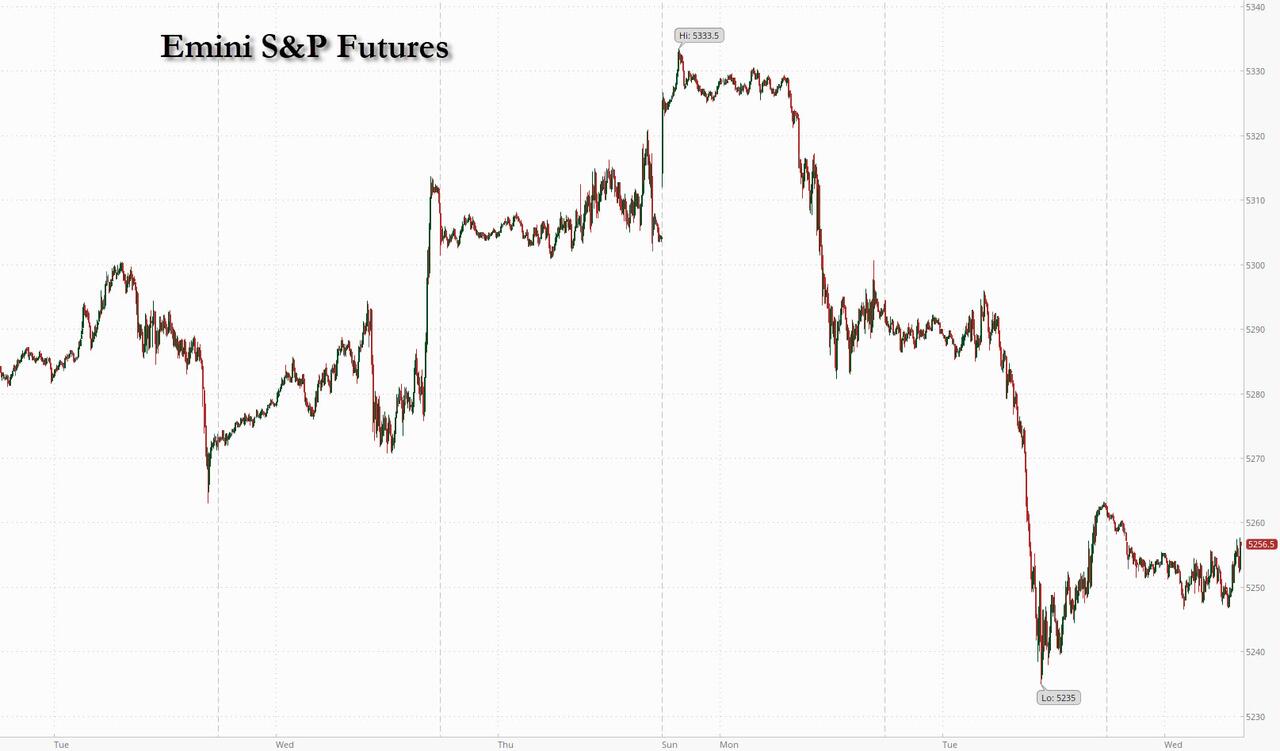
SPX futures have plummeted to a morning low of 5149.60 and threaten to go lower.  Remember that Intermediate support has been violated and SPX is on a selol signal, so this should be no surprise.  The next week should bring on an intensified decline with a possible waterfall panic.  This may be your last chance to exits longs, as the ensuing decline may be more than investors have been bargaining for.

Today’s options chain shows Maximum Investor Pain at 5200.00.  Long gamma starts at 5200.00 and intensifies at 5225.00.  Short gamma starts at 5175.00.

ZeroHedge reports, “Futures are tumbling this morning, hit by disappointing earnings and outllook from the largest US bank, JPMorgan whose stock is down around 3% in a soggy launch to Q1 earnings season, while growing fears of an imminent conflict between Israel and Iran have sent oil surging and futures sliding. As of 8:45am, S&P futures are down 0.7%, at session lows with Nasdaq also dumping after reports China has asked its telecom carriers to start phasing out foreign chips. The drop comes as we see safe having flows move capital into TSYs with bond yields sliding up to 10bps this morning. That said, the USD is higher again with the euro and cable sliding sharply. Commodities are mixed: oil and gold rally amid Middle East tension; base metals are lower amid lower-than-expected China exports (-7.5% vs. -1.9% survey vs. 5.6% prior), while the gold explosion documented last night continues, with gold futures trading just above $2,400 and spot trading just below. Today, the main focus will be banks earnings (C, JPM, WFC). We will also receive Univ. of Mich. Sentiment data.”


VIX futures have risen to a morning high at 16.28 and threatens to go much higher, as yesterday’s low began a new minor Cycle.  Particular Cyclical strength may show today and extend through the next week.

There is a battle going on in the options chain as 15.50 shows Maximum Pain for investors.  Short gamma is heavy beneath 15.00 while long gamma is gaining strength above 16.00.


TNX is making a slight correction as it surges toward its Cycle Top at 48.28.  Today may bring a supercharged surge of strength to yields as its nears the end of its Master Cycle.

ZeroHedge reports, “After two consecutive ugly auctions (and in the case of yesterday’s 10Y reopening, very ugly), moments ago the Treasury completed the week’s coupon issuance when, on the day when the BLS published a doctored PPI report to boost market sentiment, it sold $22 billion in 30Y paper in what was yet another ugly auction.

The high yield on today’s sale stopped at 4.671%, higher than last month’s 4.331% by 34 bps and also tailing the When Issued 4.661% by 1 basis point, the first tail for the 30Y tenor since last November.”


\

Posted in Published | Comments Off on April 12, 2024

April 9, 2024

8:00 am

Good Morning!

SPX futures are being pressed into an ever-smaller formation, appearing to be flat, but in fact, revealing a Triangle Wave B.  Today’s Cycles Model suggests a brief spike to 5220.00-5225.00 before a strong reversal.  SPX is on a sell signal.

Today’s options chain reveals Maximum Investor Pain at 5205.00.  Long gamma may begin at 5225.00 while short gajmma lurks beneath 5200.00.

ZeroHedge reports, “US equity futures are trading in a narrow range, swinging between gains and losses as bonds climbed, clawing back some of Monday’s slump which sent yields to the highest since last November in the buildup to US CPI print tomorrow that is crucial to the Fed’s decision when it will start to cut interest rates; Government debt in the UK and Germany followed suit, with yields falling across the curve after a 20-year UK bond sale drew record demand from investors. As of 8:00am, S&P futures were up 0.1% but traded tightly around the unchanged line as they extended Monday’s flat close on Wall Street, when trading was the thinnest since Christmas. Nasdaq futures gained 0.2% while Europe’s Estoxx 50 was down about 0.5%, with technology and industrials leading to the downside. Commodity markets are higher lead by Energy and Metals, with Gold hitting a new record high, rising as much as $25 to $2,365 before paring gains. The macro picture is light today but keep an eye on the 3Y auction, which may give some cues to investor positioning ahead of the CPI.”


VIX futures rose to 15.51 this morning, even as the SPX futures probe higher.  There is a possibility of the VIX declining to the mid-Cycle support at 14.73 today.  It may be looked upon as a buying/hedging opportunity.

Wednesday’s options chain reveals Max Pain near 15.00  Short gamma resides at 14.00 while long gamma begins at 17.00 and remains strong to 25.00.


TNX futures have been easing lower to 43.79 after Monday’s spike high.  It appears that Stock Charts may have a data feed issue since the charts have not been updated since Friday.  Today’s Treasury Auction shows  $65 billion in 42-day bills and $58 billion of 3-year notes.  Tomorrow shows $39 billion of the 9-year 10-month notes being offered.


USD futures are sagging down to 103..73 thus far.  Both Intermediate support at the 50-day Moving Average are at 103.70.  It would do well to see if these supports hold.


Gold futures rose to an overnight high of 2384.35 on day 253 of the Master Cycle.  The odds of a reversal by the end of the week are high.  cAUTION IS ADVISED.

ZeroHedge remarks, “April 8th: Bullion Bank (Citi) raises short term price targets for Gold and Silver 9% and 16% respectively, increasing price targets to $2400 and $28 over the next 3 months. with topside price spikes of $3,000 and $32.00 this year now on the table.”


Posted in Published | Comments Off on April 9, 2024

April 8, 2024

8 :15 am

Good Morning!

NDX futures have been consolidating inside Friday’s trading range over the weekend thus far.  There appears to be an attempt to hold the trendline at 18100.00 with a backup support at the intermediate level at 18053.00.  The Cycles Model shows today as a day of strength.  Should NDX remain above its Intermediate support, we may see an attempt to bounce above Friday’s high at 18202.96.  However, a reversal beneath Intermediate support may produce a waterfall event.

Today’s options chain shows Maximum Investor Pain at 18100.00.  Long gamma may begin immediately above that level, while short gamma emerges beneath 18050.00.

ZeroHedge observes, “Best of times

Buybacks + inflows have stepped up and created a very supportive flow dynamic. It has been the best of times and extreme from a historical standpoint (if you disregard the post-COVID bump).

Source: Deutsche


We are running out of equities

Global equity supply the most negative it has been since 1999. Year to date, global public equity supply has declined by $120 billion. This is three times higher than the $40 billion decline that occurred in 2023. We are also on track for a third straight year of declines for the first time in history.”


SPX futures are consolidating around 5200.00 this morning.  The Diagonal trendline provides overhead resistance near 5225.00.  In the meantime, Intermediate support comes in at 5143.43, where the sell signal is confirmed.  The Cycles Model indicates a show of strength may be at hand.  That indicates the trendline (5225.00-5235.00)may be tested again.  A breakdown at the trendline may produce a waterfall event.

Today’s op-ex shows Max Pain at 5205.00.  Long gamma starts at 5220.00 while short gamma begins abruptly beneath 5200.00.

ZeroHedge reports, “US equity futures are flat, trading around 5,252, having rebounded from session lows even as 10Y yields extend their ascent and the USD strengthens as traders further pare expectations for interest-rate cuts in the face of resilient readings on the US economy. As of 8:00am, S&P and Nasdaq fuitures are both unchnaged while major European markets are mostly higher with only Spain/UK in the red. Treasury yields rose to their highest levels of the year across the curve, with the 10-year climbing above 4.45%. Interest-rate swaps imply around 60 basis points of US monetary easing this year, making two cuts the most likely outcome. On Friday, the chance of a third cut was still above 50%. European bond yields are also higher, but yield curves are not moving in tandem. Commodities are mixed with Energy lower, Metals higher, and Ags mixed. Crude oil turned lower after last week’s strong gains after Israel said it will pull some troops from Gaza. Brent futures briefly dropped below $90-handle before reversing losses. Gold also reversed early losses and printed a fresh record above $2,350 before paring gains. Looking at the calendar, Mon/Tues are light macro days ahead of Wednesday’s CPI print, Thurs’ ECB mtg, and Fri’s Bank earnings which launch Q1 earnings season; we algo get at least 7x Fedspeakers where investors will see if a hawkish pivot is building if CPI prints hotter than expected. While the market is trimming rate hike estimates both Goldman and JPM still see at least 3x rate cuts.”


VIX futures rose to 16.49 as tensions arise.  The elevated VIX over the weekend shows that trending strength has been in play and may make a greater showing in the cash market this week.

Wednesday’s op-ex shows Max pain at 15.00.  There is a small contingent of short gamma at 14.00.  Long gamma starts at 17.00 and builds to 25.00.


TNX futures have risen to 44.67 this morning before moderating a bit.  The data feed to Stock Charts does not appear to be working, so I will replace the current chart with a new one as it becomes available.  The Cycles Model suggests another two weeks of rising yields, indicating a possible rally to the Cycle Top resistance at 48.28.

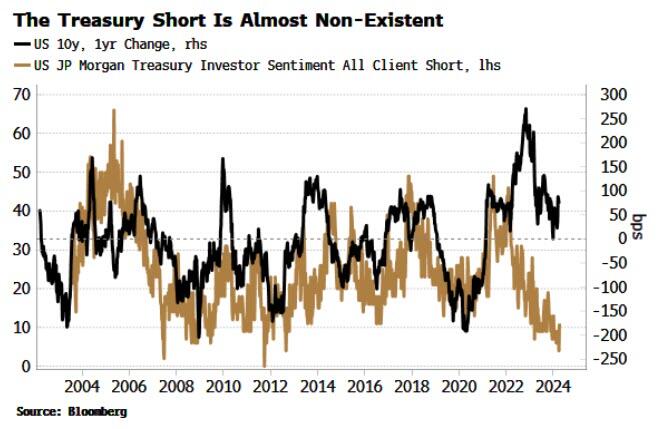
ZeroHedge remarks, “Survey data shows that outright shorts in US Treasuries are near lows. But investors are missing a trick as inflation risks point to higher bond volatility and yields.

JP Morgan’s Treasury Survey tracks their clients’ positioning in Treasuries, asking them whether they are long, neutral or short. The net of the positions is close to flat, but outright shorts are unusually low, with the number of clients saying they are positioned that way near the nadir for the 20-year history of the survey.


Posted in Published | Comments Off on April 8, 2024

April 5, 2024

9:52 am

Good Morning!

Yesterday was noteworthy in the fact that the Cycle Top, at 5264.65, formerly support for the past two months, became resistance in the SPX.  Once that was tested, SPX declined sharply to Intermediate support at 5140.62, where it bounced.  SPX may now test the trendline near 5200.00, although it may reverse short of that target.  The next level of support is the 50-day Moving Average, at 5074.05.  Beneath that lies the 1987 trendline and the 100-day Moving Average, at 4875.02.  The Cycles Model suggests a possible month of decline ahead.  Trending strength may switch to the downside early next week.

Today’s options chain shows Max Pain at a very crowded 5200 for both puts and calls.  While clls occupy a small majority above that level, puts now dominate the options chain beneath 5200.00.

ZeroHedge reports, “US futures rebounded from yesterday’s late day rout even as European stocks slumped the most in almost two months and Asian markets tumbled the most in a month, tracking Thursday’s broad market retreat as oil prices held near five-month highs above $90 and investors braced for today’s jobs report where the whisper is of a hotter than expected print. As of 7:30am, S&P futures rose 0.3% after tumbling 1.4% yesterday; even with the modest gain the index is on track for its biggest weekly decline since mid-February.  Europe’s Stoxx 600 slid more than 1%, following the previous session’s sharp retreat on Wall Street and losses in Asia earlier on Friday. US and euro-area bond yields inched higher as fears of an escalation in the Middle Eastern conflict kept Brent crude futures near $91 a barrel, fanning inflation concerns. The USD is stronger, bitcoin has resumed selling, commodities are higher led by Energy products and base metals. From a macro perspective, NFP is the focus, survey is +214k survey vs. BBG whisper +230k; both are down from the +275k prior.


VIX is consolidating near the upper end of yesterday’s trading range.  The Cycles Model suggests that a burst of trending strength may be imminent.  The February high is likely to be overcome.

Wednesday’s op-ex shows Maximum Investor Pain at 14.00.  Negative gamma beneath that level is scarce, while positive gamma is building near the October high.

ZeroHedge observes, “What started to be a rather stable and uneventful session, ended in some turbulence after a sharp reversal lower triggered by Middle East geopolitical headlines (a spike in oil) and hawkish fed speak.

All sectors finished in the red, with 430 S&P names finished lower (NVDA, GOOG/L, AMD, and AMZN contributed to 30% of move lower). Momentum, AI & New Technology, and Retail Favorites were among the hardest hit all down -2%. NDX broke through its 50dma (17,903…keep an eye on 100dma = 17,134).”


TNX may be consolidating, although at a higher level today.  The Cycles Model suggfests trending strength building over the next two weeks.  The Cycle Top at 48.28 appears to be an appropriate target.


BKX is pressing down on its 4.5-month trendline at 100.00 this morning.  Loss of upward support will be critical and lead to a confirmed sell signal.  This is also a clear sign that liquidity is drying up.


Posted in Published | Comments Off on April 5, 2024

April 4, 2024

8:15 am

Good Morning!

NDX futures rose to an overnight high of 18279.30, nearly making the 61.8% Fibonacci retracement at 18292.00.  The Cycles Model suggests a probable brief retracement high this morning prior to resuming the decline. Intermediate support and the Diagonal Trendline lie at 18043.19, beneath which a confirmed sell signal may be made.

This morning’s options chain shows Maximum Pain for investors at 18160.00.  Long gamma may start at 18170.00 while short gamma may begin at 18150.00.


SPX futures have risen to an overnight high of 5234.80 thus far, a near-61.8% retracement.  There may be a brief probe to a new retracement high at the trendline in the cash market followed by a likely resumption of the decline.  This may fulfil the trending strength indicated by the Cycles Model yesterday.  Remember, the trend is still “higher” at this juncture although a reversal may have been made.

Today’s op-ex shows Max pain at 5220.00.  Long gamma may begin at 5225.00 while short gamma may start at 5215.00.

ZeroHedge reports, “US equity futures are higher with both Tech and small-caps outperforming, while the dollar is lower even as yields are higher from Wednesday’s close. As of 7:50am, S&P futures were 0.3% higher and Nasdaq futs rose 0.4%, boosted by Powell’s comments that recent inflation figures did not “materially change” the overall picture while the latest ISM Services print was far less inflationary than the ISM Manufacturing print, in fact bizarrely so. In Europe, major markets are also all higher as part of a global risk-on tone.  Bond yields are +1-2 bps, even as Bloomberg’s dollar index extended its slide for a third day, following its biggest one-day fall in nearly four weeks.  In commodities, energy is a tad lower with Brent trading just below $90, metals are mixed, and Ags are stronger; copper – which as we noted previously could be the first “AI commodity” is the notable outperformer. Today’s macro data focus is on jobless claims but likely will be ignored with the jobs report tomorrow; we also get seven Fed speakers today.”


VIX futures sagged to a low of 14.03 this morning, near the 50% retracement level at 13.92.   It is odd that the retracement percentage in the VIX is lower than that of the SPX.  The Cycles MOdel shows the VIX gaining in trending strength by this weekend.

Next Wednesday’s op-ex shows Max Investor Pain at 14.50.  Short gamma has moved up to 14.00, while long gamma begins at 16.00.  There seems to be no rush to buy protection.


TNX has pulled back from its breakout high made yesterday.  The rally may resume, in strength, after a brief consolidation.

ZeroHedge observes, “MOVE inching higher

MOVE closed marginally higher yesterday. The latest “bounce” in rates volatility has actually been one of the bigger moves higher in a while. From recent lows, but still…”


Posted in Published | Comments Off on April 4, 2024

April 3, 2024

10:27 am

BKX is slowly losing its grip on the retracement rally.  It made an early Master Cycle high March 28, on day 248 and may need another week to prove the high.   In the meantime, critical support lies at the trendline at 101.00-101.50.  Beneath that level is a sell signal with confirmation at Intermediate support at 98.83.  A breakdown may lead to a broader sell-off in nearly all assets, as investors flee to cash.

ZeroHedge remarks, “There are more dormant office towers in the United States than at any point since 1979, according to a new report from Moody’s Analytics, which began tracking office leasing vacancies that year.

The rising supply of office space is due to a combination of surging remote and hybrid work that forces companies to reduce corporate footprints. Also, companies are exiting imploding progressive cities and high-taxed blue states for red ones while downsizing space.

In the report, office tower vacancies rose to a record 19.8%, up from 19.6% in the fourth quarter of 2023.”


8:25 am

Good Morning!

NDX futures retraced to 18132.30 before slipping back toward the trendline and Intermediate support at 18027.00.  It is on an aggressive sell signal which may be confirmed beneath the abovementioned trendline.  NDX marked its high on March 21.  SPX made its high on March 28.  Should those highs remain intact, the trend may be down until mid-May.

Today’s options chain shows Maximum Investor Pain at 18150.00.  Long gamma may begin at 18200.00, while short gamma may start at 18100.00.

ZeroHedge reports, “Taiwan Semiconductor Manufacturing Co., the leading contract chipmaker for Apple Inc. and Nvidia Corp., shuttered some of its chipmaking capacity and evacuated plants after the biggest earthquake in 25 years rocked the island nation, just east of mainland China.

Taiwan plays a significant role in manufacturing advanced chips for artificial intelligence, smartphones, computers, and electric vehicles. The country is estimated to produce 80% to 90% of the highest-end chips.”


SPX futures back-tested the trading channel trendline at 5220.00, but failed to overcome it.  Futures are lower but have not declined beneath short-term support at 5189.00.  SPX made its all-time high on March 28 (day 245) and has not challenged that level since then.  Intermediate support lies at 5126.28 and may provide support for a bounce.

Today’s op-ex shows Max Pain at 5210.00.  Long gamma starts at 5225.00 while short gamma emerges beneath 5200.00.

ZeroHedge reports, “US futures are down small with Tech underperforming and small-caps flat, as rates held at 4 month highs, and Brent is about to rise above $90. As of 8:00am, both S&P and Nasdaq futures are down -0.2%, with yields higher pre-market ahead of Powell’s 12.10pm ET speech; despite his dovish rhetoric at the Mar 20 Fed Meeting press conference investors are nervous of a hawkish pivot according to JPM. This comes amid a surge a commodity prices and a spike in geopolitical tensions; pre-market all 3 commodity complexes are higher with gold the notable laggard despite USD being flat (although gold lagging these days means it hasn’t hit a new all time high in the past 15 minutes). Today’s macro focus is on ADP (has not been predictive of the brutally manipulated NFP print), ISM Services and 2x Fedspeakers, including Powell.”


VIX futures appear to be consolidating above the mid-Cycle support at 14.70.  Trending strength is growing with a possible peak over the weekend and each successive weekend through the month of April.  This may not be a coincidence, as the Fed has been attempting to downplay and delay the reports of bank problems until the close on Friday.

Today’s op-ex shows Max Pain at 14.50-15.00.  Short gamma appears at 14.00, but long gamma begins at 16.00 shows strength at 23.00.

ZeroHedge notes, “5200 matters

This is where the lower part of the perfect Madoff channel comes in, as well as the 21 day moving average. 5200 is the make or break level.”

Source: Refinitiv


TNX continues to show strength as it advance above this year’s previous highs.  The rally may last another 2-3 weeks, according to the Cycles Model.

ZeroHedge remarks, “Positioning in US Treasuries is becoming less long as the risk of persistently higher yields increases from a cyclically strong US and global economy.

Leading data have been vindicated in projecting a US and global cyclical upturn that coincident data are now unequivocally confirming. Monday’s release of the March ISM showed the index is back into expansion territory, matching the message from the manufacturing PMI.

The US manufacturing ISM is not only the best cyclical barometer of US growth, it is also the best single gauge of global growth given the sector’s outsized importance to the world economy.”


USD futures appear to be consolidating after yesterday’s potential Master cycle high on day 259.  Should it take hold, the reversal may test the mid-Cycle support at 103.76.  Should support hold, USD may be considerably higher by the end of May.


Gold futures have risen to a new all-time high at 2308.85 on day 247 of its master Cycle.  Vigilance should be the by word as gold may reverse at any time in the next week.  The decline may be greater than most would imagine.

ZeroHedge comments, “The rally in the gold price has left me non-plussed … who is behind it and why ? Rather like an Agatha Christie murder-mystery novel, with evidence thin, the culprit or cause may be deduced by excluding what it is not … and what remains, is.

Spoiler alert … I am really not sure of the answer, but follow me … it’s fun anyway. ”


Crude oil futures have advanced to a morning high at 86.08 as it continues its rally to the Cycle Top resistance at 90.44.  There may be approximately 3 weeks left in this rally, so it may be doable.  However, there may be a structural resistance near 86.60 that may impact the rally.  Given that information, it is likely that a pullback toward mid-Cycle support at 79.75 may be in order before pressing higher.

ZeroHedge remarks, “US crude futures pierced $85 for the first time since October, the latest milestone in a rally driven by OPEC+ production cuts, strong demand and heightened geopolitical risks.

As Bloomberg reports, oil has jumped this week as tensions rise in the Middle East, with Iran vowing revenge on Israel for an airstrike on its embassy in Syria that killed a top military commander.

After last week’s surprise crude build and big jump in stocks at the Cushing hub, traders were looking for a slowing build…”


Posted in Published | Comments Off on April 3, 2024

April 2, 2024

10:22 am

SPX has fallen beneath its Diagonal Trendline at 5220.00, giving a sell signal.  It has also challenged its Short-term support at 5189.00.   A further confirmation lies beneath Intermediate support at 5129.32.  Of critical concern is the 1987 trendline near 4900.00, beneath which lies the possibility of a greater decline.


8:15 am

Good Morning!

NDX futures have declined to 18132.60 thus far this morning as the uptrend weakens.  Critical support lies at the trendline and Intermediate support at 18019.69, beneath which lies a sell signal.  Further confirmation lies beneath the 50-day Moving Average at 17822.27.  Once the reversal is confirmed, the Cycles Model suggests a potential decline lasting until mid-May.  Of critical importance to the uptrend is the 1987 trendline which lies just beneath 14000.00.

Today’s options chain shows Maximum Investor Pain at 18275.00.  Long gamma may begin at 18300.00 while short gamma may proceed beneath 18250.00.

RealInvestmentAdvice comments, “During running bull markets, much commentary is written on why this time is different and why investors should not worry about market corrections. One such piece was written recently by Fisher Investments. To wit:

“After the S&P 500’s 26% return last year and this year’s strong start, many investors are worried – understandably – that this bull run is getting ahead of itself. “‘”


SPX futures have slipped beneath the Cycle Top support at 5231.00 for the first time since February when it also rose above the 1987 trendline.  This may justify an aggressive sell signal, although a trendline sell signal lies just beneath 5200.00 where SPX is closing in.    Intermediate support lies at 5120.97, giving further confirmation to the sell signal.  Confirmation of the larger uptrendlies at the 1987 trendline at 4900.00.

Today’s op-ex shows Max Pain at 5245.00.  Long gamma may begin at 5250.00 while short gamma may reside beneath 5225.00.

ZeroHedge reports, “US equity futures are sliding as bond yields spike to 4.36%, the highest level since November, and the price of Brent crude rises to a new five-month high above $89 driven mostly by supply/demand dynamics but a geopolitical fear premium over the brewing Israel-Iran conflict begins to build, and as fears that the Fed may not cut rates in June start to percolate. The rest of the commodities complex is also pushing higher with strength in metals notable as Ags come from sale and gold jumps right back to all time highs despite the recent strength in the dollar.  As of 7:50am, S&P and Nasdaq futures drop 0.4%, as health insurance stocks tumbled after regulators didn’t boost payments for private Medicare plans like the industry had come to expect; Mag7 names are mixed with Semis up small despite NVDA sliding. In Europe, most markets are mostly higher after reopening after the Easter holiday with only Spain in the red: energy, AI, and semis the best performing segments with additional support from banks, as regional curves bear steepen. The risk-on tone in APAC where HK showed significant outperformance. The yield curve is steeper, and the Bloomberg dollar index dropped. Bitcoin slumped after several sharp sell orders hit futures during Asian trading. Today’s macro data focus is on JOLTS and 3x Fedspeakers.”


VIX futures have risen to 14.54, giving a buy signal.  The Cycles Model suggest growing strength, especially on weekends through mid-May.  This may be due to authorities hiding bad news until the weekends, hoping that it will blow over by Monday.  The unusually low stretch of volatility may be about to end.

Tomorrow’s op-ex shows Max Pain at 14.00  Short gamma may reside at 13.00-13.50 while long gamma starts at 15.00 with outliers at 18.00 and 40.00.


TNX has broken above its February high, confirming the buy signal given last Thursday.  The Cycles Model suggests the rally may extend to the week of April 15.  A natural target may be the Cycle Top at 48.28…or higher.  Our lawmakers don’t know how to control their spending. 


Gold futurtes hit a nominal new high this morning at 2287.35 on day 246 of the current Master Cycle.  Gold may be in its final probe to all-time highs before a major correction.  Thus far there is no weakening of the uptrend.  Once the decline manifests, the nearest suport at which a signal may be given is the Cycle Top at 2167.62, approximately 5% beneath its current high.   Be aware that a change in trend may happen rather quickly.


Posted in Published | Comments Off on April 2, 2024

March 28, 2024

10:15 am

BKX may be making its last stand on day 245 of the Master Cycle.  A possible reason for the Cycle high ending early may be “window dressing” where sectors may be made to look good for the quarter-end.  The Wave structure appears complete.  Thus far there have been no outright bank failures.  That may all end as the kicked can may be too damaged to withstand another nudge.

  • CRE vacancies and defaults are rising as major corporations are downsizing their real estate footprint.
  • The purchase of treasuries may decline as quarterly pension rebalancing is complete, which may cause yields to rise.
  • The Bank Term Funding Program (BTFP) has ended.  This may erode investor confidence in banks.
  • Bank profitability has eroded as yields have risen, causing savers to choose money markets with more competitive rates.


8:30 am

Good Morning!

SPX futures made a minimal advance overnight to 5251.60, on its way to5300.00.  Today is day 245 in the current Master Cycle, as the reversal door opens wider.  But first, the spike high must be made.  The Cycle Top support lies at 5209.86.  Beneath that lies an aggressive sell signal.  The Diagonal trendline and short-term support lie at 5170.00, confirming the sell signal.  Additional support lies at 5107.04, beneath which resides further confirmation of the sell signal.  Market tops are a process, not an event, unless a Key Reversal is made, breaking multiple supports.

Today’s options chain shows a close race with 5245 as Maximum Pain, with long gamma beginning at 5250.00 and shor gamma possibly beginning at 5240.00.

ZeroHedge reports, “Stock futures are pointing to a flat open on the last trading session of the week, month, and quarter, following a late-session spike that took the S&P 500 to yet another record as the much anticipated quarter-end pension dump (as big as $32BN according to Goldman failed to materialize, but may very well show up today). As of 7:45am ET, both Nasdaq and S&P futures were down 0.1% after Fed Governor Christopher Waller poured cold water on the path to lower interest rates, saying there’s no rush to cut rates given recent “disappointing” inflation figures.

The broadest equity index is set for a gain of 10% for the first three months of the year, with the Nasdaq 100 just short of a 9% rise. Europe’s Stoxx 600 benchmark also notched up another record as Arnaud Cayla, deputy CEO at Cholet Dupont Asset Management, said: “Investors have no reason to sell”, and sure enough, a look at either the weekly S&P candle chart which is up 19 of the past 22 weeks…”


VIX futures are consolidating inside yesterday’s trading range.  Should VIX make a new low today, it may be on day 280 of the Master Cycle, an unusually long duration.  However, other forces may be at work, extending the VIX Cycle.  The  50-day Moving Average is at 13.71 while the mid-Cycle support/;resistance lies at 14.72.  VIX has been ignored as a hedge for so long that it may take a rally above the February peak at 17.94 to wake up investors to looming danger.

Next Wednesday’s VIX ooptions expiration shows Maximum Investor Pain at 14.00., with very little short gamma.  Long gamma rises up at 15.00 and extends to 40.00.


TNX tested its 50-day Moving Average at 41.86, then rallied through the 200-day Moving Average at 42.22 toward the mid-Cycle resistance at 42.57, where a possible new confirmation of the buy signal lies. TNX appears to be at a Trading Cycle low and new strength to the upturn may come next week.  This rally has the capability of running strong through mid-April.

There may be an answer for why yesterday’s 7-year Note auction went so well.  In short, pension rebalancing may be the culprit.  It is a mechanical process and takes no heed to market conditions until something breaks…

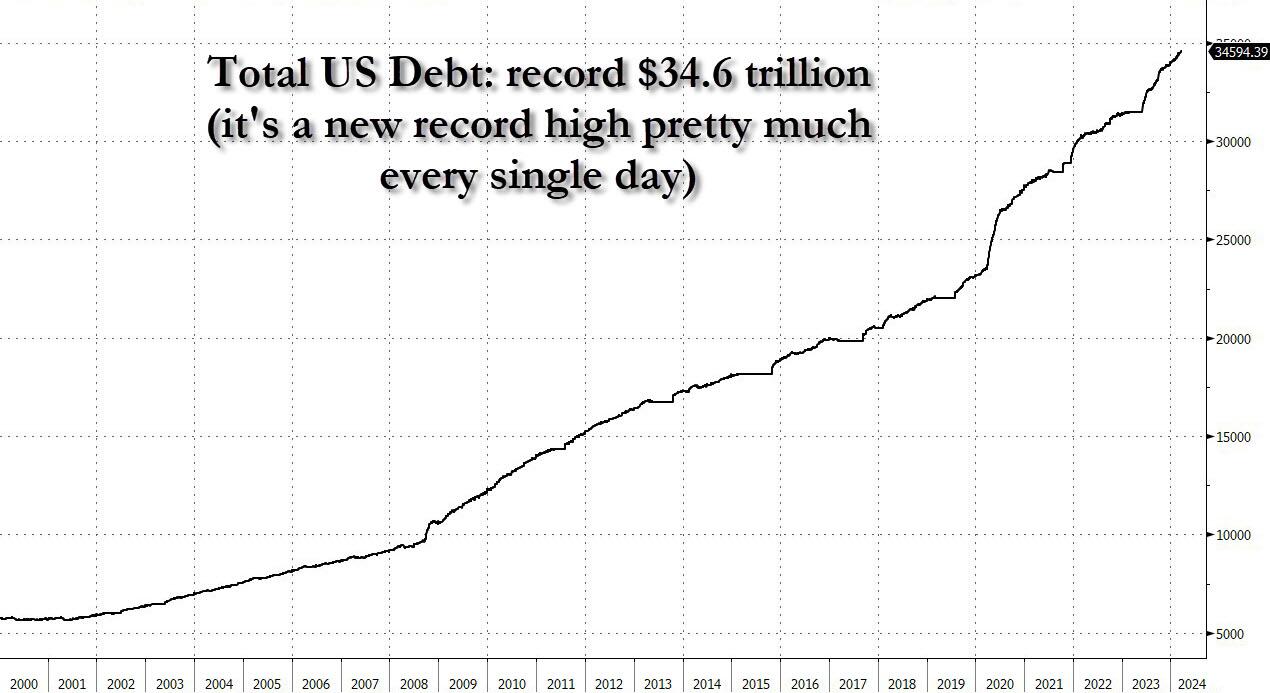
ZeroHedge remarks, “We’ve been pointing it out for so long – in fact, for most of our 15 years in existence – that it has become more of a chore than actual reporting, especially since the “number only go up“, as it hits a new all time high virtually every day. We are talking, of course, about the exponential curve that is the US debt, arguably one of the most boring and at the same time, most exciting topics of all time (because one day the “number go up no more” and you want to be far, far away when that happens).

Perhaps the catchiest observation we made on the trajectory of US debt was last September when we first noted that it is rising by $1 trillion every three months, or every 100 or so days…”

ZeroHedge adds, “Crashing is maybe too strong of a word, but bond volatility continues coming off sharply. The MOVE closed at the lowest levels since early February 2022.”


USD futures consolidated overnight after yesterday’s surge.  At day 253-254, yesterday or today may give USD a Master Cycle high.  This suggests a possible decline into mid-May.  A possible target may be the Cycle Bottom at 100.41.


Posted in Published | Comments Off on March 28, 2024

March 26, 2024

12:53 pm

SPX is advancing slowly from its pullback, but the Wave Structure requires one final push higher.  The likely target may be 5300.00.  Some analysts are anticipating a blow-off top, but the trend channel is straight and narrow, suggesting that the trend channel is likely to be obeyed.  The shadow banking system, which has funded this rally is not eager to start another speculation binge.  There is no reason to sell.  However, a 10-year yield above 43.50 may dampen the animal spirits.  The trading channel trendline has risen to 5163.00.

ZeroHedge comments, “Stock market optimism is at full throttle after central banks’ rate-cut reassurances, leaving investors with no reason to sell and bears with little to do but await catalysts that might derail this rally.

The Federal Reserve’s signal that three interest-rate cuts are still on the cards for this year has just propelled Europe’s Stoxx 600 index to its ninth straight week of gains, the longest winning streak in 12 years. While the Stoxx and its blue-chip counterpart the Euro Stoxx 50 may look a tad overbought, there is no real sign of the excesses that would trigger technical red flags.”


8:25 The Feast of the Annunciation moved to April 8

Good Morning!

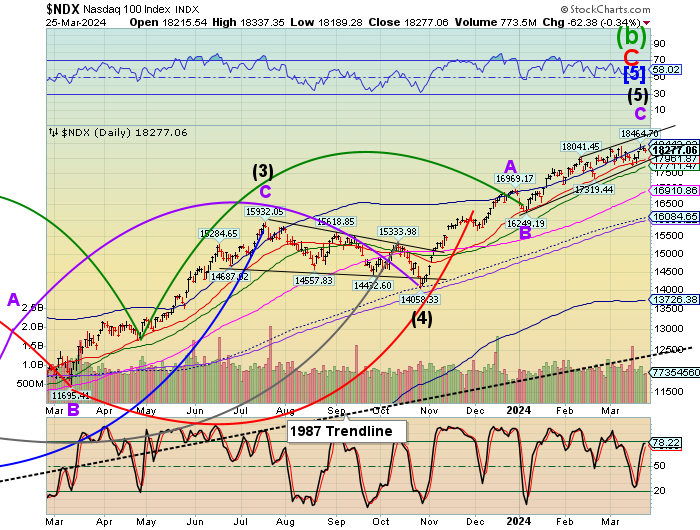
NDX futures have risen to a morning high of 18327.20 as it makes a final probe into its all-time high.  The anticipate high may be near 18500.00.  Today is day 243 in the current Master Cycle, which means the turn window has opened, leaving two weeks to the anticipated turn date.  Note that, at 258 days, the turn date is an average with reversals occurring about two weeks plus or minus that date. Intermediate support is at 17961.82, parallel to the Ending Diagonal trendline.  A sell signal may be obtained beneath that level.

Today’s option chain shows Maximum Investor Pain at 18290.00.  Long gamma may begin at 18300.00 while short gamma resides beneath 18250.00.

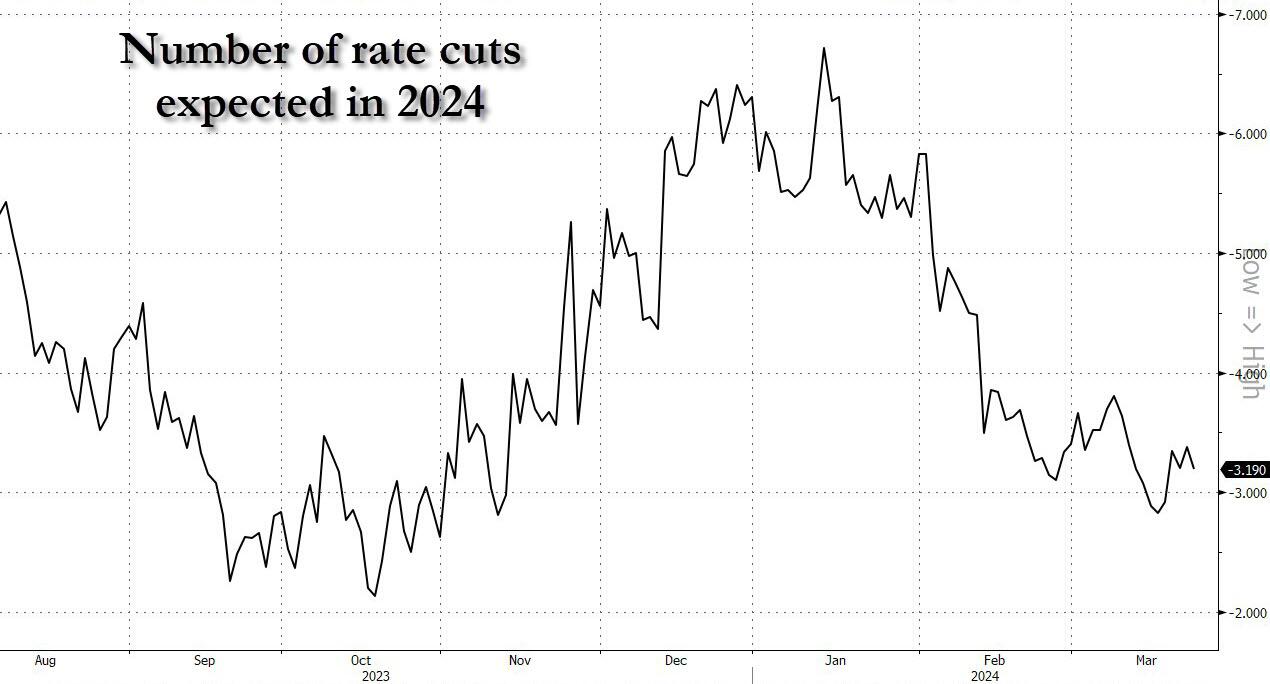
ZeroHedge observes, “Economists and strategists tend to look at everything through the lens of interest rates, as if these are all important in explaining market conditions. But if we look at this year’s shift in money markets, we’ve seen a significant recalibration of expectations, from seven to three Fed cuts, while stock indices hit one all-time high after another and credit spreads continue to tighten.

It suggests that central bank policy may not be the primary force at play. Instead, if it’s collective risk appetite that drives liquidity, market movements are largely independent of central bank action. The concept of endogenous money creation explains how, arguing that the (shadow) banking system itself influences the money supply through lending and borrowing.”


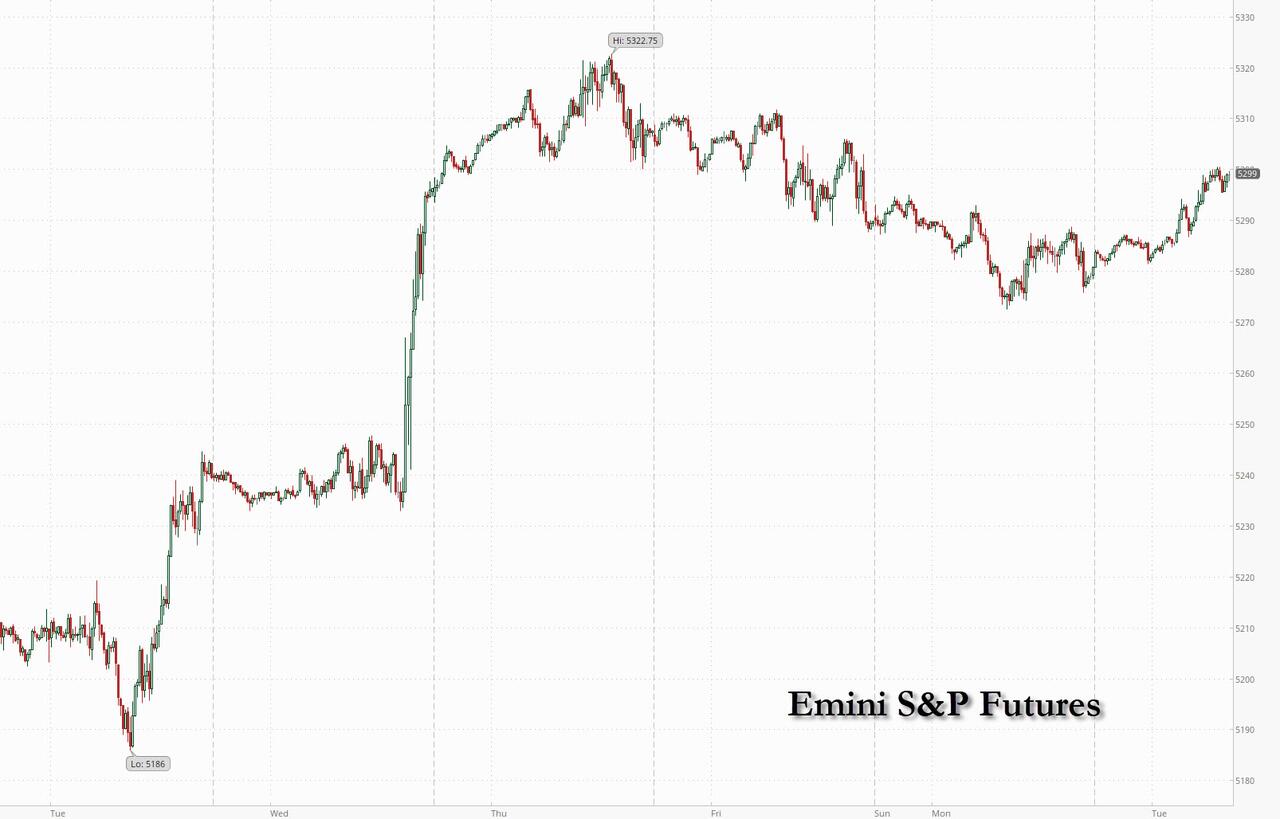
SPX futures have risen to a morning high at 5241.90 as SPX makes its final probe to its all-time high.  The anticipated target for this final move may be 5300.00 over the next few days.  However, the Cycle Model suggests that there may be another two weeks left in the current Master Cycle.  The Ending Diagonal trendline is near 5150.00 while Intermediate support lies at 5092.00.  A decline beneath either may constitute an aggressive sell signal.

Today’s options chain reveals Max Pain at 5230.00.  Long gamma may begin at 5250.00 while short gamma is likely beneath 5200.00.

ZeroHedge reports, “It’s as if Monday’s modest dip never happened: S&P futures are trading are higher, surpassing Monday’s highs, with both Tech and small-caps outperforming, as investors keep a close eye on any potential market impact from the collapse of a major commuter bridge in Baltimore after it was rammed by a container ship. As of 8:00am ET, S&P futures were 0.4% higher, erasing Monday’s 0.3% drop, while Nasdaq futures gained 0.5%. Europe’s Estoxx 50 is similar, trading at multiyear high with utilities and financials outperforming. According to a JPM morning note, it is unclear if yesterday’s moves were tied to month-end/quarter-end rebalancing but generally those flows occur before the last day of the period. USD weakness continues as the yen just refused to drop no matter what; commodity performance is mixed with gold approaching ATHs and oil trading at a 5 month high. Today’s macro data calendar is busy with focus on Durable/Cap Goods, Home price indices, Consumer Confidence, and regional activity indicators (Dallas, Philly, and Richmond); we also get a $67BN 5Y bond auction; let’s see if it goes as smoothly as yesterday’s 2Y auction.”


VIX futures declined to 13.05 this morning.  The Wave structure indicates that VIX may make one further decline beneath the 12.40 low.  Should VIX make a new low tomorrow, it will have stretched its Master Cycle to an unusually long 279 days.

Tomorrow’s options chain shows Max Pain at 14.00  Short gamma lies at 13.50 while long gamma begins at 14.50.

ZeroHedge remarks, “The VIX reset

Zoom out and you see that VIX has spent a lot of time in the 12-16 range over the past 15 years. We saw low teens VIX, and even sub 10, during parts of 2017. VIX around 12 isn’t far from the “natural” floor, but we can stay low for extended periods of time.”

Source: Refinitiv


TNX may have bounced off Intermediate support at 42.32 this morning as it continues upward until mid-April.  A potential target may be the Cycle Top at 48.27.

ZeroHedge observes, “Greater inflation expectations and receding recession risk leave the interest rate cuts priced in for the Federal Reserve more vulnerable than in the UK or Europe.

The market currently sees a similar amount of rate cuts in 2024 for the US, UK and euro area, with ~80 bps seen for the Fed and BOE and just over 90 bps expected for the ECB. The US is more exposed to rising inflation, which is beginning to be reflected in the market’s expectations. The CPI-fixing market has started marking up its estimates of where inflation is anticipated to be over the next 12 months after a protracted period of marking them down.”


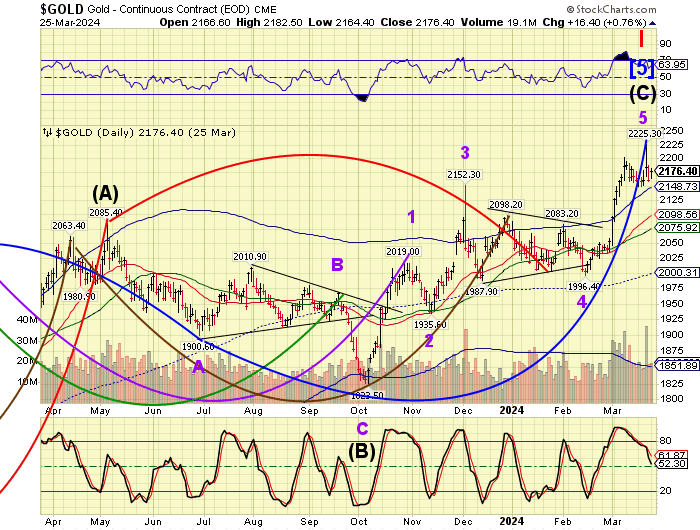
Gold futures are consolidating between 2168.00 ans 2200.00 after making a spike high on March 21.  That high may be the limit for the rest of this year and possibly longer, since the last 25 years of rally are due to be retraced, at least in part.  Initial estimates of the decline suggest the first possible support may come in near 1800.00.


Posted in Published | Comments Off on March 26, 2024