July 14, 2023

10:10 am

BKX, our liquidity proxy, made a new retracement high at the open, then reversed lower.  JPM’s glowing report comes at a cost to other banks’ solvency.  The Banking crisis may be about to resume.

ZeroHedge remarks, “Q2 earnings season officially started just before 7am ET when JPM reported earnings which, as expected, trounced expectations primarily on the back of generous contributions from the First Republican FDIC/taxpayer bailout-cum-gift, which has helped push the bank’s net interest income that much closer to a mindblowing $100 billion.”


8:40 am.  Bastille Day

Good Morning!  I spent a little extra time in analysis this morning.  I hope you appreciate it.

NDX futures spent the night beneath yesterday’s high at 15602.74.  It qualifies as an extended Master cycle high at day 273.  While there is no definitive reversal, the Cycle formation may be complete.

Today’s op-ex shows Maximum Pain for investors at 15530.00.  Long gamma starts at 15550.00 while short gamma begins at 15500.00.  Options investors have been front-running a very large playerthat may have withdrawn from the game.

ZeroHedge remarks, “NASDAQ – perfection continues

The perfect trend channel that has been in place since March lows stays very much intact. This time around we touched the 21 day and decided to bounce (without even testing the lower part of the channel). Note how far down the 50 day is…”


That player is the Bank of Japan.  Since early January, the Yen has declined 12% to the USD.  As a result, that change in the FX market has magnified the gains of all stock investments in the US, but especially in the NDX.  Since early this year, the NDX has appreciated by 56.5% in Yen.  The Bank of Japan is notorious for owning stocks, something that the Fed would not do publicly.  That Cycle may now be over, as this combination is now testing the Cycle Top at 212.65.  A cross beneath it implies a change in trend.  The “perfect investment” may have lost ist largest supporter.


SPX futures ventured marginally higher, to 4519.80 this morning, but may have lost momentum.  As mentioned earlier, yesterday was day 273 in the Master Cycle.  A new Master Cycle may have arrived.  With it may come a five-fold increase in strength and volatility.  I hope you are ready.

Today’s op-ex shows Max Pain at 4465.00  Long gamma starts at 4475, while short gamma may begin at 4450.00.

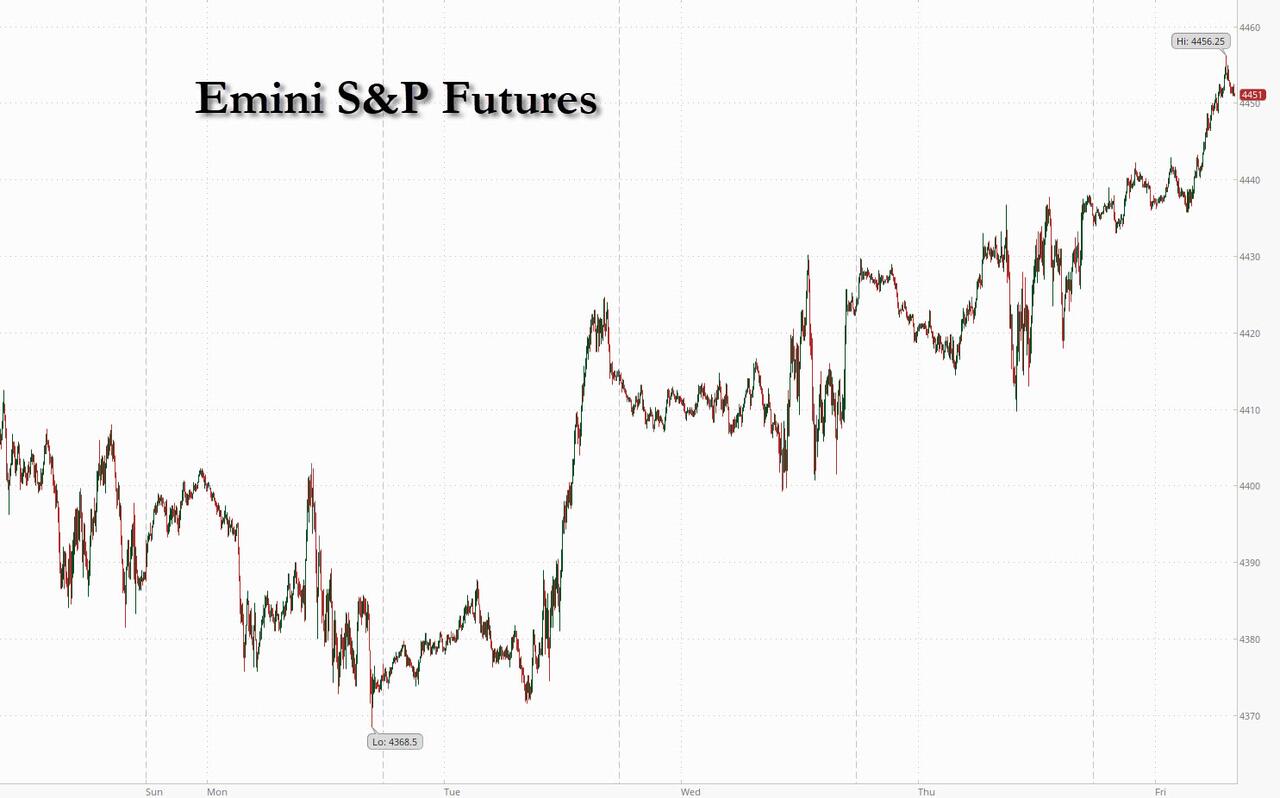
ZeroHedge reports, “The week’s powerful rally which sent US stocks to a new 52-week high has faded, with futs down small after a quiet overnight session on the day JPM officially ushers in Q2 earnings season as the post-CPI market rally pauses for breath as investors contemplate how recent US inflation data will impact upcoming Fed policy decisions. As of 6:45am ET S&P futures are flat at 4,542 while Nasdaq futures are down 0.1%. Bond yields are 3-5bp higher, and the USD has reversed higher after dropping the lowest level in more than a year. Commodities are mixed with energy lagging and base metals such as iron ore extending gains from yesterday. Yesterday’s dovish PPI and lower-than-expected initial claims supports the soft-landing narrative. Key focus today will be banks earnings; JPM, C and WFC report pre-market. Keep an eye on banks’ commentary on consumer health, credit trends and loan growth. We will also get the latest UMichsentiment data (consensus sees 65.5 vs. 64.4 prior); 1yr inflation expectation is estimated to fell to its lowest in two years”


VIX futures are on the rise, although not yetrising above the 50-day Moving Average at 15.62.  Recall that VIX has challenged the 50-day and pulled back.  This is a place to accumulate shares.


TNX has declined beneath the Intermediate-term support at 37.92, giving it a sell signal.  The Cycles Model suggests that TNX may continue its decline to the first week of August.  The likely target may be the Cycle Bottom at 32.59.

ZeroHedge remarks, “There was a shocking number in today’s latest monthly US Budget Deficit report. No, it wasn’t that US government outlays unexpectedly soared 15% to $646 billion in June, up almost $100 billion from a year ago…
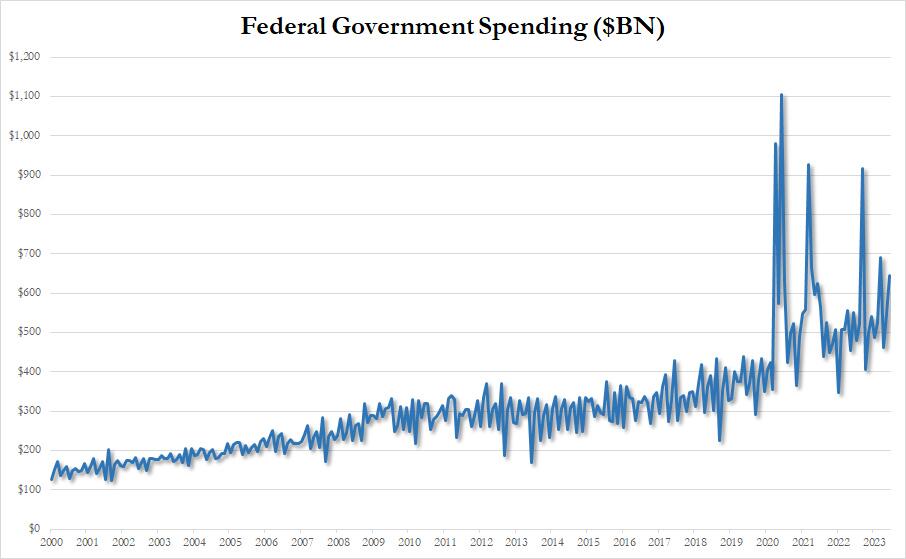
… while tax receipts slumped 9.2% from $461 billion to $418 billion, resulting in a TTM government receipt drop of over 7.3%, the biggest since June 2020 when the US was reeling from the covid lockdown recession; in fact never have before tax receipts suffered such a big drop without the US entering a recession.”


USD futures have bounced to test the trendline near 100.00.  It is currently in a throw-under of an Ending Diagonal formation, which may last a couple of weeks.  During that time, USD may decline to its Cycle Bottom at 98.32.  Calls for the demise of the USD may become more shrill, but this decline is merely a retracement of the 2021-2022 rally from 89.51 to 114.75 and not a change in trend.

ZeroHedge comments, “The prevailing downwards trend in the dollar is primed to remain intact while the real yield curve flattens.

FX is one of the hardest markets to get consistently right. Traders often employ a lot of leverage so there is little room for error, or for indiscipline with stops or sizing. But sometimes getting the bigger trends is not as frustratingly hard.

One of the best leading indicators for the dollar, for instance, is the real yield curve. The intuition is the dollar is driven at the margin by the real return of foreign investors into US yields.”


Posted in Published | 2 Comments

July 13, 2023

3:31pm

SPX may be nearing completion of its final probe in this series at 4 degrees of trend.  Should it be so, the reversal may come overnight.  Looking at this as the end of a trend, we are in day 272, which barely leaves another day to go.  At the minimum, consider taking long profits. An aggressive short may be taken beneath the two-month trendline at 4450.00.  Earnings season will start tomorrow and analysts are unfazed.

ZeroHedge remarks, “On Friday, Q2 earnings season kicks off when JPM reports just before 7am followed by WFC, and C, while MegaCap tech reports earnings in two weeks (Jul 26). 82% of S&P 500 firms (80% of market cap) will have reported by August 7th, and the bulk of reporting takes place during the week of July 24, when 48% of S&P reports.”

ZeroHedge further observes, “As discussed in our CPI preview, Wall Street expectations were for a soft CPI. The final number ended up being a dovish bomb with a rounded-up 2-handle, sending the dollar tumbling and stocks soaring to respective 52 week lows/highs.

Wall Street, which has been extremely bearish for most of 2023, pretended as if it hadn’t been dead wrong for the duration of the post-October bull market, and spun the CPI data as the all-clear for continued gains.”


12:03 pm

The Ag Index may have hit its Master Cycle low today, on day 253.  It did not venture to its 61.8% retracement at 387.76.  However, the pattern appears complete, or nearly so.  It may be time to accumulate shares of Ag businesses.


10:20 am

BKX may have completed its Master Cycle at day 272 yesterday.  It completed a 32% retracement of its February-to-May decline.  The banking crisis maybe about to resume.  The key is that the banks’ earnings season starts tomorrow.


8:15 am

Good Morning!

NDX futures rose to 15429.80 this morning.  The next resistance is at 15500.00 as it remains above the Cycle Top at   15123.80.  This is a rare phenomenon, as the Cycle Top is usually the final resistance in a Wave 5.  It shows ample liquidity for stocks in a market that is known for its illiquidity.  The question is, Where is the liquidity coming from?  Today is day 252 in the latest Master Cycle, so this matter may be resolved in the next week.

Today’s op-ex shows Maximum Pain for options investors at 15330.00.  Long gamma begins at 15350.00, while short gamma starts at 15300.00.  The domestic (daytime) market is clearly driven by long gamma, which may be the origin of the aforesaid liquidity.

RealInvestmentAdvice observes, “A recent whitepaper by the Federal Reserve warns of “significantly lower profit growth and stock returns in the future.” In his article, End of an Era: The coming long-run slowdown in corporate profit growth and stock returns, Michael Smolyansky explains how the interest rate and corporate tax rate trends for the last thirty years provided a strong tailwind for corporate profits. As a result, stocks performed better than would have otherwise been the case.

Understanding why corporate profits and, ultimately, stock prices outperformed in the past is important. However, more critical for investors is the future and assessing how interest rates and tax rates will affect earnings growth and stock prices.”


SPX futures rose to a morning high at 4491.80, on its way to 4500.00.  It continues to use its Cycle Top at 4415.12 as support.  Again, a highly unusual circumstance at this late in the rally.  As mentioned earlier, today is day 252 in the current Master Cycle.  That leaves the market a possible week to rally further.  However, the formation may lead to a sudden collapse, catching many investors unawares.  An aggressive sell signal may be invoked beneath the Cycle Top at 4415.12.

Today’s op-ex shows Max Pain for options investors at 4475.00.  Long gamma begins at 4495.00 while short gamma starts at 4450.00.

ZeroHedge reports, “For the second day in a row, US equity futures are higher as part of a global risk-on move one which has sent spoos to fresh 52 weeks highs, and fast approaching the Jan 2022 all time high. Tech is again outperforming led by the “magnificent 7″ megacaps following the unexpectedly soft CPI print which sparked expectations that after the July hike the Fed is done, and has accelerated the dollar tumble. As of 7:45am ET, S&P futures were 0.3% higher to 4,522 while Nasdaq futures rose 0.6%. Bond yields and the USD continue their move lower, with steepening in the belly of the curve. The DXY has made a 52-wk low today. The plunge in the dollar means that commodities are bid with strength across all 3 segments; keep an eye on Ags as India may move to restrict rice exports and the Black Sea Grain Initiative expires next week. Today’s macro data focus is on PPI, which will boost confidence that yesterday’s CPI print was not a fluke. Keep an eye on PPI in the future as China’s negative PPI and the lack of money supply growth may put accelerating downward pressure on input costs. Bank earnings kick off tomorrow.”


VIX futures made a new retracement low at 13.29 this morning.  While VIX may go down to, but not below, the June 22 low, the reversal may be imminent.

Wednesday’s op-ex shows the strike at 17.00 to be hotly contested and the locus for Max Pain.  Short gamma starts at 16.00 and is strong to 13.00.  Long gamma begins at 20.00 and appears strongly held to 60.00.


I have endeavored to find the source of liquidity for our supposedly illiquid equities market.  It appears that the SPX, measures in Japanese Yen, rallied nearly 30% since the March low banking crisis, nealry matching the 32% rally in the NDX.  We know that the Fed injected $300 billion into the banking system, but that was used to band-aid over their own solvency issues.  Banks have raised their lending rates and tightened their credit requirements since then, so it was not the banks that gave the stock market the extra juice.

Instead, it may have been the Bank of Japan, which has been known to buy equities at the drop of a hat.  The Bank of Japan now owns approximately 80% of all the stock ETFs issued in Japan and is a major player in all the Japanese indices.  It should not surprise us to know that the Bank of Japan may have been been the “big player” in the most recent rallies in the SPX and NDX.


USD futures are challenging the lower trendline at 99.65 this morning.  Should it hold, we may see a reversal by the weekend.


TNX is testing its trendline at 37.95 this morning.  It may bounce today, but subsequently decline beneath the trendline to the 50-day Moving Average at 36.98.  The Cycles Model suggests that this correction may last to the end of the month, so the likelihood of a lower correction is high.

ZeroHedge remarks, “In a recent podcast, Peter Schiff warned that we could be on the verge of a further breakdown in the bond market and that a bear market in bonds could also maul US stocks and the dollar.

Financial commentator and investment guru Jim Grant has similar concerns. In a recent interview on Odd Lots Podcast, Grant said he thinks we’re at the beginning of a long-term trend of a weak bond market with higher interest rates that could last decades.”


Posted in Published | Comments Off on July 13, 2023

July 12, 2023

8:00 am

Good Morning!

NDX futures have risen to 15176.40 this morning, riding above the Cycle Top support at 15078.82.  The Cycle Top is 2 standard deviations from the mid-Cycle support at 12560.06.  After two months above the Cycle Top, a reversion to the mean may also suggest a decline well below the mid-Cycle value.  The Cycles Model suggests the current Cycle interval may last until monthly options expiration on July 21.  Thus far it is directionless.

Today’s op-ex shows 15120.00 being hotly contested.  Long gamma starts at 15150.00.   Short gamma begins at 15000.00.

RealInvestmentAdvice comments, “Does stock risk decline the longer the holding period is? It’s a great question and something I received a comment about.

Blaise Pascal, a brilliant 17th-century mathematician, famously argued that if God exists, belief would lead to infinite joy in heaven, while disbelief would lead to infinite damnation in hell. But, if God doesn’t exist, belief would have a finite cost, and disbelief would only have, at best a finite benefit.

Pascal concluded that given that we can never prove whether or not God exists, it’s probably wiser to assume he exists because infinite damnation is much worse than a finite cost.

When it comes to investing, Pascal’s argument applies as well. ”


SPX futures rose to 4452.00, testing the June 30 high at 4458.48.  However, the CPI is due at 8:30 and may either boost SPX to a higher peak or take the steam out of the rally.  The Cycles Model suggests the current Cyclical interval may last until monthly options expiration.

8:35 am

SPX futures have reached a new high at 4475.40.  The CPI was up .2% for the month of June.

Today’s op-ex shows Max Pain at 4415.00.  Long gamma starts at 4425.00 while short gamma begins at 4400.00.

ZeroHedge reports, “US equity futures are trading near session highs boosted by a global risk-on mood ahead of a US CPI report for the month of June which JPM said is “more likely to print dovish than hawkish” and is expected to show annual US headline inflation falling almost 1% to 3.1% Y/Y while core CPI is seen dipping less, to 5.0% YoY, which according to the market will erode the case for more rate hikes. Dovish sentiment pushed the dollar lower for a 4th straight day, sending the Bloomberg dollar index to the lowest since April, while also depressing Treasury yields.

As of 7:30am, following Monday’s solid gains, S&P futures traded higher 0.3% to 4,485 led by small-caps as bond yields and the USD move lower. Nasdaq 100 futures also rose 0.3%. Commodities are higher while gold, oil, and iron ore prices all higher amid increasing calls for fiscal stimulus from China; ags are also higher driven by next week’s expiration of the Black Sea Grain Initiative.”


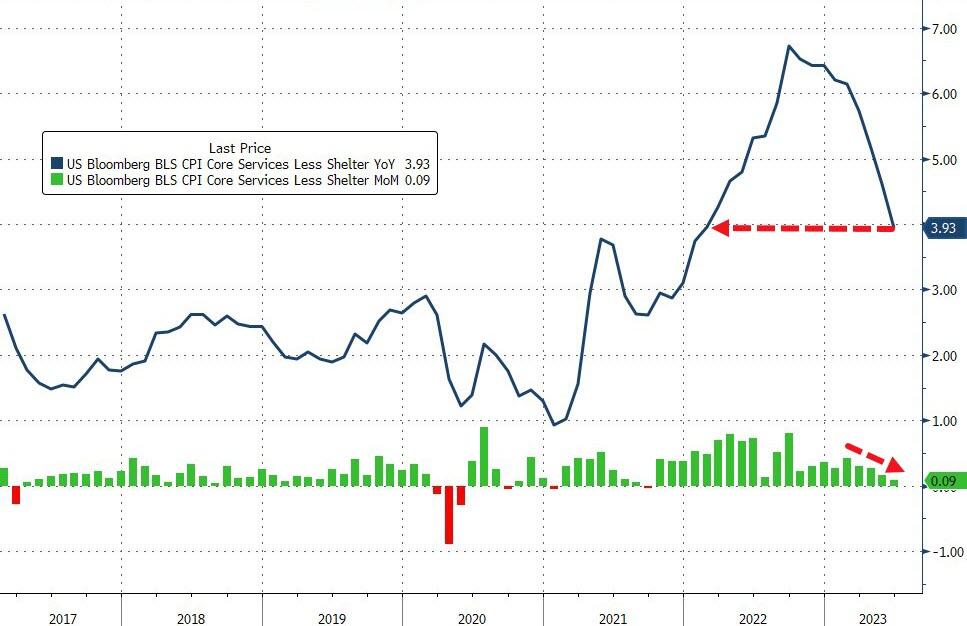
ZeroHedge reports, “Expectations for this morning’s headline CPI print were for a plunge from 4.0% YoY to 3.1% YoY (due to shelter, used-cars, and seasonals); however, what The Fed will be watching for is Core Services CPI Ex-Shelter, which fell to +3.93% YoY – the lowest since Jan 2022…

Source: Bloomberg

The headline CPI rose just 0.2% MoM (below the 0.3% MoM expected) which dragged the headline down to +3.0% YoY (cooler than expected) – the lowest since March 2021..”


VIX futures plunged to 14.03 this morning on the CPI report.

Today’s op-ex shows Max Pain at 13.50.  There is no short gamma.  Long gamma begins at 16.00.  Next week’s monthly op-ex shows Max Pain rising to 17.00.  Short gamma makes a comeback beneath 16..00 while long gamma takes a strong position at 20.00 to 35.00.


TNX futures declined to 38.85 this morning.  The correction in TNX may last to the end of the month.

ZeroHedge reports, “If there were some concerns that the week’s first coupon auction would be a disappointment due to today’s risk-on sentiment and lack of concessions into the 1pm auction block, they were promptly blown away moments ago when the Treasury announced results from today’s sale of $40BN in three year paper, which were nothing short of stellar.

Stopping at a high yield of 4.534%, this was more than 30bps higher than last month’s 4.202% and not far below the current cycle high of 4.641% reached in March (just before yields collapsed following the March banking crisis). The auction also stopped through the When Issued 4.536% by 0.2bps, the 4th stop through in the past five auctions (last month the auction tailed by 0.2bps).

The Bid to Cover jumped to 2.882 from 2.696, and was also above the 6-auction average of 2.686.”


Posted in Published | 1 Comment

July 11, 2023

10:35 am

The Ag Index is testing its lower trendline prior to a final plunge to its 61.8% retracement low at 387.76 or, its Wave (4) technical support at 380.54.  The Cycles Model suggests this may take place in the next week or so.  While this has been a steep decline, it has been a seasonal feature for this time of year for the past three years, due to the start of the harvest season.  The lower prices at the field have not trickled down to the consumer.

ZeroHedge reports, “Despite the Biden administration’s cheerleading that ‘Bidenomics’ is the economic savior of the middle class — most Americans will disagree there has been an economic revival amid the worst inflation storm in a generation that has sent negative real wage growth negative for more than two years, forcing consumers to deplete personal savings and rack up record amounts of credit card debt in a high-interest rate environment.

We have shown many households are in rough financial shape. Dollar Tree executives confirmed weeks ago that mid/low-tier consumers are trading down from other more expensive retailers to their stores for groceries. This means Walmart has become too expensive for some consumers. ”


10:15 am

BKX is attempting to make a new retracement high and extend the Master Cycle above the July 3 high at 82.12.  It must do so immediately in order to succeed, as today is day 271 in the (former) Master cycle.  The probability is slim, but must be allowed under these circumstances.  Once BKX declines back down beneath Intermediate-term support at 79.92, then all bets for an extended rally are off.

ZeroHedge comments, “Last month, when both revolving credit (i.e., credit card debt) and interest charged on credit cards hit a record high, we said that this trajectory was unsustainable and it was only a matter of time before the debt-funded US consumer hit a brick wall. One month later, the brick wall is finally here, because according to the Fed’s just released consumer credit report, in May US consumer credit grew by a paltry $7.24BN, down more than 50% from the downward revised $20.3BN in April…

…. and a huge miss to the consensus forecast of $20 billion. In fact, this was the 4th miss in the past 6 months.”

ZeroHedge now states, “After a ‘holistic review’ of capital for large banks “to enhance their resilience and ability to serve communities, households, and businesses,” Fed Vice-Chair of Supervision, Michael Barr said in a report this morning that he’s leading a multi-year effort to increase capital requirements for banks.

Barr managed expectations by explaining that the focus of the review was on building resilience rather than attempting to address every conceivable risk, as the financial system is complex and constantly evolving.

“The proposed rules would end the practice of relying on banks’ own individual estimates of their own risk and instead use a more transparent and consistent approach,” he said.”


8:00 am

Good Morning!

NDX futures are backing away from an overnight high at 15095.00 this morning.  It is challenging its Cycle Top resistance at 15040.00.  Should it go higher, the next probable resistance is at 15210.00.  The next period of strength hovers around monthly options expiration on July 21.  The current Master Cycle also ends there and it isn’t giving any indication of direction.  Today’s action may give resolution to that issue.

Today’s op-ex shows 15050.00 (Max Pain for investors) hotly contested.  Long gamma begins at 15075.00 while short gamma at 15000.00.  The monthly op-ex shows Max Pain drifting down to 15000.00 with massive call interest at 15100.00 and above.  There is currently little short interest on that expiration.

ZeroHedge observes, “In a day when the S&P rose and non-profitable (small cap) tech companies soared yet megacap tech companies sank (partially answering the question we posed last week)…

… Goldman trader Mike Washington writes that there was a lot of client focus on the Nasdaq 100 special rebalance which was announced late last week on the back the “magnificent seven” dominance, and which plans to address overconcentration in the index by redistributing the weights (no adds/deletes) on Friday (7/21) after the close, effective prior to open Monday, July 24th.”


SPX futures are trading in a range from 4404.00 to 4421.00.  The Cycle Top is at 4407.00 with an aggressive sell signal beneath it.  The next FOMC meeting is on July 25-26, shortly after the monthly op-ex on July 21.  There is a high probability of a flat market until the op-ex as SPX hovers near its Cycle Top.

Today’s op-ex shows Max Pain for investors near 4400.00.  Long gamma starts at 4425.00 while short gamma may begin at 4370.00.

ZeroHedge reports, “For the second day in a row, S&P futures are largely unchanged following a muted overnight session, reversing an earlier loss around the start of the European session and trading around session highs. In a reversal of yesterday’s tech/small cap drubbing sparked by fears about the upcoming Nasdaq special rebalance (see here). As of 7:30am, S&P futures were up 0.2%, trading at 4,450, and building on Monday’s modest gains with sentiment boosted after China signaled that more economic aid measures will come to support its ailing property market along with measures to boost business confidence; Nasdaq futures were also in the green as tech stocks see a lift while bond yields fall ahead of growing expectation that tomorrow’s CPI will surprise dovishly (in large part on the back of yesterday’s Manheim used car index collapse).”


VIX futures drifter lower, to 14.87 this morning.  Support may be found at Friday’s low of 14.33.  Unlike the SPX, which anticipates an ending Master Cycle on or around July 21, the VIX is merely showing a period of strength.  One may infer a possible new low in the SPX, while the VIX forges higher.

Wednesday’s op-ex shows a grey area between 14.00-15.00, possible the Max Pain area.  Short gamma is practically non-existent, while long gamma may occupy the area from 16.00 to 33.00.  On the other hand, the Monthly op-ex on July 19 shows Max Pain at 17.00 with massive short gamma below that level and massive long gamma above that level to 35.00.  It promises to be a volatile op-ex week.


TNX has dropped beneath 40.00 as it retraces the previous Cycle high.  The breakout is real, but typically a three-week retracement/consolidation follows.  The Cycles Model suggests TNX may go lower until the first week of August.  Presently, the trendline or possibly the 50-day Moving Average at 36.96 may be the target for the pullback.  However, it would not be beyond the range of possibility tha the Cycle Bottom at 32.56 may be the ultimate target.

ZeroHedge remarks, “Fixed-income traders may be considerably underestimating how long price pressures will persist in the developed economies.

The breakeven curve in the US has gone from being inverted six months ago to pretty flat now. The change in the slope of the line isn’t as much a surprise as is the level of the points on the curvature: to the extent a central bank tightens policy and restores market confidence that it is acting decisively on inflation, the curve would “normalize”.

ZeroHedge explains, “It is rare to have an indicator that works every single time; this is one of those rare instances.

That is the warning from Bank of America’s HY Credit team as rates surged back into play in a big way last week.

Specifically, the 10yr UST back over 4% for the first time since Feb; the 2yr touched on 5.12% – the highest level since June 2007. In the UK, the 10yr has breached 4.64% level – the peak achieved during the LDI crisis last Oct.

The rate risk is back as the front and center driver of volatility in credit… and as goes credit, so goes the rest of the market.

BofA’s core view here remains that the full extent of damage from tight monetary policy is unknown until the peak in policy tightening is behind us.

We are clearly not at that point yet.”


Posted in Published | Comments Off on July 11, 2023

July 10, 2023

9:00 am

Good Morning!

SPX futures are flat this morning, trading beneath its Cycle Top resistance at 4404.2.  It remains on an aggressive sell signal on day 270 of the Master Cycle.  The high at 4458.48 was made on June 30, day 260 and is likely to be recorded as such.  The next Master Cycle is due in a bout 10 days.  The next level of support is at the Intermediate-term at 4310.00, while the final support is the 50-day Moving Average at 4245.21.  Beneath that is a confirmed sell signal.

Today’s op-ex shows Maximum Pain at 4410.00.  Long gamma may start at 4425.00 while short gamma may start at 4375.00.

ZeroHedge reports, “After Friday’s downbeat market close, futures are again weaker to start the weak, if off the worst levels of the day, as we enter a heavy macro week highlighted by CPI, 8 Fed speakers, and the kick off of earnings season. Risk appetite also took a hit as focus turned to the threat of deflation in China: June CPI was flat – on the verge of deflation – while producer prices slumped 5.4% from a year earlier, the sharpest slide since December 2015.

As of 7:30am ET, S&P futures were down fractinally, erasing an earlier loss of 0.5%, with Nasdaq 100 futures lagging and down 0.2%. Bond yields are lower, the USD flat also erasing an earlier drop amid broad commodity weakness (as a reminder, the Black Sea Grain Initiative expires next week; keep an eye on Ags prices). Yellen’s China trip attempted to thaw US/China relations and while dialogue remains open there are no actionable plans for further step.”


VIX futures are challenging the 50-day Moving Average at 15.83, having reached a morning high at 16.21. VIX has made a confirmed buy signal and should be accumulated on any pullback.  The next Master Cycle is due near mid-August, but may be extended to the end of August.


TNX futures made a morning high at 40.92, leaving Friday’s high at 40.94 as the potential Master Cycle high on day 259.  Should that high remain, the new Master Cycle may last through the end of July with a potential target at the trendline and Intermediate-term support at 37.77.  Contrary to popular opinion, there may be a nother rate hike in August.

ZeroHedge remarks, “10-year US Treasury yields eclipsed 4% this past week for the second time this year and the third time since 2008. The most recent move began in mid-May from a level 70bp lower than current market yields. The yield on 2-year US Treasury notes rose more than 100bp during the same period – sending the 2s10s yield curve back to its most inverted levels of the hiking cycle.

Despite these large moves, US Treasury yields rose less since mid-May than the yields on UK, Canadian, and Australian government bonds. UK gilt yields were up the most since mid-May, with 10-year yields higher by almost 100bp and 2-year yields by 175bp. What common denominator could explain these moves? The repricing of market-implied central bank policy paths.”


USD futures are higher this morning, consistent with the current Master Cycle, due for a potential high in mid-August.  USD may see Trending Strength carry it along through the end of July.


Posted in Published | Comments Off on July 10, 2023

July 7, 2023

8:00 am

Good Morning!

US Tech futures hovered just above 15000.00 this morning as they await the monthly Employment Situation Summary due at 8:30 am.  The NDX tested the Cycle Top support at 14963.00, but did not decline beneath it.  An aggressive sell signal awaits the decline crossing the Cycle Top.  The next level of support is the Intermediate level at 14578.57 and the Ending Diagonal trendline jsut beneath it.

Today’s op-ex shows Max Pain at 15050.00.  Long gamma begins at 15150.00.  Short gamma may begin beneath 15000.00.

ZeroHedge comments, “Unprofitable tech and rates

We have seen a lot of commentary that big tech is immune to surging rates. You decide if you buy that argument, but what about unprofitable tech? There has been a lot of buying, mainly short covering, in unprofitable tech since May according to GS. The great chart needs little commenting…

Source: GS/Bloomberg

Surging rates is a problem

You do not compare trending assets to mean reverting assets, but the US 10 year vs VIX chart shows that surging rates is a problem for equities, despite the fact so many people tell you other stories.


SPX futures are hovering just above the Cycle Top support at 4401.54 after challenging that level yesterday.  thus far, the Cycle Top is at the June 30 high at 4458.48 on day 260 of the Master Cycle.  The Department of Labor’s monthly jobs report is due momentarily.

Today’s op-ex shows Max Pain at 4410.00.  Long gamma starts at 4450.00 while short gamma begins at 4400.00.

ZeroHedge reports, “Stocks were subdued as investors prepared for the June jobs report to gauge if they will confirm the blowout ADP print and back new bets for more Fed interest rate hikes which sent yields soaring on Thursday, slamming risk assets. US equity futures reversed earlier losses and traded unchanged after Thursday’s losses in the S&P 500 and Nasdaq 100 benchmarks sparked by stronger-than-expected ADP private payrolls data. As of 6:30am, emini S&P futures were down 0.1% while Nasdaq 100 futs dropped 0.2%. European stocks erased earlier declines of as much as 0.5% to trade flat, but were still on course for their worst week since the middle of March. MSCI Asia Pacific Index declined 1.6% to the lowest since June 2, as strong hiring data in the US renewed monetary tightening worries and investors awaited major stimulus measures from China. Treasury yields extended their ascent, with the 2Y rising back over 5.00% after nearly hitting 5.10% on Thursday while 10Y yields traded around 4.06%, after yesterday’s jobs data sent a gauge of global bond yields soaring to the highest since 2008.”


VIX futures are hovering near the 50-day MOving Average after having broken through it yesterday.  It is on a buy signal and pullbacks may be used to add longs or reduce short exposure.  The Cycles MOdel infers an uptrend through mid-August, with rising volatility.

Wednesday’s  op-ex shows Max pain at 16.00.  Short gamma is still strong, while long gamma appears weak.


TNX is hovering near its high made yesterday.  Today is day 259 of the current Master Cycle and may be the final high of this Cycle.

9:15 am

The anticipated breakout has occurred this morning.  The high thus far is 40.94, overcoming the February high at 40.91.  The Cycle Top at 41.34 awaits a possible test before a short-term reversal.

ZeroHedge comments, “BS break down

Fed’s BS printed another new recent low. The SBV “juice” is all gone. Note we haven’t “printed” these levels since Q3 2021.

Source: Refinitiv

Why bond yields are up

Liquidity drain over the past 2 weeks driving the bond move. Note another $1tn drain is expected in the upcoming couple of months.


USD futures are pulling back, challenging the 50-day Moving Average at 102.56.  The Cycles Model suggests the uptrend may continue through mid-August.


Posted in Published | Comments Off on July 7, 2023

July 6, 2023

11:56 am

VIX has given us an unambiguous buy signal as it rallied above the 50-day Moving Average at 15.94.  Trending strength has finally arrived and may help propel the VIX higher over the next tow months.


11:46 am

SPX may have issued its first aggressive sell signal by crossing the lower trendline of its most recent 2-month rally.   It has bounced from short-term support at 4382.94 and may retest the trendline.  The Cycles Model calls for two more weeks of decline with a potential target at the 2-hour Cycle Bottom at 4090.10.


11:29 am

BKX has declined through its Intermediate-term support at 79.64 and its 50-day Moving Average at 78.88, creating a confirmed sell signal.  Liquidity is draining out of our economy.  One absolute way to make liquidity disappear is through bankruptcies.  Liquidity increases through the issuance of debt.  However, bankruptcies and insolvencies have the opposite effect and may cause the economy to contract.

July 3 (Reuters) – U.S. Chapter 11 bankruptcy filings jumped 68% in the first half of 2023 from a year earlier, Epiq Bankruptcy, a provider of U.S. bankruptcy filing data, said on Monday.

SVB Financial Group, Envision Healthcare Corp, Bed Bath & Beyond, Party City Holdco, Lordstown Motors and Kidde-Fenwal were among some casualties of decades-high interest rates and sticky inflation as the era of easy money drew to a close.

ZeroHedge inquires, “The Federal Reserve has hiked interest rates to levels not seen since before the financial crisis in 2008. The money supply had contracted at a rapid rate. This should cause the economy to slow down. Yet month after month, we get strong job numbers, rosy economic headlines, and assurances that the economy remains robust.

What exactly is going on here? Why hasn’t the predicted recession materialized yet?


8:15 am

Good Morning!

NDX futures are sliding lower from their double top to a low of 15104.00.  The Cycle Top support is at 14920.78.  Beneath that may be an aggressive sell signal.  Most articles on tech are retrospective, as if by looking backwards you will know where you are going.

Today’s op-ex shows Max Pain at 15225.00.  Long gamma may start at 15300.00 while short gamma may begin at 15200.00.

ZeroHedge notes, “Highest since the SBV collapse

The US 10 year is trading at 3.92% as of writing. A level last seen when SBV hit the world. Note the 50 day crossing the 100 day moving average here. Previous big crosses saw yields move sharply higher…

Source: Refinitiv

Pushing it

Will they push tech to a new all time high as a share of sector fund assets? Big tech has decoupled from rates. GS writes: “Tech has had a tremendous rally despite higher rates, so on a scenario of lower rates I think this cohort has another leg higher”.


SPX futures have declined to a morning low of 4405.40 thus far, soon to reach or power through the Cycle Top support at 4397.62.  An aggressive sell signal may await beneath that level.  The Cycles Model shows a potential low during options week, where trending strength may increase.

Today’s op-ex shows Max Pain at 4440.00.  Long gamma may begin at 4455.00 while short gamma starts at 4425.00.

ZeroHedge reports, “US futures extended losses as markets finally noticed the recent surge in Treasury yields across the globe, sparking fears of stagflation and following recent remarks from the Federal Reserve that were more hawkish than anticipated. Sentiment was also cautious ahead of fresh employment data. Stocks have struggled as a result, with the Stoxx 600 down 1.2% and on course for its largest fall in six weeks. As of 8:00am, ET, S&P 500 and Nasdaq 100 futures lose 0.6%. Treasury yields rose across the curve, adding to gains on Wednesday spurred by the Fed minutes. The policy sensitive two-year rate inched up to 4.96%. The dollar initially dropped but then spiked after a blow out ADP report.”


VIX futures have risen to a morning high at 15.63, breaking out above a previous high at 14.93 and approaching the 50-day Moving Average at 15.94.  An Aggressive buy signal may be made at either level.  Trending strength has kicked in and may last the rest of this week.

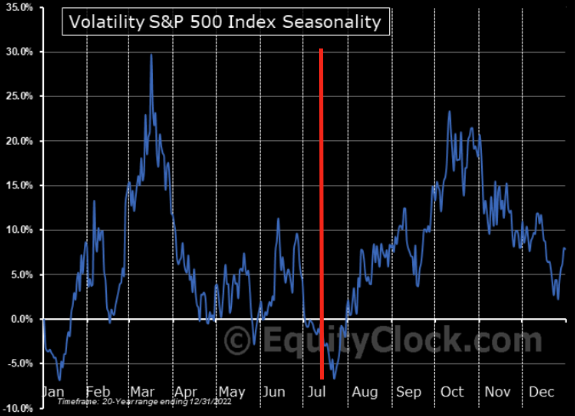
ZeroHedge remarks, “VIX seasonality

Use the summer vacations wisely…

Source: Equity Clock

Some fear has moved sharply higher

European “VIX”, the V2X, has moved sharply to the upside. The index has not closed here since early June. The gap vs VIX is very wide.”


TNX surges higher this morning, nearly taking out the March high at 40.91 and possibly aiming for the Cycle Top resistance at 41.31.  As you can see, the Master Cycle is nearing its end and may be over by the end of the week.  While TNX is due for a pullback, the message may be clear.  Higher rates are on their way.

ZeroHedge remarks, “The effects of Fed rate rises will be increasingly amplified as households’ duration risk rises, strengthening the hand of those in the FOMC who would prefer a “wait-and-see” approach to further tightening.

Five hundred basis points of rate rises in a little over a year would normally be expected to cause some damage. While there have been a few casualties along the way, and growth has taken a hit, it’s remarkable how resilient the economy has been.

Yet this rate-hiking cycle has been different from others in that the Fed has had a large amount, over $5 trillion, of the market’s duration risk sitting on its balance sheet, shielding the economy from the worst of the effects of rate rises.”


Posted in Published | Comments Off on July 6, 2023

July 5, 2023

12:20 pm

The rally in the BKX appears to have fizzled on June 13 as the knock-on effect appears to be the narrowing of leadership in all the other indices.  The NDX and SPX only have 5 companies on which they can base their rally.  Liquidity may be about to take another nosedive as the Cycles Model points down for the next two months.   To make matters worse, the Fed releases the minutes to the June 14 meeting.

ZeroHedge observes, “A rise in bankruptcy filings points to increasing bankruptcies, loan charge-off rates and delinquencies, suggesting credit spreads are not reflective of the underlying credit backdrop.

A chart of bankruptcy filings (using weekly data from Bloomberg’s BCY function) and credit spreads I used in last Thursday’s MacroScope column generated a lot of reader interest. This chart, below, shows that filings for bankruptcies have risen sharply despite credit spreads idling for most of this year. Previous rapid rises in filings have been preceded by a widening in credit spreads.”


7:45 am

Good Morning!

I am revisiting the DJIA this morning to highlight some important characteristics about Cycles.  First, there are Cycles at multiple units of measurement.  For example, the Master Cycle has an average duration of 258 days.  It may be considered the most basic Cycle.  However, Monthly Cycles also exist that may consist or multiples of the Master Cycle.  And, in some cases, may not coincide exactly with their brethren.  This may be a case in point, where we have a double top, two weeks apart.  Last Friday’s high was 260 days from the October 13 low, a typical Master Cycle.

The DJIA is being highlighted for another reason.  It’s retracement high was on December 13 at 34712.48.  It has not exceeded that high, even at this double top.  There may be a final attempt to go higher, but time is running out and, should it do so, it must be very soon.

This morning’s INDU futures have declined to 34228.00 thus far.   Should the INDU decline beneath the 50-day Moving Average at 33644.00, it will have created an aggressive sell signal.


NDX futures have declined to 15103.40 thus far this morning, leaving a double top.  Time may be running out for another attempt to probe higher.

The NDX gives us another example of a double top, where June 13 marked the top of an 18.5-month Cycle, coinciding with the 17.2-month Cycle in the Blue Chips.   Friday’s Master Cycle high also agrees with the Master Cycle high in the SPX.  Cycle Top support lies at 14871.48 where an aggressive sell signal awaits.

ZeroHedge notes, “It would be (almost) perfect

NASDAQ started front running the 1999 analogy a while ago. Is a pullback to be expected…followed by a furious melt up later this autumn? Nothing is impossible…

Source: Refinitiv

Tech’s rates dislocation

Big tech continues driving the main narrative, and rates seem to not matter for this mighty sector, despite the 10 year trading at highest levels in months. NASDAQ vs US 10 year inverted gap at very wide levels.


SPX futures have declined to 4429.40 thus far this morning, nearing its Cycle Top support at 4390.98.  Beneath that level an aggressive sell signal may be assumed.  Of all the major indices, the SPX alone has made a new retracement high as well as a double top.  Should SPX (or any of the other stock indices) go higher, time to make new retracement highs would be limited.

ZeroHedge reports, ” One day after a solid start to the new quarter, and after the US took a day off for Independence Day, sentiment has reversed for the worse and US equity futures and European stocks followed Asian shares lower, while bonds declined after the latest China services PMI print from China came well below expectations (53.9 VS 56.2 expected) and raised fresh concerns about the outlook for the global economy. At 7:45am ET, S&P 500 and Nasdaq 100 futures both fell more than 0.5%, indicating US stocks will open lower when trading resumes after the Independence Day holiday. The yield on 2Y Treasuries drifted about five basis points lower to 4.89%. The China-driven weakness was broad based with Japan’s NKY down -40bps, China’s Shcomp sliding -60bps and the HSI -1.5%. The Stoxx Europe 600 Index slid about 0.6% after soft euro-zone May PPI data, with miners leading the retreat on concern about waning minerals demand from China. Most commodities were lower with copper -70bps, oil -50bps and iron ore -40bps. The Bloomberg dollar index is higher, gold is climbing, and oil is also edging higher.”


VIX futures rose this morning to 14.74 before easing.  A potential breakout lies above 14.90, while the 50-day Moving Average is at 15.99.  Should the VIX go above the first level, it may create an aggressive buy signal.  Above the 50-day May create a confirmed but signal.  The extended tail of the Triangle formation may cause a slingshot effect above the long-term trendline at 18.00.  The Cycles Model suggests trending strength may have resumed with possible knock-on consequences.


TNX is challenging its breakout occurring last week.  Today is day 257 in the Master Cycle, suggesting the balance of this week may show higher rates.

ZeroHedge observes, “A note recently published by two Federal Reserve economists reveals a looming catastrophe…

The Fed’s interest rate hikes have already precipitated a financial crisis. The central bank managed to paper over that problem and get it out of the headlines with a bailout program. But it didn’t solve the problems. Banks continue to tap into the bailout loans as they struggle in this high-interest-rate environment.

And there are even bigger problems on the horizon.”


Posted in Published | Comments Off on July 5, 2023

June 30, 2023

10:30 am

The Banking Index may have reached another Master Cycle high this morning as it may have completed a 70% retracement of its decline from its June 14 high at 83.38.  The Cycles Model now suggests a 2-month decline that may fulfill the Head & Shoulders target despite Fed reassurances that banks have passed their stress tests. 

In fact, hedge funds have never been more bearish on banks, despite the Fed rassurances.   The Fed waited until the market close to announce that the emergency bank bailout facility usage hit a new record high.


8:00 am

Good Morning!

SPX futures rose this morning over it 61.8% Fibonacci retracement at 4401.00 after a 6-day decline and a 3-day rally (thus far).  Cyclically and technically the retracement may be over today, but pressures are on for a strong end-of-quarter.  After the 4-day holiday coming up, the emphasis may be on the downside.

In today’s op-ex, there is a huge collar put on SPX starting at 4320.00 with a heavy population of calls going to 4400.00.  It is likely that SPX may close today in the upper range of this collar.

ZeroHedge reports, “The second quarter – and first half – of 2023 is coming to a close on an upbeat note, as US equity futures are higher, led by megacap tech, and especially Apple, which is set to open with a market cap over $3 trillion following a bizarre initiation report from Citi yesterday late, which set a $240 price target on the world’s biggest company, just in time to catch its all time high. As of 7:45am ET, S&P futures were 0.4% higher, set to close out a third straight quarterly gain…

… while Nasdaq futures rose 0.5%, indicating the index is set to extend its 37% surge since the start of the year, its best start to the year since 1982.”


NDX futures just crossed above the 61.8% Fib retracement at 15056.00 this morning.  Quarter end dictates that id may stay at or above that level for the remainder of the day.  An aggressive sell signal lies beneath the Cycle Top support, currently at 14709.60.

In today’s op-ex Max Pain lies near 14950.00.  Long gamma lies above 15000.00, while short gamma lies beneath 14900.00.  Both long and short open interest falls off dramatically after the holiday.


VIX futures revisited but did not go lower than the June 22 low at 12.73 overnight.  The bearishness has been wrung out of the VIX.  A breakout above the June 26 high at 14.33 mayu  provide an aggressive buy signal.

the July 5 op-ex shows Max Pain at 17.00.  Short gamma begins at 16.00, while long gamma comes in at 17.00.

ZeroHedge inquires, “The VIX has continued its remarkable descent last week despite downward pressure on US equities, falling below 13 to as low as 12.73 intraday on June 22, its lowest levels since Jan-20, before recovering to 13.54.

And while investors – most of whom are still skeptical about the current rally – might be in different “stages of grief” about the equity vol crush, according to BofA’s derivatives gurus Nitin Saksena and Benjamin Bowler, they can all agree on the key questions: what’s driving it; when will the VIX base; and how low can it stay?”


TNX broke out above its May 26 high at 38.59 on day 252 of its current Master Cycle.  However, it has made an immediate reversal and may revisit Intermediate-term support at 37.14 or the mid-Cycle support at 38.93, prolonging the Master Cycle and positioning it at the low.  The jury is out for another week to determine the true intent of the Cycles Model.


USD futures declined to a morning low at 102.52, just above the 50-day Moving Average at 102.47.  The decline may not last since the Cycles Model shows (up) trending strength coming back next week.  In fact, the may rally considerably higher through mid-August.


Posted in Published | 11 Comments

June 23, 2023

9:30 am

BKX just plunged beneath the 50-day Moving Average at 79.15 and Intermediate-term support at 78.25 to confirm a sell signal.  Something may emerge in the Banking Sector that constricts liquidity.  The Head & Shoulder target is still valid.


9:20 am

Prepare for a gap down beneath 4350.00 in the SPX and an aggressive sell signal.


7:40 am

Good Morning!

PLEASE NOTE:  i will be out of town until Thursday.  Commentary may resume on Friday.

NDX futures are down this morning after making a 51% retracement.  The Cycle dynamics have changed, with 3 days down and only one day of retracement.  This compares to last year’s 2 to 1 ratio.  Keep that in mind as we launch a vicious decline that may last up to 4 weeks.  Short covering may be brutal, but the decline may be much worse.

In today’s op-ex, 14950.00 is hotly contested.  Long gamma may begin at 15000.00 while short gamma gains ascendancy beneath 14900.00.


SPX futures are testing Cycle Top support at 4356.00 this morning after a less-than-Fibonacci retracement of 32%.  There is an outside chance of a quick recovery to make a higher retracement, but once beneath 4350.00 the decline resumes under an aggressive sell signal.  The sell signal is confirmed beneath Intermediate-term support, currently at 4229.74

Today’s op-ex shows the strike at 4375 may be hotly contested Max Pain.  Long gamma begins at 4400.00 while short gamma takes over at 4350.00.

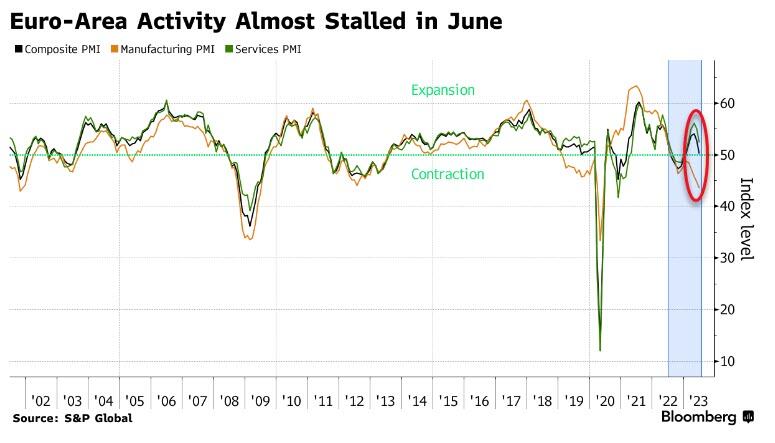
ZeroHedge reports, “One week after S&P futures hit a 52-week high, sentiment has turned increasingly ugly and US equities are set to open lower for the 4th of the past 5 days, with global stocks also sliding, after the latest set of dismal European PMIs revealed that economic momentum in the euro area almost came to a halt in June, signaling an end to the revival the bloc demonstrated since its winter downturn (and good news for the ECB which has been desperate to spark a recession). As of 7:45am ET, emini S&P futures were down 0.5%, trading just over 4,400, almost 100 points below the YTD highs hit last Friday; Nasdaq futures were also down half a percent, as investors fled into the safety of bonds amid a return of fears that weak euro-area activity data together with aggressive central bank rate hikes will tip economies into recession. The Bloomberg dollar index traded near the day’s highs, pressuring all Group-of-10 currencies. Treasury yields fell across the board, following pullbacks in the UK and Europe. Gold advanced, Brent crude slid more than 1.5% and Bitcoin fell for the first time in five days. Today’s macro data focus is PMIs releases: the street expects another contractionary print from the US Mfg PMI at 48.5, while services are expected to dip to at 54.0 from 54.9.”


VIX futures rose to 13.55 this morning after a likely bottom made yesterday on day 267.  While an 8.6-day extension is allowed in the Master Cycle, there is no explanation where the selling originates.   Was the VIX decline meant to curb the decline in stocks in a tail-wags-the-dog fashion?

A look at the VIX op-ex next Wednesday shows Max Pain at 13.50.  There is no short gamma, while long gamma takes of at 16.00.


TNX was beaten back to the mid-cycle support and trendline at 36.80 this morning.  It remains in a consolidation as it gathers strength for the next probe higher.  The target for the next two weeks appears to be the Cycle Top resistance at 41.22.


USD futures rose to an overnight high of 102.78, probing above the 50-day Moving Average at 102.26 and issuing a buy signal.  This action may launch a 2-month rally in the USD.  Analysts who are trash talking the USD fail to see the worsening conditions elsewhere, especially in Europe.

ZeroHedge reports, “Hope for a rebound from Europe’s economic ‘winter’ were dashed this morning as PMIs signaled a renewed downturn.

S&P Global EU PMI fell to a 5-month low of 50.3 (barely in expansion). The decrease in the composite index was broad-based across sectors but skewed towards services, although the services index, unlike the manufacturing output index, remains in expansionary territory.

The composition of the June report showed a broad-based moderation across new orders, employment, new export orders, and backlogs. Firms’ future output expectations declined further as well.”


Posted in Published | 11 Comments