January 12, 2024

3:20 pm

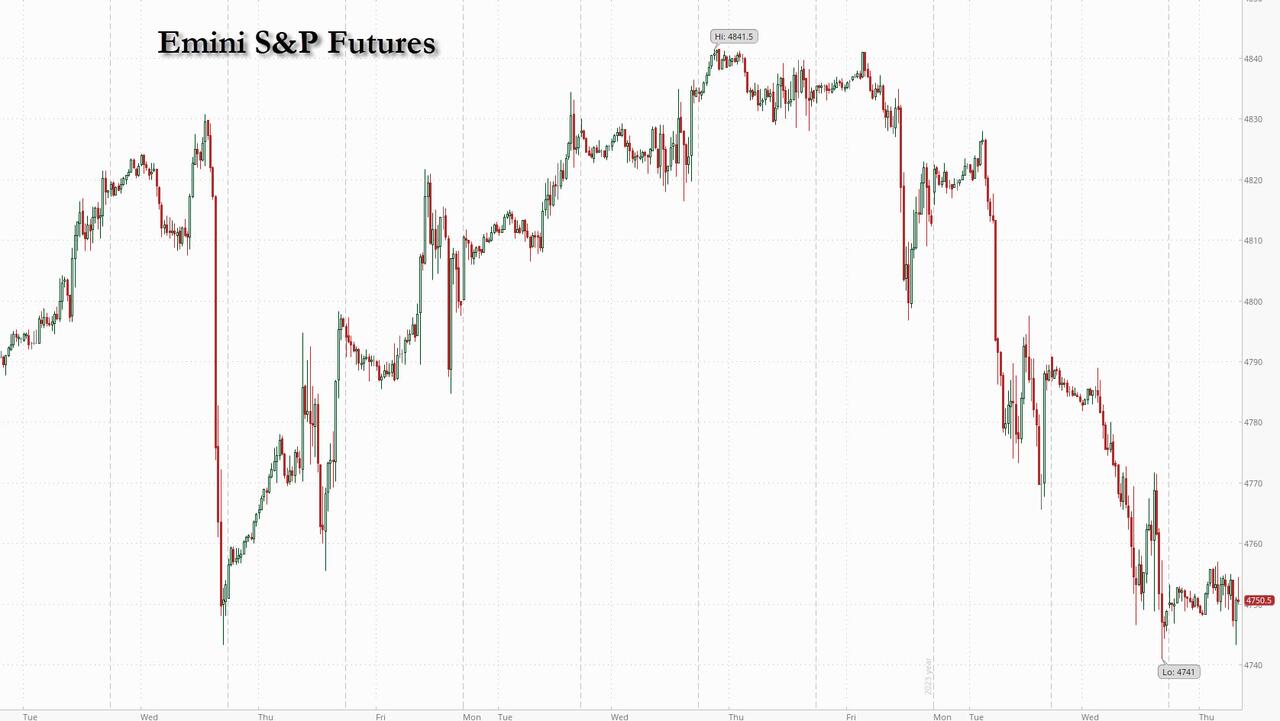
SPX may have completed its final probe higher.  If so, the rising trendline is at 4748.00.  Beneath it is a possible sell signal.


10:34 am

BKX, our liquidity proxy, attempted a rally back above its Cycle Top  this morning, only to fall back beneath it again.  Today is day 253 in the Master Cycle, which allows a possible probe higher (98.51?) early next week.  Regardless, we are seeing an aggressive sell signal with minimal upside.  Earnings season has begun with JPM reporting mediocre earnings but high hopes for rate cuts.

ZeroHedge observes, “Tomorrow Q4 earnings season officially starts with the big banks – JPM, BofA, Citi and Wells – all reporting (as well as BNY, Blackrock, Delta and UNH).
Source: @earningswhispers

And, as discussed earlier, after what has been the best bank stock rally in years, the setup is somewhat challenging even if, as UBS fins analyst Rob O’Dwyer writes, “valuations are not very extended, despite the 20% rally since November.” Still, O’Dwyer concedes that earnings challenges are due to US bank EPS being positively correlated with rising rates over the next 12 months, which suggests pressure on net interest income guidance for 2024. Indeed, given credit metrics remain clean, “there is more downside than upside risk to credit here.” 


7:45 am

Good Morning!

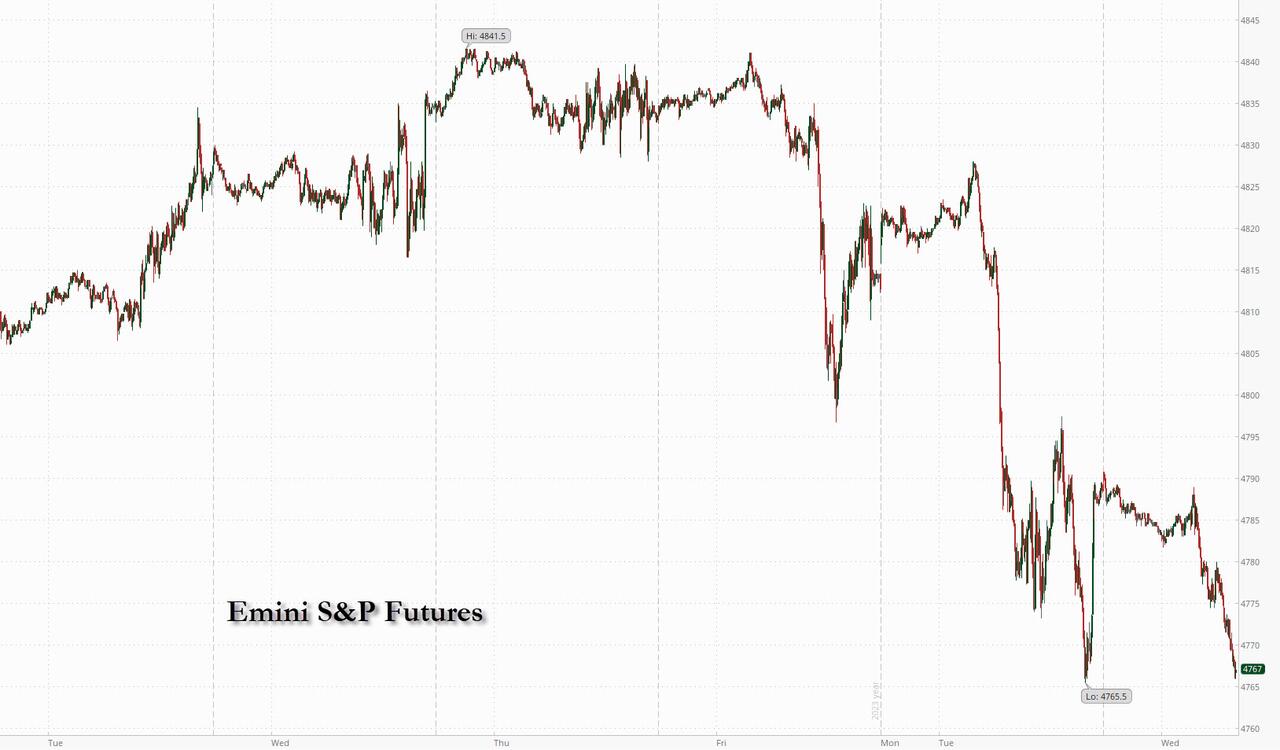
SPX futures have gone lower, testing the 1987 trendline at 4770.00.  Beneath that level is an aggressive sell signal.  The Cycle Top is at 4775.00.  A confirmed sell signal lies beneath Intermediate support at 4675.00.  Earnings season is beginning.  Analysts have already lowered the earnings bar.

Today’s options chain shows Maximum Investor Pain at 4770.00 Long gamma may start at 4775.00 while short gamma may begin at 4765.00.  The options market is heating up, but no clear direction yet.

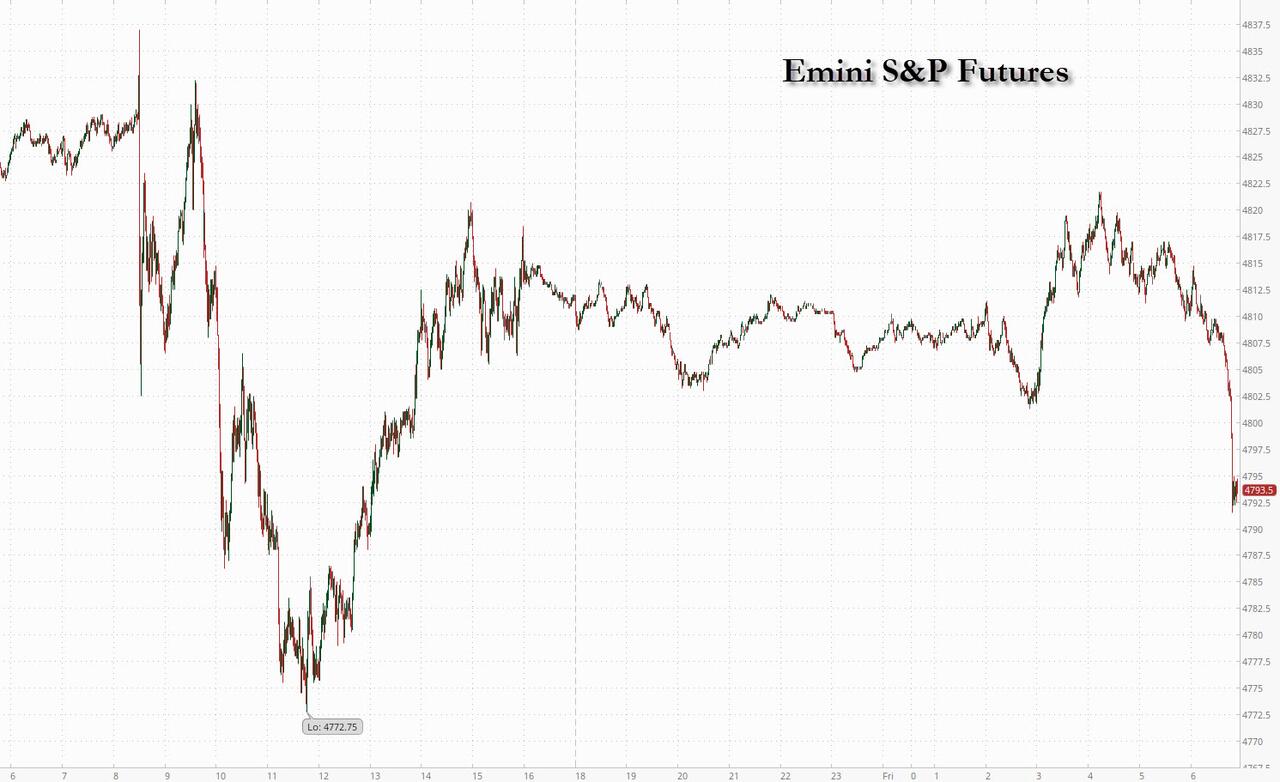
ZeroHedge reports, “US equity futures are muted on the last day of the week, as investors mull the impact of inflation’s rebound on the outlook for monetary easing and waited for earnings from some of the world’s biggest banks. At 6:54am, S&P 500 futures are down -0.5%, dragged lower by poor earnings reported by BofA with JPM fallilng in sympathy, while Nasdaq 100 futures fell 0.6%. 10Y Yields rose to 3.99% and was set to rise above 4.00% after sliding yesterday for reasons still unknown. The dollar reversed earlier losses and was last trading near session highs.


VIX futures continue to consolidate near the low.  Today is day 256 of the current Master Cycle.  A reversal is imminent.

Nest Wednesday’s options chain shows Max Pain at 15.00.  Short gamma resides between 12.50 and 14.00.  Long gamma begins at 16.00 and now sows active interest up to 47.50.


TNX is hovering beneath the 200-day Moving Average at 40.03.  Today is day 253 of the current Master Cycle.  We may expect TNX to retest the rising trendline near 38.00 in the next week.  Thereafter, rates may begin to rise again.  All seems well after the solid 30-year Treasury Auction yesterday.  However, there is danger lurking beneath the surface.

ZeroHedge explains, “The Fed has already started down the path to resuming quantitative easing.

The question is whether they do so before, or after, upending the highly-leverage hedge fund basis trade that has been supporting the Treasury market.”


USD futures are hovering beneath Intermediate resistance at 102.48.  The Cycles Model suggests a pullback near 101.50 before resuming its rally.  A buy signal awaits USD above 102.48.


Crude oil futures rose to an overnight high of 75.25 before pulling back .  It is currently above Intermediate support/resistance at 72.85 and on a possible buy signal. However, should it decline back beneath Intermediate support, it may reveal another Triangle formation that points to lower prices.


Posted in Published | 10 Comments

January 11, 2024

11:00 am

BKX has declined beneath its Cycle Top support at 94.77.  Further confirmation lies beneath Intermediate support at 91.61.  The Cycles Model calls for an intensification of the decline beginning next week, so a prompt reaction may be necessary for longs.  This is a dangerous juncture for bank stocks.


10:25 am

SPX finally exceeded its December 28 high, as indicated this morning and may have reversed beneath critical support  at 4775.00 (Cycle Top) and 4770.00 (1987 trendline).  It may spend the rest of the morning testing those support/resistance areas, but the final decision of the day may be after 1:30 when the results of the 30-year Treasury Auction are released.  Current structure may allow a possible test of the 4818.62 high.

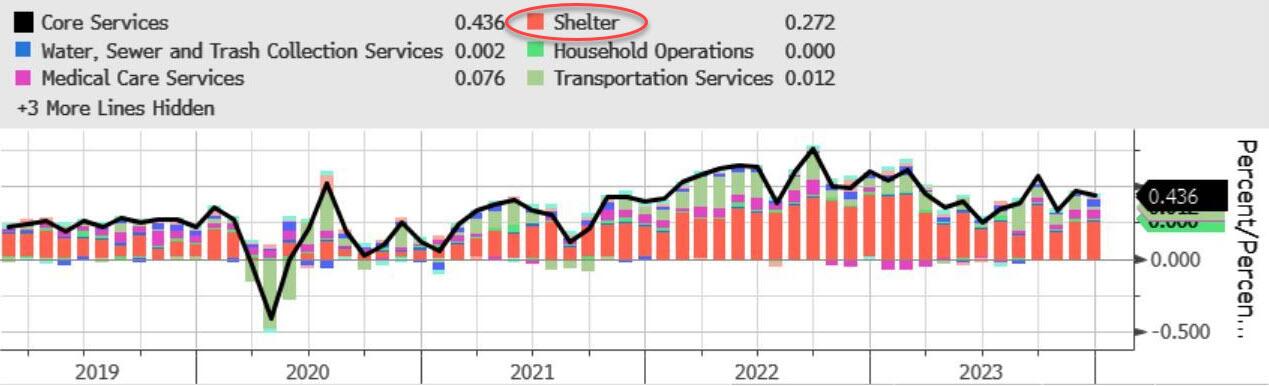
ZeroHedge gives analysis, “Just as we predicted in our CPI preview, where we said that “a hawkish print is more likely than a dovish print”, moments ago the BLS reported that both headline and core inflation came in slightly hotter than expected in December, driven as usual by shelter inflation (food prices hit an all time high but that was expected) which not only accounted for more than half of the “all items” increase, but was also the largest factor in the monthly increase for core items.

That was not a surprise; what was is that according to the BLS, the used car CPI index rose 0.5% after rising 1.6% in November, even though the much more accurate Manheim index has tumbled to the lowest level in three years.”


7:50 am

Good Morning!

NDX futures reached a morning high of 16903.80 on day 260 of the (current) Master Cycle.  The peak on December 28 is currently being marked as the top.  There are likely only two days left to make the new all-time-high.  The current formation may be a “shadow high” that may fail the new ATH.

Today’s options chain shows Maximum Investor Pain at 16780.00.  Long gamma starts at 16800.00 while short gamma may begin at 16750.00.

ZeroHedge remarks, “Decoupling

NASDAQ’s rates obsession has been strong since the summer. Note the latest gap becoming rather short term wide.

Source: Refinitiv

The power of the doji

On Sunday we pointed out the rare doji in SPX. We wrote: “SPX put in a big rare doji candle on Friday. It could be a possible exhaustion signal post the latest sell off, but we need confirmation candles”. The market has squeezed rather hard since then. 4850 is the big short term resistance to watch.”


SPX futures have hit an overnight high of 4802.70, testing round number resistance on day 260 of the Master Cycle.  The high made on December 28 may have been surpassed.  Critical support of both   the 1987 trendline and the Cycle Top remain at 4770.00.  The next question is, can it exceed its all-time high at 4818.62 in the next couple of days?  Decision making on rates may have been turned over to Yellen.  Today’s 30-year Treasury auction and this morning’s CPI may tell us whether that move was a wise one.

Today’s options chain shows Maximum Investor Pain at 4770.00.  Long gamma has it above 4775.00 while short gamma may begin at 4755.00.

ZeroHedge reports, “US equity futures tracked European and Asian stocks higher, but were off session highs as investors prepared for inflation data that will help clarify the path for Fed rates. As of 7:50am, S&P 500 futures pointed to small gains of about 0.1% after the gauge wiped out all losses from the start of the year and closed just short of an all-time high set two years ago on the back of the latest gamma squeeze in Mag 7 stocks; nasdaq 100 futures however continued their relentless meltup, and were 0.4% higher. After ramping all day, stocks eased off in the last minutes of trading during Wednesday’s session, after the NY Fed’s incompetent president John Williams said monetary policy is now likely sufficiently tight to guide inflation back to the 2% target, but that more evidence will be needed before any rate cuts emerge. JPM Asset Management, however, thinks Fed rate cuts could top current forecasts. Cryptocurrency stocks extended an advance in premarket trading after regulators approved exchange-traded funds that invest directly in Bitcoin, which jumped but it was ether that soared higher as the market attention now turns to frontrunning it ahead of its own ETF approval in a few months. US Treasuries climbed, with the yield on the 10-year benchmark dipping below 4%. Oil prices jumped after an oil tanker was boarded by Iranian military off the coast of Oman. WTI rises 1.6% to trade near $72.50 while Brent is above $78 a barrel.”


VIX futures continue to consolidate at the lows.  Today is day 255 of the current Master Cycle.  Support lies at 12.36 in a probable flat correction.

Next Wednesday’s (January 17) options chain shows Maximum Investor Pain at 15.00.  Short gamma rules from 12.00 to 14.00.  Long gamma begins at 16.00 and runs hot to 47.50.


TNX had been declining to 39.37 when the CPI was released this morning, prompting a sharp reversal back toward the 200-day Moving Average at 40.56.  There is a buy signal above the 200-day which may be confirmed above the neckline at 41.00.

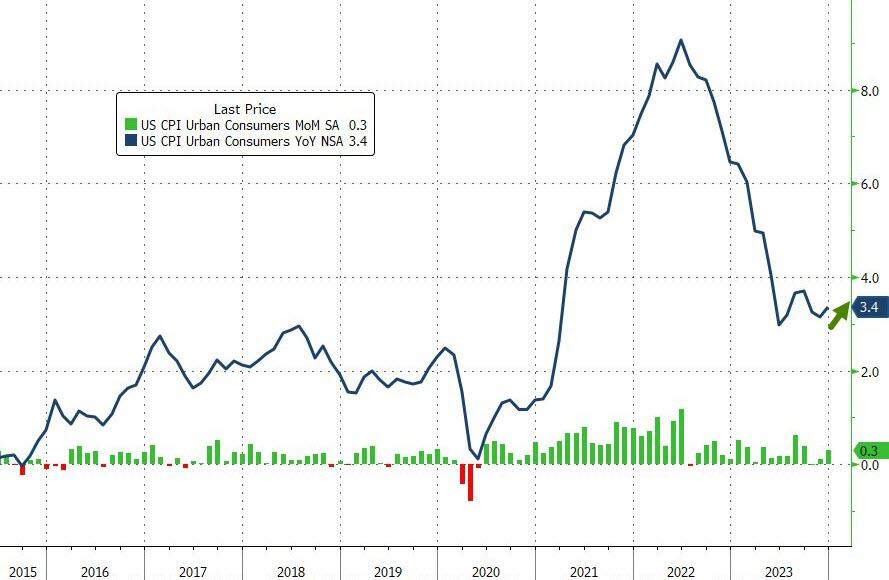
ZeroHedge reports, “Headline Consumer Price Inflation printed hotter than expected in December, +0.3% MoM vs +0.2% exp and +0.1% prior, pushing the YoY headline CPI up to +3.4% (from +3.1% prior and hotter than the +3.2% exp)…”


Posted in Published | 6 Comments

January 10, 2024

12:02 pm

SPX has a potential of one more probe higher, but has possible structural limitations at 4781.00.  Currently the 1987 trendline is near 4763.00-4765.00.  The daily Cycle Top resistance is at 4769.67, imposing its own limitations on the rally.  SPX may have the ability to send one more probe higher today, completing the retracement.

Note:  The 10-year Treasury Note Auction is being held today and the 30-year bond auction will be offered tomorrow.

ZeroHedge observes, “One day after a stellar 3Y auction launched the coupon Treasury issuance for 2024, moments ago we got the sale of the first benchmark piece of paper for the new year, when some $37BN in a 9-Year 10-Month reopening were sold to the public in a generally strong auction.

The auction priced at a high yield of 4.024%, which was a sharp drop from December’s 4.2960 and was the lowest yield since the 3.999% August auction. More notably, the high yield tailed the When Issued 4.019 by 0.5bps. This was the 4th consecutive tailing 10Y auction, and the 11th non-stop through auction in a row (September was on the screws). More remarkably, there have been only 3 stop-through 10Y auction in the past 27 months!”


10:00 am

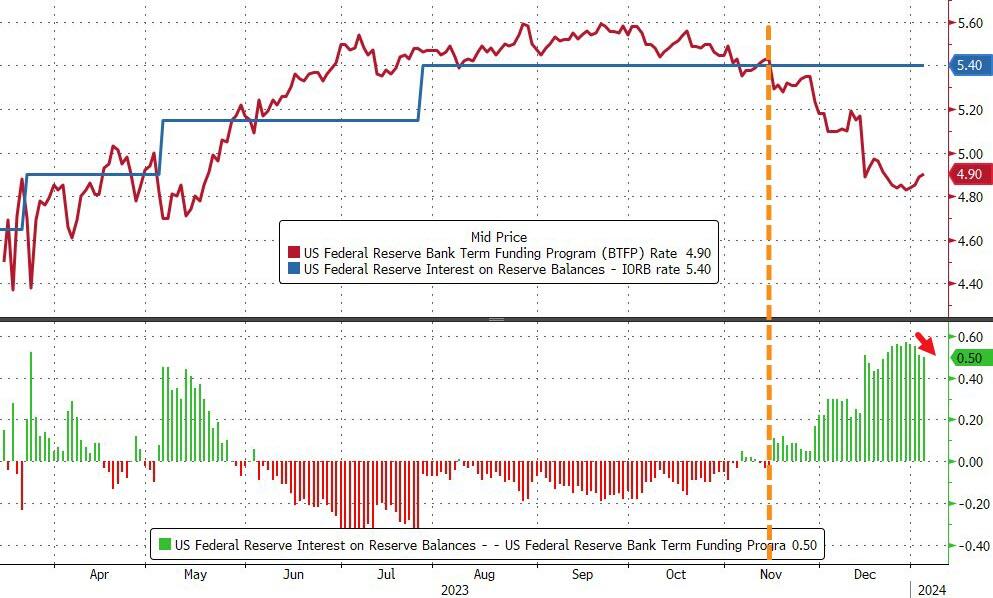
BKX has dropped to the lower end of its one-month trading range.  Should it decline further, a bearish cross beneath its Cycle Top support at 94.57 may produce a sell signal.  Today is day 251 of its current Master Cycle, a week early.  However, should the decline take place, it may confirm the top is already in.  Should the BTFP expire, the Federal tit is removed and banks may have to fend for themselves.  Should rates also rise, the outcome may not be pretty.

ZeroHedge remarks, “The Federal Reserve is likely to retire the Bank Term Funding Program in March. This would entail an additional ongoing headwind for reserves, and thus liquidity, through 2024. At the margin, this adds weight to the case for the Fed cutting interest rates sooner in the year.

The BTFP was created in the wake of the SVB crisis to help struggling banks get access to liquidity when bond prices were dropping. However, its use in recent months has jumped to over $140 billion. That is not, however, a sign of banking stress.

The chart below shows the usage of the BTFP along with the rate paid at the 99th percentile in the fed funds market relative to the upper bound of the range for fed funds.

As can be seen, this is under zero, i.e. banks are not having to pay up to get liquidity.”


8:50 am

Good Morning!

NDX futures remain stalled at the short-term resistance at 16662.27 and a 64% retracement of the first week decline.  Today is day 259 of the (old) Master Cycle, leaving NDX with diminishing capabilities of a new all-time high.  Should the decline resume, it may do so with an increased intensity as momentum factors are increasing.

Today’s options chain shows Max Investor Pain at 16725.00.  Long gamma may begin at 16750.00 and short gamma starts strong at 16720.00.  Dealers may be fighting a negative tape today.

ZeroHedge remarks, “Market narratives have been around for ages. However, the internet and, more recently, social media allow narratives to spread much quicker. Accordingly, they have become more frequent and potent market forces. Following economic data, corporate earnings, politics, global affairs, and many other factors are still crucial for investors. But equally important, especially over short periods, is identifying which narrative(s) most heavily impact markets. Today’s popular narrative is a growing consensus for the Fed to engineer a soft landing and a Goldilocks economy. It’s worth appreciating the Fed and Jerome Powell, purposely or not, started the narrative.

As the fiscal stimulus that drove above-average economic growth in the post-pandemic era exits the system and monetary policy remains very tight, economists and investors wonder what comes next. The scenario rapidly gaining in popularity is the Goldilocks narrative.”


SPX futures remain flat beneath the 1987 trendline at 4765.00.  There was a slight gain yesterday to the 67% retracement value,  also at 4765.00.  We canot rule out the potential for another probe higher, but the old Cycle is winding down with less and less capability to forge higher.  On the other hand, should a reversal take place today, the Cycles Model suggests a potential for a panic decline over the next week.

Today’s options chain shows Max Pain from 4745.00 to 4755.00.  Long gamma starts with a 7,520 contract call wall at 4760.00.  Short gamma begins at 4740.00.  Speculation is overwhelmingly bullish.

ZeroHedge reports, “US stock futures were unchanged, trading in a narrow range and shifting between modest gains and losses, as investors clung to the sidelines ahead of a key US inflation report. As of 7:50am, Nasdaq 100 futures gained 0.1% while S&P 500 index futures were little changed. The Treasury 10-year yield crept back under 4%, before recovering much of the move. The Dollar was also unchanged while the yen tumbled after the latest Japanese wage data confirmed there will be no rate hikes soon, if not ever. Brent crude rose 0.5% and was trading just below $78 a barrel in a choppy session following more attacks on vessels in the Red Sea that could upset both oil supplies and trade flows. Bitcoin dropped to trade around $45K after a hacked post on the SEC’s X/twitter account prompted large price swings on Tuesday. Today’s calendar is sparse: just wholesale inventories and trade on deck.”


VIX futures are consolidating near yesterday’s low.  Today is day 254 in the Master Cycle and we are looking for a bottom before the week is over.

Today’s options expiration shows Max Pain at 13.00.  There is a small contingent of short gamma at 12.00.  Long gamma starts at 15.00 and runs to 37.00.


TNX is marching the flat line at 40.00 this morning.  Should it succeed in going higher, the neckline at 41.00 may be in its sight.  The 10-year and 30-year auctions will be interesting to watch.  The Cycles Model indicates trending strength to start rising.

ZeroHedge observes, “While not nearly as interesting as the upcoming long-duration 10Y and 30Y auction later this week, all eyes were on today’s sale of 3Y paper as it was the first coupon auction of the year. And despite some erroneous previews at competing publications, the auction was nothing short of stellar.

Pricing at a high yield of 4.105%, down 38.5bps from the December yield of 4.490%, and the lowest 3Y high yield stop since May 2023, today’s auction stopped through the When Issued 4.116% by 1.1bps, the biggest stop through since Aug 2023.

The bid to cover was 2.672, a solid jump from the 2.416 in December, and the highest since September.”


Posted in Published | 5 Comments

January 9, 2024

3:43 pm

SPX is closing right at the cusp of a breakdown after retracing 67% of the first week decline.  This appears to be a one-off event.  As mentioned this morning, it is attempting a close at “Max Pain” at 4750.00.  A close beneath that may result in a decline.  Nearby support is at 4743.00, beneath which short gamma may take hold at 4740.00..


8:15 am

Good Morning!

NDX futures have reversed down to 16534.40 this morning after being repelled by short-term resistance at 16650.00, a 66% retracement.  Today is day 258 of the former Master Cycle.  Thus far, it appears to be early, on December 28.  An early appearance may be followed bay a “shadow high” on the correct day, that is today.

This morning’s options chain is flirting with short gamma at 16600.00.  There is a huge put wall at 16680.00 that may block a further rally.

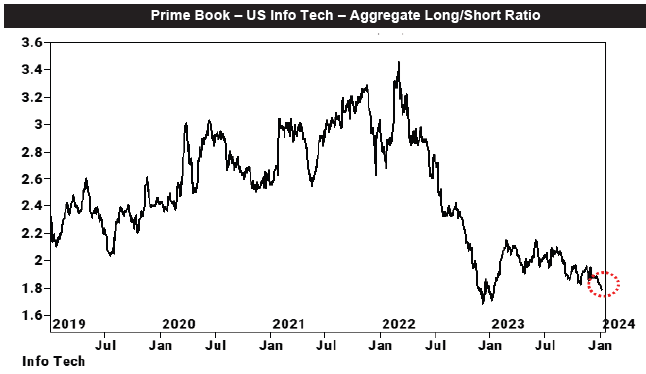
ZeroHedge remarks, “In retrospect today’s torrid meltup in the Nasdaq, and the MagnifiSeven in particular, was largely preordained following our weekend post that “Hedge Funds and Long-Onlies had Resumed Dumping Tech Stocks At Furious Pace” with the “Largest Selling Since Mid-October.” Of course, in this market which loves inflicting max pain on a daily if not hourly basis, it was inevitable that the one trade which the smart money was rapidly liquidating – in this case the Info Tech Long/Short pair trade…

… would be insta-jammed higher, leading to the best day for the Nasdaq since mid-November.”


SPX futures reversed down to 4739.40 after being repelled by the 1987 trendline at 4765.00.  AS mentioned earlier, we may be watching a “shadow Cycle”  occurring on Day 258.  Barring a further rally, we will leave the Master Cycle high at December 28.

Today’s options chain shows Max Pain at 4750.00.  Long gamma may start at 4755.00 while short gamma starts at 4740.00.

ZeroHedge reports, “US stock futures dropped amid a risk-off tone as Monday’s tech-fueled bounce fizzled and investors turned their attention to this week’s inflation print as well as the start of corporate earnings season. As of 7:40am ET, S&P futures were down 0.3%, and Nasdaq futures dropped 0.5% following European bourses lower. The tech rally in US stocks on Monday came as Nvidia surged after announcing new AI products for personal computers. The Nasdaq 100 jumped the most since November on Monday and the S&P 500 traded near a record high while Japan’s Nikkei 225 index closed up 1.2% — a level unseen since March 1990. Bonds are lower pushing the 10Y yield as high as 4.05% as oil bounced back from the largest drop in about a month on signs of a weaker physical market, including a deep pricing cut by OPEC+ leader Saudi Arabia; Brent traded near session highs around $78. The USD was flat while the yen reversed earlier gains. Bitcoin dipped after surging past $47,000 on bets that the US is set to approve the first spot ETF.”


VIX futures are consolidating beneath the 50-day Moving Average at 13.95.  The Cycles Model calls for the probable uptrend ti become more established at the end of the week.

Tomorrow’s op-ex shows Max Investor Pain at 13.50.  Short gamma is in short supply while long gamma begins at 15.00.


TNX is consolidating beneath its 200-day Moving Average at 40.50 after a brief challenge in the overni8ght session.    The Cycles Model suggests a gathering of strength in the uptrend that may break out early next week.  The uptrend may resume above the Head & Shoulders neckline at 41.00.


USD futures pulled back to 101.83 this morning.  A decline to an estimated 101.00-101.50 may be in store for today.  The rally appears to be a long-lasting one, to early March, as a world-wide decline in stocks and bonds develops.


Posted in Published | 7 Comments

January 8, 2024

11:08 am

BKX, the market’s liquidity proxy, may have made its Master Cycle high on Friday.  Although there may be a few days left in the current Cycle, the retracement structure may be complete.  Evidence of this may be a decline beneath 95.00.

ZeroHedge remarks, “Buried on a Saturday morning, amid the hubbub of politicians and media scrambling to signal their virtue over the 3rd anniversary of ‘January 6’, Dallas Fed President Lorie Logan dropped a couple of tape-bombs that suggest Powell and his pals are ‘worried’ about more than just jobs and inflation.

Notably, prior to joining the Dallas Fed last year, Logan was heavily involved in the financial plumbing of the Fed’s policy mechanism as SOMA Manager at the NYFed, and so her views are going to carry a lot of weight on the FOMC – and the two subjects she discussed point to potential financial stability concerns.

Her first point can be summarized as a concern that:

‘Liquidity is draining (too damn) fast…'”


11:00 am

SPX made an exact 38.2% retracement this morning of last week’s decline.  The decline may resume with considerable strength imminently.  Today may be the start of one of those “limit down” days mentioned on Friday.


7:45 am

Good Morning!

NDX futures dropped to 16222.00 before a morning bounce back to the flat line.  NDX is flirting with a confirmed sell signal beneath Intermediate support at 16296.25.  The next support to fall may be the 50-day Moving Average at 15829.21 as the decline may pick up momentum this morning.

Today’s options chain shows 16300.00-16310.00 being highly contested.  Long gamma may begin at 16340.00 while short gamma may begin at 16200.00.

ZeroHedge remarks, “Late last year, Goldman’s Prime Brokerage, the bank’s most actionable client-facing division which keeps daily tabs on all the latest hedge fund activity and is happy to share the data with a select group of top clients, launched its weekly US Equities Weekly Rundown: a weekly must-read compilation that aims to consolidate the latest positioning and flows intelligence, market themes, and actionable ideas from thought leaders and risk takers across the GS franchise. It is an indispensable piece for every serious trader, and below we excerpt from the latest full report for the benefit of our premium and professional readers (full analysis available to our pro subscribers in the usual place).”


SPX futures declined to 4677.00 over the weekend, then bounced to a near recovery of Friday’s close.  The Cycles Model calls for an intensification of the decline which may start after the opening bell.

Today’s options chain shows Max Pain at 4705.00.  Long gamma begins at 4720.00 while short gamma starts at 4700.00.  Options do not provide insurance.  They simply transfer risk.  At this point the risk is on the dealers who must sell short to cover losses in a declining market.

ZeroHedge reports, “US stock futures dipped on Monday and Treasury yields gained as traders jostled for position in the wake of last week’s selloff coupled with at very confusing jobs report which was strong at the headline level and a disaster when looked closer. As of 7:40am ET, S&P 500 futures declined 0.1% with Boeing retreating almost 8% after a fuselage section on a 737 Max 9 aircraft ejected during a flight over the weekend, leading to another FAA-mandated grounding of the aircraft. Spirit AeroSystems, which installed the panel, slumped 21%. European stocks followed declines in Asia. The dollar was flat, bitcoin reversed earlier losses and and oil slid almost 3% after Saudi Arabia cut official selling prices for all regions amid persistent weakness in the market.”


VIX futures rose to 14.18 this morning before settling back beneath the 50-day Moving Average at 14.09.00This is a good position to accumulate VIX shares and futures as a hedge against falling stock prices.

Wednesday’s options chain shows Max Pain at 12.50.  Short gamma appears to be non-existent while long gamma begins at 15.00.


TNX rose to 40.63 over the weekend after challenging the Head & Shoulders neckline at 41.00 on Thursday.  The Cycles Model suggests a burst of strength may be due today, possibly launching it over the line.

ZeroHedge remarks. “US data from last week were not enough, from the perspective of the economy, to endorse the amount of rate cuts from the Federal Reserve expected by the market.

Payrolls and the jobs data released last week demonstrated why the market – and the Fed – shouldn’t take it too seriously as a real-time snapshot of the labor market.

On the surface, the data was solid next to expectations, but if you go digging you will always find elements to back up a bullish or bearish case.”


Posted in Published | 4 Comments

January 5, 2024

1:31 pm

Today is day 246 in the current Master Cycle for BKX.  You would think there may be another two weeks before a reversal may happen.  However, it is fast approaching the 61.8% Fibonacci retracement at 98.51 which may spell the death knell for this rally.  The Cycles don’t just measure time.  They also measure price.  A Cycle may be lengthened or shortened by its relation to the price target.  Keep that in mind as a very strong burst of energy is due in the banking sector in the next week.

ZeroHedge remarks, “Usage of The Fed’s BTFP bank bailout facility surged by over $5BN to a new record high of $141BN…

Source: Bloomberg

The BTFP-Fed Arb continues to offer ‘free-money’ (and usage of the BTFP has risen by $32BN since the arb existed), but the spread has narrowed a smidge from a peak near 60bps to 50bps today…

Source: Bloomberg

Which will make it hard for The Fed to defend leaving the facility open after March when its “temporary” nature is supposed to expire.”


6:30 am

Good Morning!

I have a morning appointment and may not return until after the open of the Markets.

SPX futures continued their decline to 4672.30 thus far.  Intermediate support lies at 4640.82, beneath which lies a confirmed sell signal.  Intermediate support may not hold, leaving the 50-day Moving Average at 4519.03 as the next possible support.  A word of warning.  The Cycles Model suggests that trending strength may increase substantially starting next week and lasting a possible two weeks.  Trending strength tends to magnify the current trend.  The implication is that we may see one or more “limit down” days during that period.

Today’s options chain shows Max Pain at 4715.00.  Long gamma starts at 4750.00.  Short gamma begins at 4700.00.


VIX futures have ramped up to 14.58, exceeding the 50-day Moving Average and creating a double confirmed buy signal.  The target for this rally may be the March 13 high at 30.81.  Depending on the velocity of the rally, the ultimate target may be much higher.

Next Wednesday’s op-ex shows Long gamma residing between 15.00 and 17.00.  Short gamma has all but disappeared.  Investors are just not prepared for an explosion in the VIX.


TNX futures have risen to a morning high of 40.51, confirming the fears of investors that the rally in treasuries may be over.  TNX has exceeded its 200-day Moving Average, creating a confirmed buy signal for yields.

Posted in Published | 2 Comments

January 4, 2024

11:33 am

SPX may be at the end of a less-than Fibonacci retracement at 30.1%, a very weak rebound from this morning’s new low.  We may see the decline resume with strength within the hour.


7:45 am

Good Morning!

NDX futures have continued to decline to 16340.10 this morning.  It is due for a short-term bounce that may be complete by the end of the day.  The bounce target may be short-term resistance at 16608.00.    However, should NDX continue to decline beneath Intermediate support at 16268.10, the decline may resume uninterrupted.

Today’s options chain shows Max Pain at 16425.00.  Long gamma may begin at 15450.00, but without much conviction to 16475.00 to 16500.00.  Short gamma starts at 16410.00 an remains strong beneath it.

ZeroHedge remarks, “Hard to get excited

JPM’s positioning intelligence team, who nailed the melt up, summing up the view here: “… it’s hard to be excited about the market in the near-term from a positioning standpoint, given how much has changed in the past ~2 months.”

Lot of longs

Positioning is elevated.”


SPX futures are hovering near the low end of yesterday’s trading range.  Normally SPX would have bounced to 4750.00 today.  Instead, the bounce may have truncated at 4729.29 and the decline appears to have resumed to the close.  A gap down at the open may suggest a panic decline may be underway.  If so, the next support may be the 50-day Moving Average at 4511.13.  For most investors, the uptrend is still not broken.

Today’s options chain shows Max Pain (for investors) at 4705.00. Long gamma begins above 4710.00 while short gamma starts beneath 4700.00.  The options market may easily go out of control.

ZeroHedge reports, “After the worst start start to the year in almost two decades – it was just the third time in history that the Nasdaq started the year with back to back 1%+ declines (the other two years were 1980 and 2005) – markets took a breather on Thursday, with US equity futures posting small gains even as they remained toward the bottom of Wednesday session range. As of 7:50am, S&P futures gained 0.1% after swinging between modest gains and losses and supported by the Dec 20 0DTE flash crash lows, while Nasdaq futures were down 0.1%; Treasury yields resumed their ascent, edging closer to 4%, and last trading at 3.95% as part of a bear steepening, potentially a delayed reaction to the higher-for-long message from the Fed. The dollar is higher and the USDJPY is surging to the highest since mid-December, rising above 144, just as everyone was convinced the pair would tumble to 130 next. Commodities are also stronger led by Energy. Today’s macro data focus is on ADP, Jobless Claims, and Job Cuts all ahead of tomorrow’s Nonfarm payrolls which should help shape the macro narrative as we are about to enter Q1 earnings season.”


VIX futures remain flat, but at yesterday’s session high.  A breakout above yesterday’s high and the 50-day Moving Average at 14.22 produces a confirmed buy signal.  The target for this rally may be the March 2023 high at 30.81.

The January 10 options expiration shows Max Pain at 13.50.  There is little short gamma.  Long gamma begins at 17.00 and runs to 24.00.


TNX may be resuming its rally toward the 200-day Moving Average at 40.42.  A confirmed buy signal awaits above that level.  Mid-Cycle support/resistance lies at 40.90.  Above those resistances it may be clear that the decline has ended.

ZeroHedge remarks, “Today we get to see the cherry-picked highlights from The Fed’s ‘Great Pivoting’ in December.


Will they admit what we all think happened? Of course not

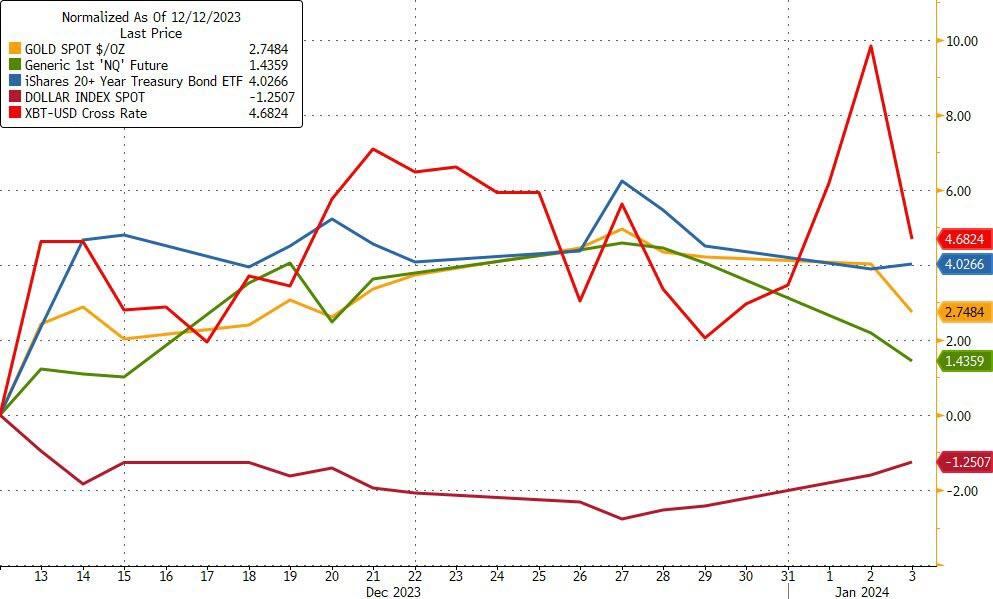
Since the ‘dovish’ flip-flop at the last FOMC meeting on December 13th, markets have mimicked ‘the QE trade’ – dollar down, everything else up (led by crypto)…”

Source: Bloomberg


USD futures have slowed their ascent at they approach Intermediate resistance at 102.75.  A pullback near 101.50 may be in order here before the advance resumes.  A good time to accumulate USD shares/futures.  We may continue to see predictions of the Dollar’s demise until it becomes painfully evident that USD is about to become stronger.


Posted in Published | 2 Comments

January 3, 2024

8:25 am

Good Morning!

NDX futures declined to 16423.00 thus far, as it searches for Intermediate support at 16242.00.  A bounce may normally occur at or above Intermediate support.  However, should it decline through that support, the 50-day Moving Average lies at 15738.76 as the next level.  The average target for this decline may be the October low at 14058.30.  WE will monitor the decline to ascertain whether it goes deeper.

Today’s options chain shows Max Pain at 16575.00.  Long gamma may start at 16000.00 while short gamma begins at 16570.00.  Short gamma may rule the day.

ZeroHedge remarks, “The big short is now a big long

What a difference a year makes. Non dealers exposure in US equities is at the highest levels in “forever”.”


SPX futures declined to 4720.50 this morning as larger losses are consolidated.  Overhead resistance is at 4750.00 where the short-term trendline, the 1987 trendline and the Cycle Top all reside.  Should the decline continue, the next level of support is the Intermediate level at 4626.51 beneath which the sell signal is confirmed.  The Cycles Model indicate that the next two weeks may be particularly bearish.  The normal target may be the October low at 4103.78.  However, the decline may go lower.

Today’s options chain shows Max Pain at 4745.00.  Long gamma dominates above 4750.00.  Short gamma reigns beneath 4735.00.

ZeroHedge reports, “The risk off tone that has dominated the 2024 mood so far extended into a second session, and this time in addition to selling in both stocks and bonds, we are seeing crypto join the fray (the reason being attributed to this tweet). US equity futures and global market are experiencing some selling and profit-taking after the recent torrid Santa Rally, as we enter the first of several important macro data days: today the focus will be on ISM Mfg report and the December Fed Minutes. Interestingly, despite the weakness, yesterday’s US session saw a $7.8bn MOC to buy, and in its market intel note this morning (available to pro subscribers), JPM writes that for all the weakness “it does feel like there are buyers below current levels as the SPX struggles to breach 4,800.” That said, as of 7:45am, S&P futures were down 0.4% to 4,765, near yesterday’s session lows; Nasdaq futures dropped 0.7%. Bond yields are higher as we see bonds come for sale alongside stocks globally. 10Y Treasury yields rose to 3.98%, the highest since mid-December and a move above 4% will likely add more volatility to equity markets; the USD extended its gains; Brent jumped to session high around $77, rising form a sub-$75 low after Libya’s Sharara oil field unexpectedly shutdown amid mass protests, removing some 265K bpd in daily output although commodities overall remain mixed on concerns about China’s economy.”


VIX is consolidating beneath the 50-day Moving Average at 14.49.  Yesterday was a wake-up call with the sudden realization that stocks don’t only go up.  A confirmed buy signal lies above the 50-day.

Wednesday’s op-ex shows Max Pain at 13.50.  Short gamma rules between 12.00 and 13.00.  Long gamma resides above 15.00 and runs to 30.00.


TNX rose to 40.08 this morning as rising rates attract attention.  The Master Cycle low on December 27 gave traders a reversal and aggressive buy signal.  Unfortunately, most do not see this as a positive because TNX is beneath the 200-day Moving Average at 40.40.  Once above it, however, investors may take appropriate action.

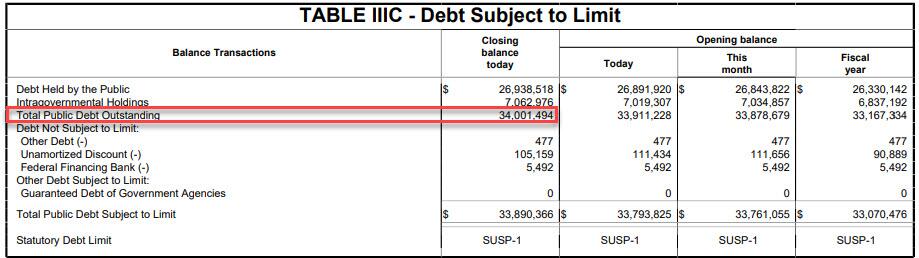
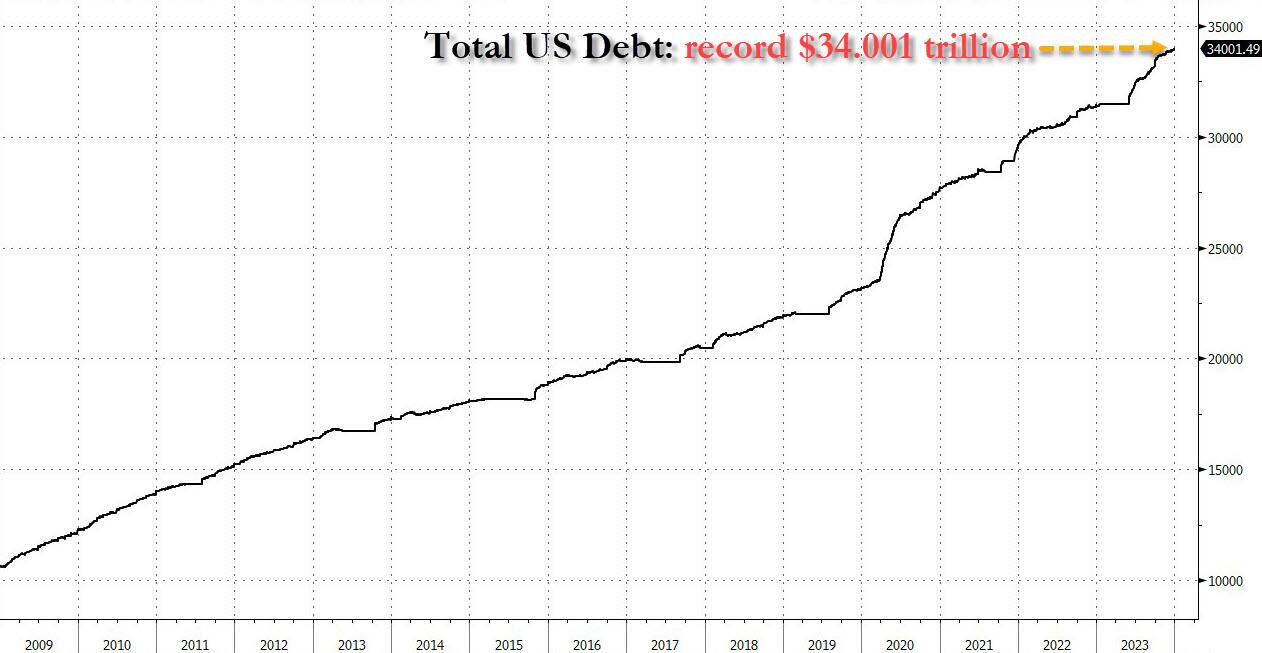
ZeroHedge observes, “The US Treasury has a morbid habit of revealing big, round numbers of debt around major calendar milestones, and the new 2024 year was no different because according to the latest Treasury Daily Statement published after the close today and reflecting the US Treasury’s financial statements as of Dec 29, 2023, total US debt as of the end of the year was – drumroll – just over $34 trillion for the first time ever, or $34,001,493,655,565.48 to be precise.

Since this is a topic we have covered more or less daily for our 15 year existence, we don’t need to say much suffice to show a chart of total US debt since zerohedge launched in Jan 2009, when total US debt was only $10.6 trillion. We sure have gone a long way since then.”


USD cash may be approaching Intermediate resistance at 102.82 after exploding out of its Master Cycle low on December 28.  It is on an aggressive buy signal with confirmation of its buy at Intermediate resistance.


Posted in Published | 3 Comments

January 2, 2024

2:24 pm

BKX, our liquidity proxy, may be attempting to make the 61.8% Fibonacci retracement at 98.51.  Today is day 243 in the current Master Cycle, which allows a few more days of rally either until something breaks or quarterly earnings begin reporting the week of January 8.

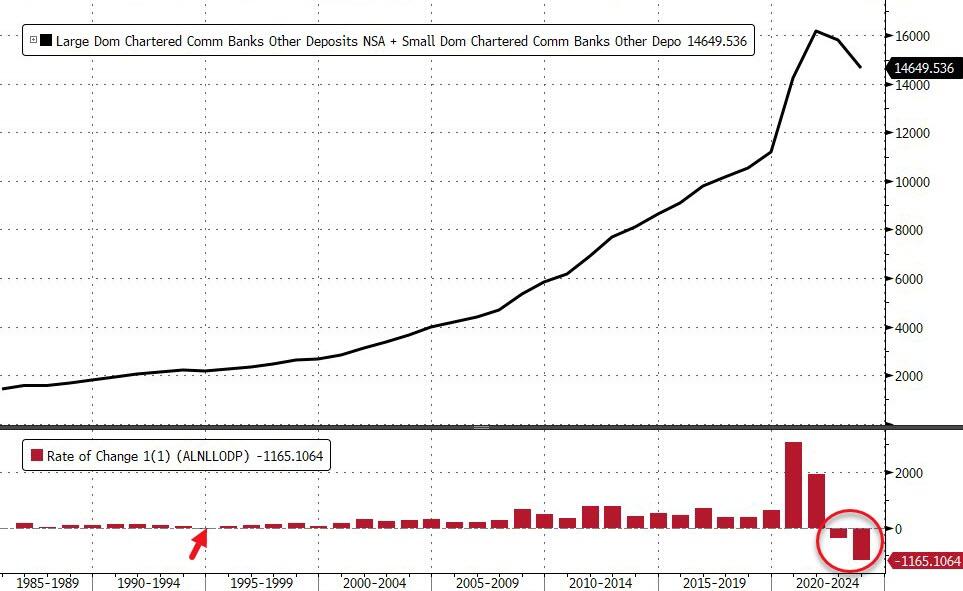
ZeroHedge observes, “n a non-seasonally-adjusted basis (why adjust when we are looking at annual changes), US domestic banks saw a stunning $1.17TN in deposit outflows (ex-large time deposits) in 2023 – the largest annual decline ever (and only the 3rd annual decline on record going back to 1985 – 1994, 2022, and 2023)…

Source: Bloomberg

Interestingly, money-market funds saw inflows of around $1.15TN almost perfectly mirroring the deposit exodus from banks…”


2:07 pm

SPX has declined both below the 1987 trendline and the diagonal trendline that defined the lows in the year-end rally, both at 4750.00.  It also declined beneath the Cycle Top at 4742.94.    Today is day 251 in the Master Cycle.  Although early, SPX has also met its structural high, leaving a truncation in place.   While not attaining the January 2022 high, both time and price targets may have been met for this rally.   An aggressive sell signal may have been made,  Aggressive signals are those that are often (1) short-term, awaiting confirmation, (2) may be early, allowing attempts at higher highs or lower lows, (3) subject to volatility where gains/losses appear uncertain.   However, aggressive moves tend to prove out over time and allow a greater gain on a new position.


9:15 am

Good Morning!

I had originally intended to put the long charts up last night, but family events took precedence.

DJIA futures declined to 37463 this morning, indicating a potential reversal.  Cycle Top support is at 36985.00.  A decline beneath that level gives us an aggressive sell signal.  The traeding bands have narrowed considerably, suggesting a probable slingshot move to the October 2022 low.  Note that the Indu rose above its Cycle Top in 2021 but further advances were stopped by the 1987 trendline during 2021.  It has stayed beneath the trendline and Cycle Top resistance until December 2023 in a final probe called a throw-over.  The Industrials are favored by international investors due to their liquidity and stability.

INDU futures remain above  the Cycle Top support at 36985.06.  A decline beneath that level produces an aggressive sell signal.


The SPX was also able to rise above the 1987 trendline in 2021, but fell back beneath it in April 2022.  It has met a double resistance at 4750.00 and the Cycle Top at 4815.00.  SPX has not been able to crack the 2022 ceiling due to these resistances, but the structure suggests a completed uptrend.  This may be called a truncated rally where it had structurally weakened to be unable to make a new all-time high.  The SPX is favored by domestic institutions for its liquidity, but has fallen out of favor recently due to weakened performance and overperformance of the seven largest NDX stocks..

SPX futures fell beneath the 1987 trendline at 4750.00 to 4732..00 thus far.  This produces an aggressive sell signal on the weekly chart.  We will follow the daily chart from here on, but this picture substantiates the necessity for a reversal here.


NDX has remained above its 1987 trendline for all of its existence, attracting retail investors and hedge funds.  The Cycle Top is at 17068.  The NDX rose to within 100 points of the Cycle Top but was unable to reach it.

NDX futures have fallen the most of all the indices, breaking the diagonal trendline for an aggressive sell signal and nearing its first short-term support at 16451.00.  Confirmation of the sell signal lies beneath Intermediate support at 16243.00.

ZeroHedge says, “Not Buying The Dips Here… Yet.”


VIX futures have reached a morning high at 14.23, short of a confirmed buy signal at 14.50, where we find the 50-day Moving Average.  The VIX made its Master Cycle low on December 13 and has remained above it since.  Investors have steered clear of it because of its historically low level.  However, it  may be at a good accumulation level, nonetheless..


TNX continues to advance from its Master Cycle low made on December 27, day 252 of its Master Cycle.  Today is day 258.  The chances of a deeper low are diminishing by the day.  The Buy signal resides at the 200-day Moving Average at 40.37.


Posted in Published | 4 Comments

December 29, 2023

12:46 pm

SPX has declined to the convergence of the short-term trendline and the 1987 trendline.  A break beneath the double trendline offers an aggressive sell signal.  One should not own stocks beneath that point.  The first confirmation is at the short-term line at 4698.96 (4700.00), another aggressive confirmation.  Take advantage of these supports to unencumber yourself of any longs.  Shorts may be taken at those points, as well.  When the liquidity spigot closes, we may see a “no bid” event.

ZeroHedge remarks, “Over a month ago (and well before the Fed’s “shocking” dovish pivot) as the Fed’s Overnight Reverse Repo tumbled below $900 billion for the first time since June 2021 amid a growing debate of where and when the Fed’s reserve scarcity constraint will be hit, we warned that liquidity is rapidly approaching the reverse repo constraint level which could emerge as soon as the RRP facility dropped to $700 billion, at which point the market’s all-important credit plumbing will start to crack”

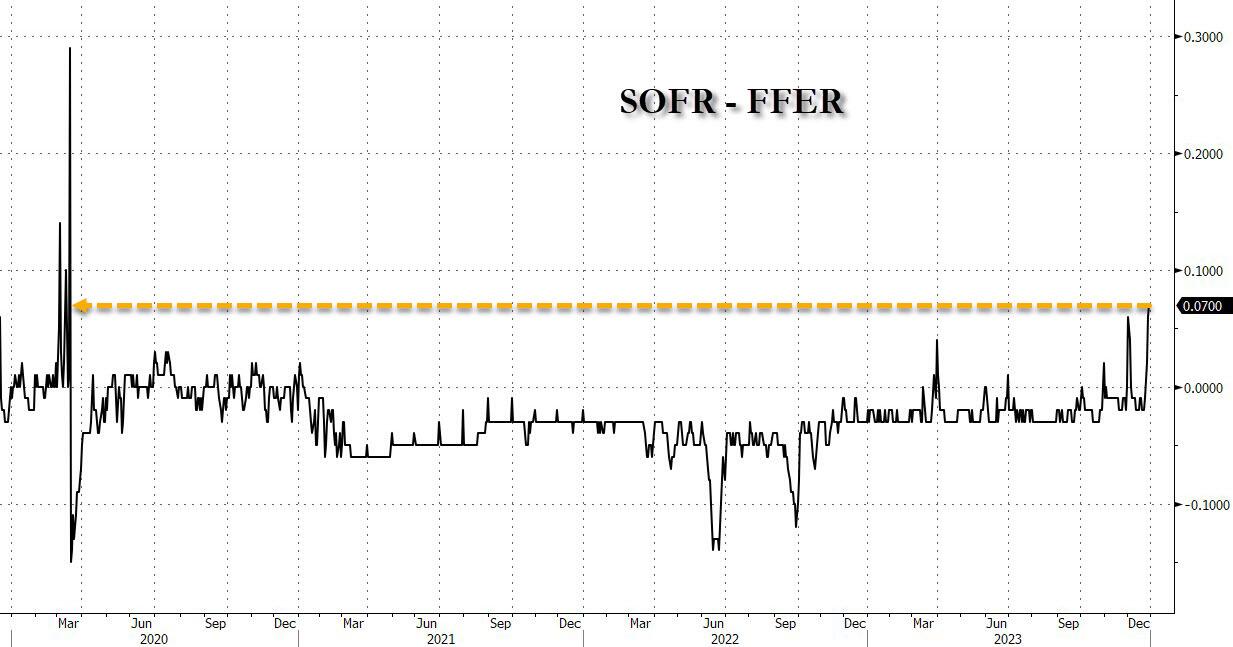
ZeroHedge further observes, “Earlier today, when discussing the sudden spike in the SOFR rate to an all time high 5.40% and which dragged the SOFR-Fed Funds spread to the highest since the March 2020 repo crisis…

… we said that “two factors are the likely culprits: the year-end liquidity crunch, and the recent sharp increase in the Fed’s reverse repo facility, which has increased from a multi-year low of $683 billion on Dec 15 to yesterday’s $830 billion, and which STIR strategists expect will shoot up above $1 trillion in today’s final for 2023 reverse repo operation as a whopping $300+ billion in short-term liquidity in pulled from markets in just days.”


9:30 am (short session)

SPX futures attempted a new high by briefly reaching 4795.30, but fell back to a flat position.  The cash market high has been 4793.30 thus far.  The rally formation is complete, or nearly so.  Today may remain flat on weak volume as the book for 2023 is closed for many.  The rising trendline and the 1987 trendline bot reside at 4750.00.  An aggressive sell signal lies beneath them.  The Cycle Top resides at 4732.30 which may confirm the sell signal.

Today’s options chain shows 4780.00 is hotly contested and offers the Max Pain.  Long gamma starts at 4800.00 while short gamma may begin at 4775.00.

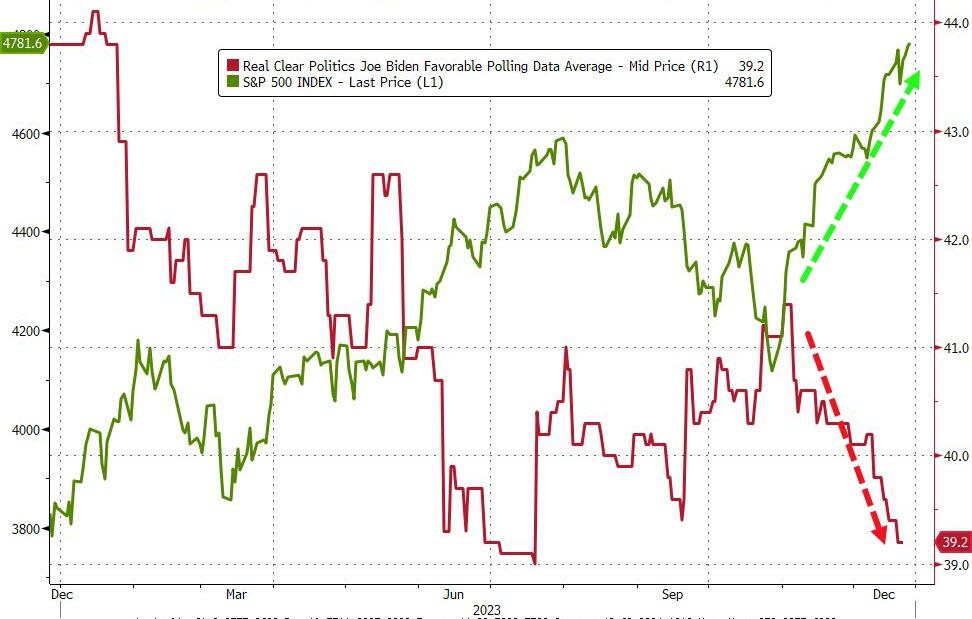
ZeroHedge reports, “US futures once again flirted between gains and losses on the last trading day of the year, but with the all time high in the S&P just 0.3% away, it is virtually guaranteed that the script calls for a new record to close out 2023 because that’s how centrally-planned markets work. And who knows, maybe this time BIden’s approval rating will actually increase; after all that’s what all of this is about.”


VIX futures consolidated inside yesterday’s trading range, without the energy to break up or down.  However, it has completed its first positive hourly Cycle since the Master low on December 13.  The new Master Cycle may extend to mid-January with an upward bias.

Wednesday’s options chain shows Max Pain at 13.50.  An 11,000 call contract at 11.00 negates the potential short gamma.  Long gamma otherwise begins at 16.00 and extends to 30.00.


TNX opened higher this morning, putting more distance from its probable Master Cycle low on December 27th.  There are multiple indications that yields have stopped going lower.

ZeroHedge remarks, “It’s only appropriate that a year which saw 10Y rates soar above 5%, the most in 16 years, before sliding on fears of an imminent recession and/or Fed easing cycle, that the final coupon auction of the year was a dog with a capital D.

Yesterday’s far stronger than expected 5Y auction surprised many: not only was there no concession with yields tumbling all day, but there was no tangible reason for the burst in demand that lead to one of the strongest stop-throughs on record, besides perhaps a big squeeze overhang as shorts sought to cover in the year’s last trading hours. Well, moments ago we did get confirmation that yesterday’s strength was indeed technically-driven because the $40BN in 7Y paper that was just sold by the Treasury could be described by just one word: ugly.”


BKX continues to hover near its retracement high.  As noted, TNX is beginning to rise, indicating that liquidity may be drying up.  Should that be the case, a decline beneath the Head & Shoulders neckline may be imminent.

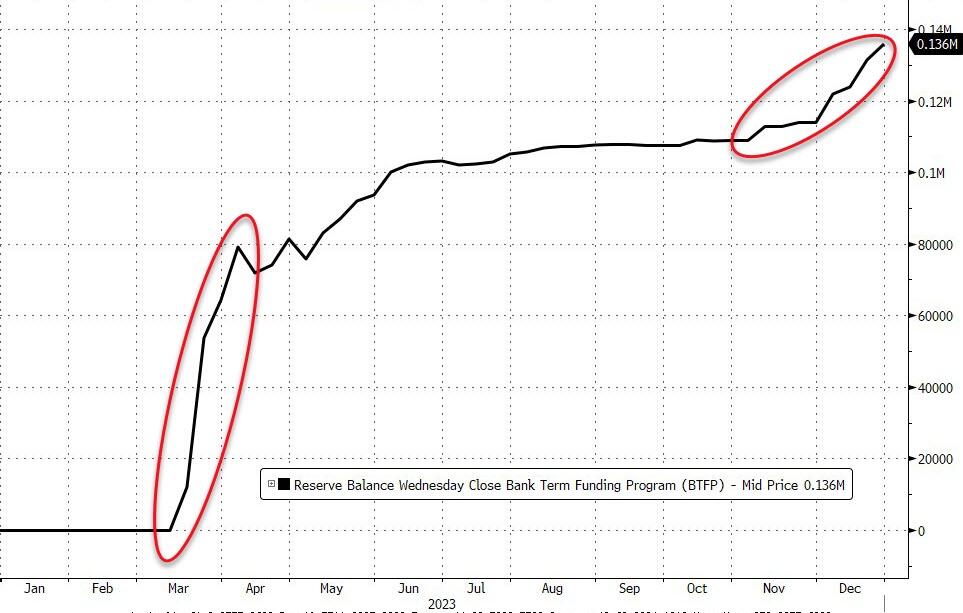
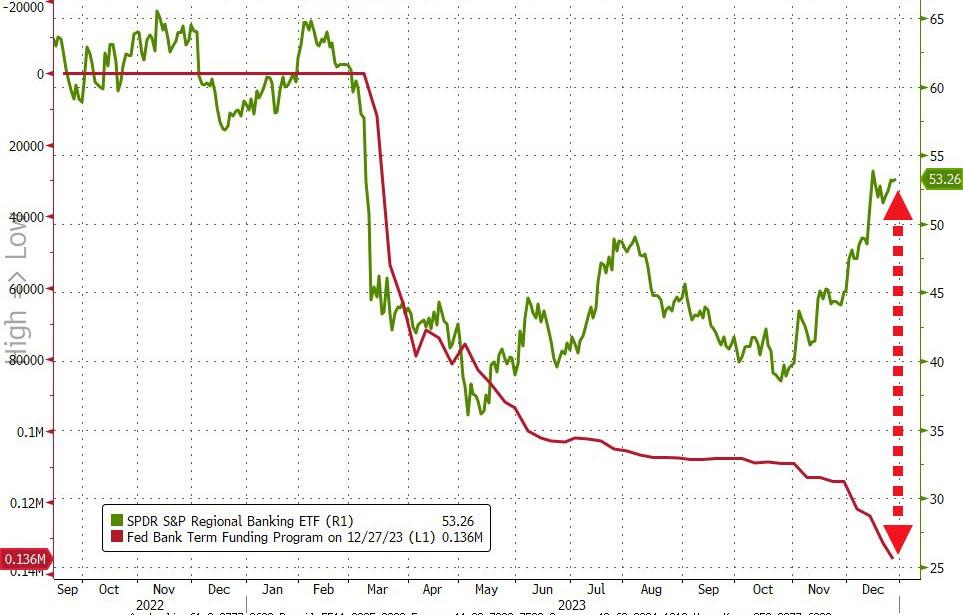
ZeroHedge notes, “Usage of The Fed’s bank bailout facility rose by another $4.5BN last week to a new record high of $136BN…

Source: Bloomberg

But Regional bank shares don’t care…”


The Ag Index made its Master Cycle low on December 21.  There is no visible buy signal except the Cycle low.  Overhead resistance is at 395.98, beyond which lies a confirmed buy signal.

ZeroHedge observes, “The war in Ukraine has transformed parts of the Black Sea into a conflict area. Commercial vessels transporting agricultural goods from the ‘breadbasket of Europe’ have been caught in the crossfire.

The latest maritime incident occurred on Wednesday when a Panama-flagged bulk carrier struck a mine in the Black Sea while sailing to a port on the Danube River to load grain, according to Reuters.

“A Panama-flagged civilian vessel was blown up on an enemy sea mine in the Black Sea … The vessel lost its course and control, and a fire broke out on the upper deck,” Ukraine’s southern military command said on Telegram.”

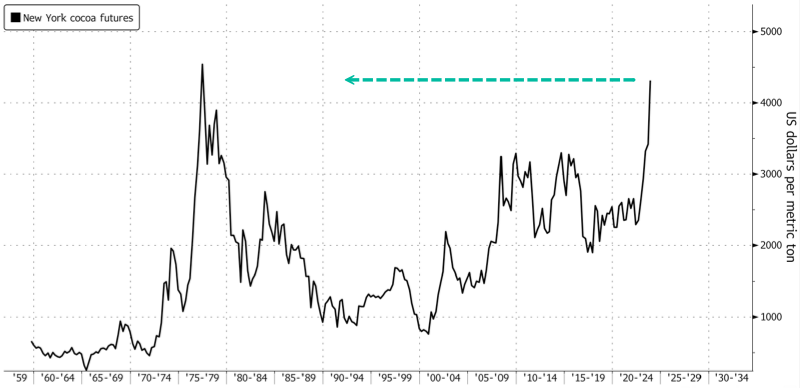
For those with a sweet tooth, ZeroHedge remarks, “Cocoa prices Wednesday hit $4,285 per ton in New York, the highest level since 1978, as the outlook of poor crop harvests across West Africa has been a major bullish factor pushing prices higher this year. There is also an increasing risk that El Nino-induced weather disturbances could cause the global cocoa market to sink into a deficit for the third year.”


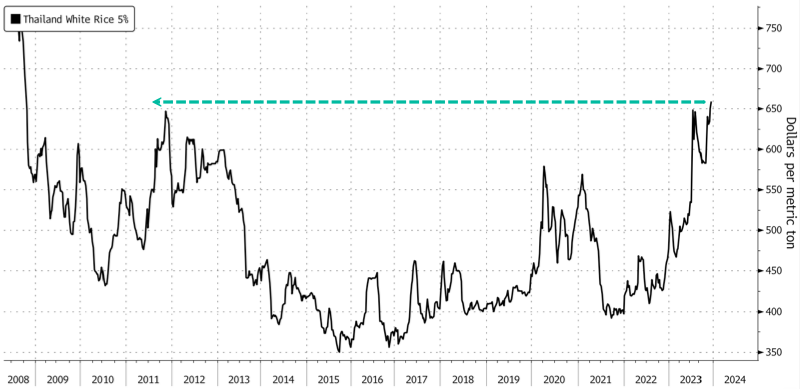
On the other side of the world, shortages lurk.  ZeroHedge reports, “On Wednesday, the Thai Rice Exporters Association revealed that the price of Thai white rice 5% broken, a key Asian benchmark, reached a new 15-year high. This surge is mainly attributed to increasing fears of a global shortage due to the damaging effects of the El Nino weather phenomenon on Asian farmlands and India’s recent decision to restrict certain rice exports.

Thai white rice 5% broken hit $659 a ton, the highest level since October 2008. Prices of the staple food that feeds billions of people worldwide are up over 50% since the start of 2022. ”


Posted in Published | 5 Comments