June 7, 2023

9:42 am

The Ag Index was repelled by its 50-day Moving Average at 442.50 on Monday and is seeking support at its Cycle Bottom at 427.46.  It may probe lower, to the bottom trading channel trendline near 415.00 in the next few days in a very complex retracement.  However, the placing of the Master Cycle low (currently at May 31) may be resolved.  I had breakfast with a soybean farmer who mentioned that only half of his seeds had sprouted due to dry weather.

ZeroHedge notes, “Farmers in Corn Belt states have been very concerned about their crops this spring as drought expands across the Heartland.

The latest weekly report from the US Department of Agriculture shows the US corn crop deteriorated by the most in nearly three years as drought conditions worsened in the Midwest.

About 64% of the nation’s corn crop was rated good-to-excellent in the weekly report, a five percentage-point plunge that was the most significant decline since August 2020. The drop was more than double of any analysts surveyed by Bloomberg.”

TheEpochTmes reports, “The Irish government is facing a backlash after reports broke of a proposal to kill off as many as 200,000 cows over the next three years in an effort to meet the country’s emissions reduction goals.

Last week, the Irish Independent reported on a government document describing plans for a potential cull of up to 65,000 dairy cows per year for the next three years. The paper reportedly obtained the documents from Ireland’s Department of Agriculture through a freedom of information request. In all, killing off 200,000 cows would wipe out about 10 percent of Ireland’s dairy cow population.”


9:31 am

BKX continues its retracement rally with a target at 85.95 by early next week.  The last probe may be met with a burst of strength through the weekend to finish its Master Cycle.  Be aware that the reversal may come quickly and savagely as rising interest rates break out.


8:05 am

Good Morning!

NDX futures continue to consolidate beneath Monday’s high.  Today completes an 18.5-month Cycle from the high on November 22, 2021.  NDX is currently in throw-over above its Ending Diagonal formation.  An aggressive sell signal may be issued beneath the Cycle Top support at 13988.09.  Confirmation of the sell signal may come at the conjunction of the lower Ending Diagonal trendline and the August high trendline near 13750.00.

Today’s op-ex shows Maximum pain for options investors at 14550.00.  Long gamma begins at 14600.00, while short gamma starts at 14525.00.

ZeroHedge comments, “On Friday, following the blowout jobs report, we observed a remarkable reversal in the surging – until now – tech/small caps ratio (represented in this case by QQQ/RTY), and asked if the blowout in tech names (at the expense of small cap) was finally over, and if it was small caps’ turn to shine.

The answer, just two days later: a resounding yes.”


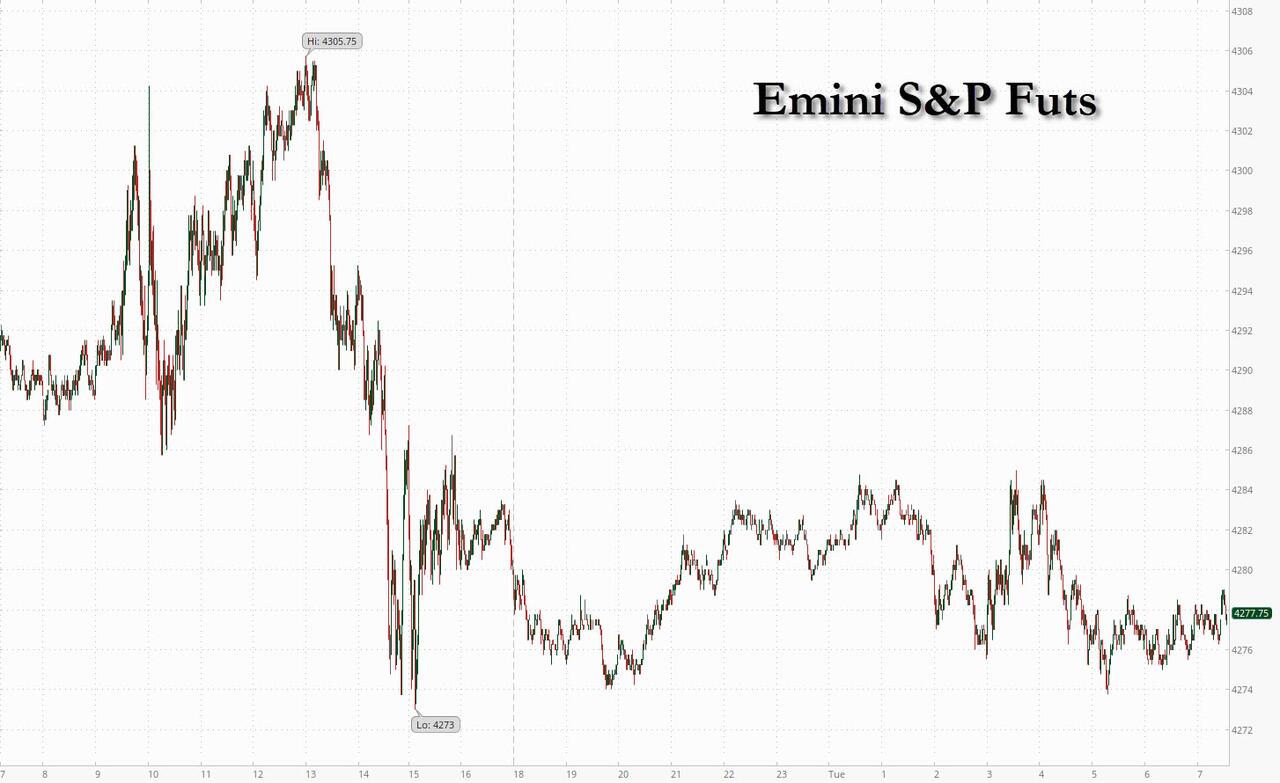
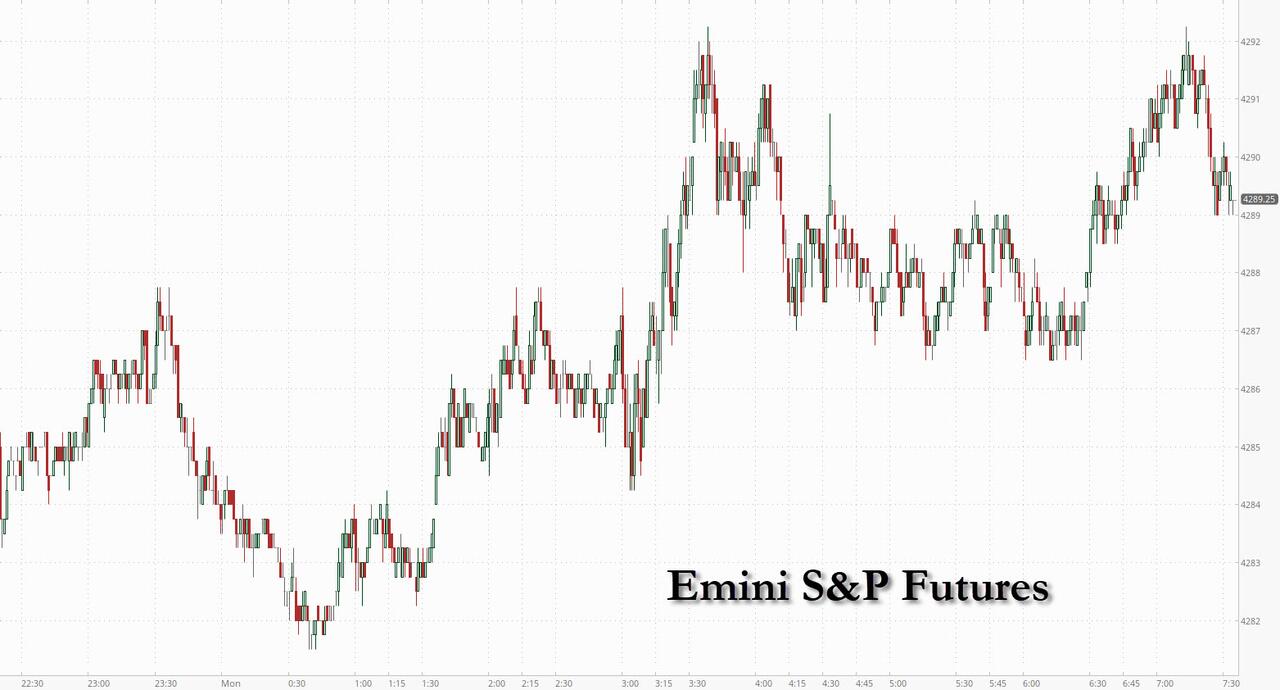
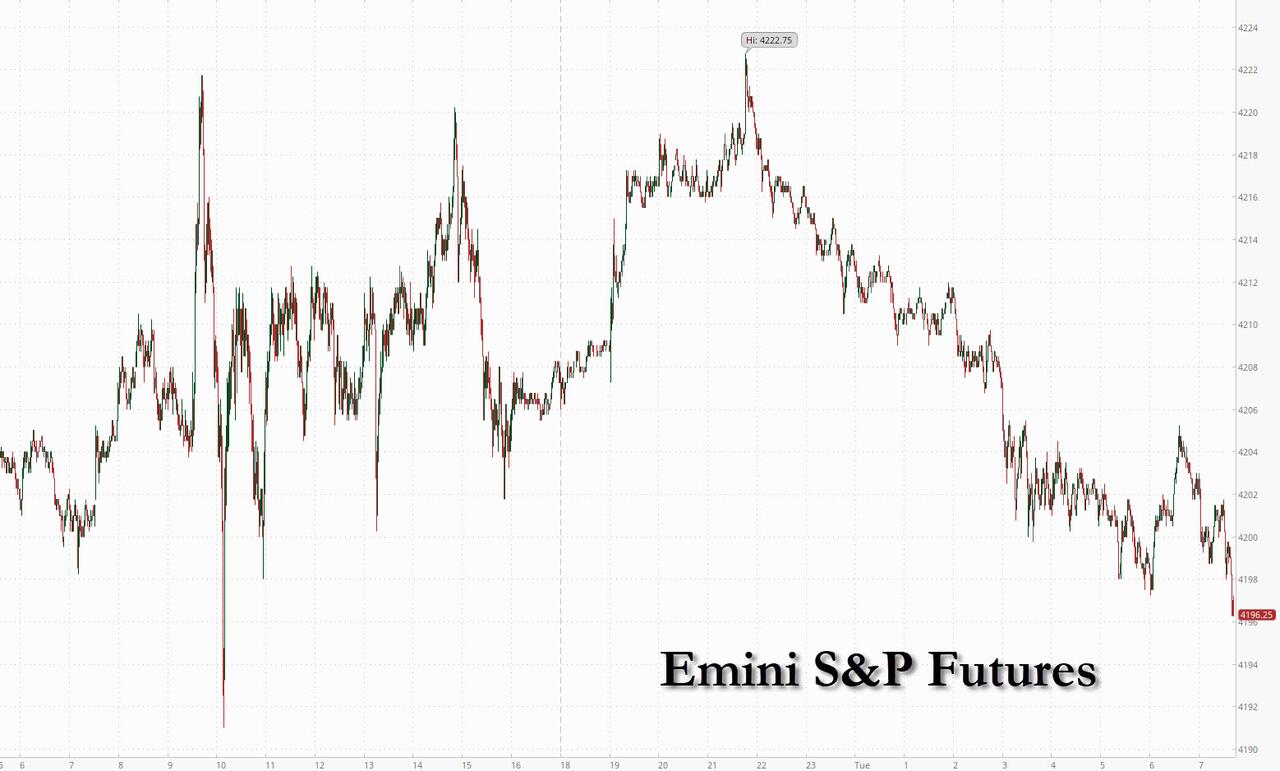
SPX futures are also consolidating in a narrow 15-point range beneath the Monday peak.  The 17.2 month Cycle meets its numerical apex on Friday, but Cycle turns may be influenced by the DJIA or the NDX which both peak today.  The fact is, Monday’s peak may already fulfill the Cycle requirements which may be confirmed by the appropriate reversal.  SPX may already be considered to have an aggressive sell signal by having reversed beneath the Cycle Top resistance at 4288.50.  An additional aggressive sell signal comes beneath the upper Ending Diagonal trendline at 4250.00.  A confirmed sell signal comes beneath the lower Ending Diagonal trendline flanked by the intermediate-term support at 4154.83 and the 50-day Moving Average at 4127.71.

Today’s op-ex shows Max Pain at 4275.00.  Long gamma begins at 4300.00 while short gamma starts at 4150.00.

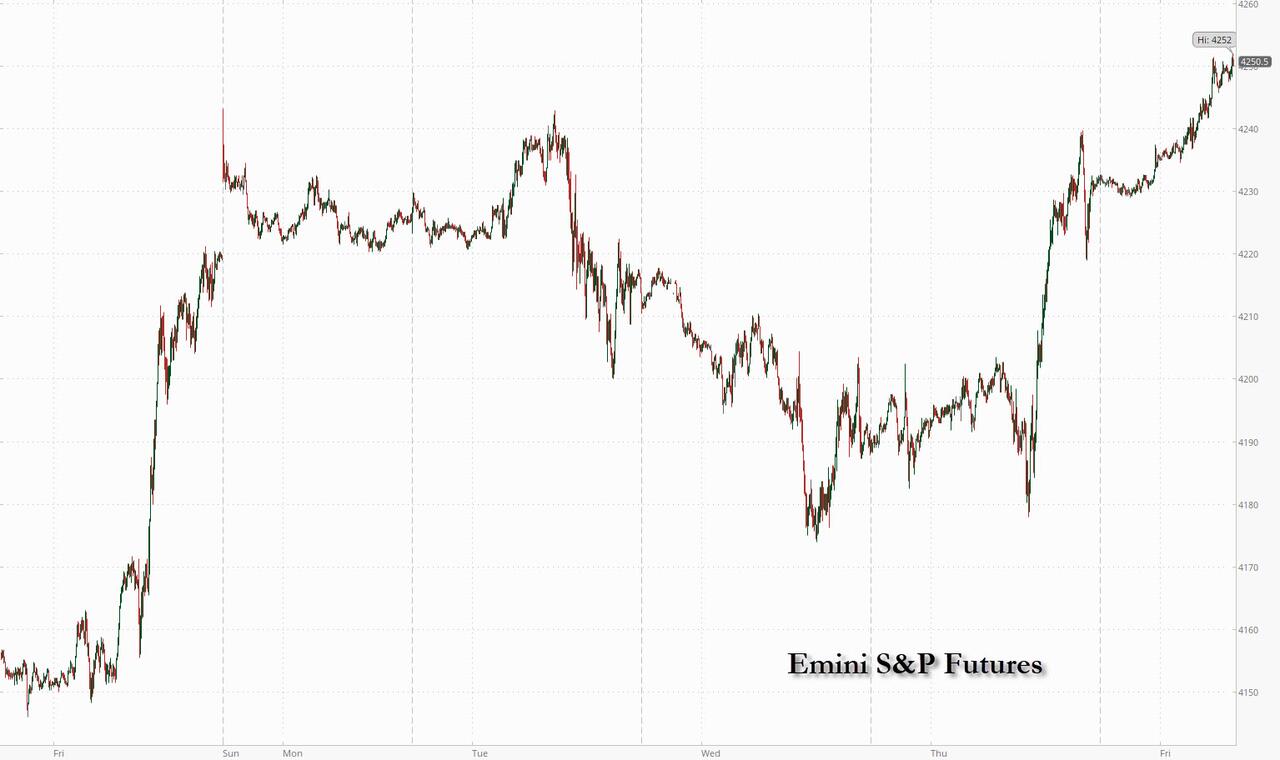
ZeroHedge reports,” Futs are starting flat for a second consecutive day, having reversed earlier losses, after China reported a bigger-than-expected drop in exports and OECD warned of a weak global economic recovery. Shares are trying to build on Tuesday’s gains as a rally in megacap stocks that had propelled the S&P 500 to the edge of a bull market continued to fizzle. As of 8:00 am ET, S&P futures were modestly in the green at 4295 while Nasdaq 100 futs were up 0.2%The Bloomberg Dollar Spot Index traded near the day’s lows, boosting most Group-of-10 currencies. Treasury yields were little changed amid listless trading global bond markets. Oil and gold were flat, while Bitcoin retreats a day after climbing more than 5%. Today’s macro data includes mtge applications, trade balance, and consumer credit. Ultimately, the macro data prints are light for the balance of the week.”


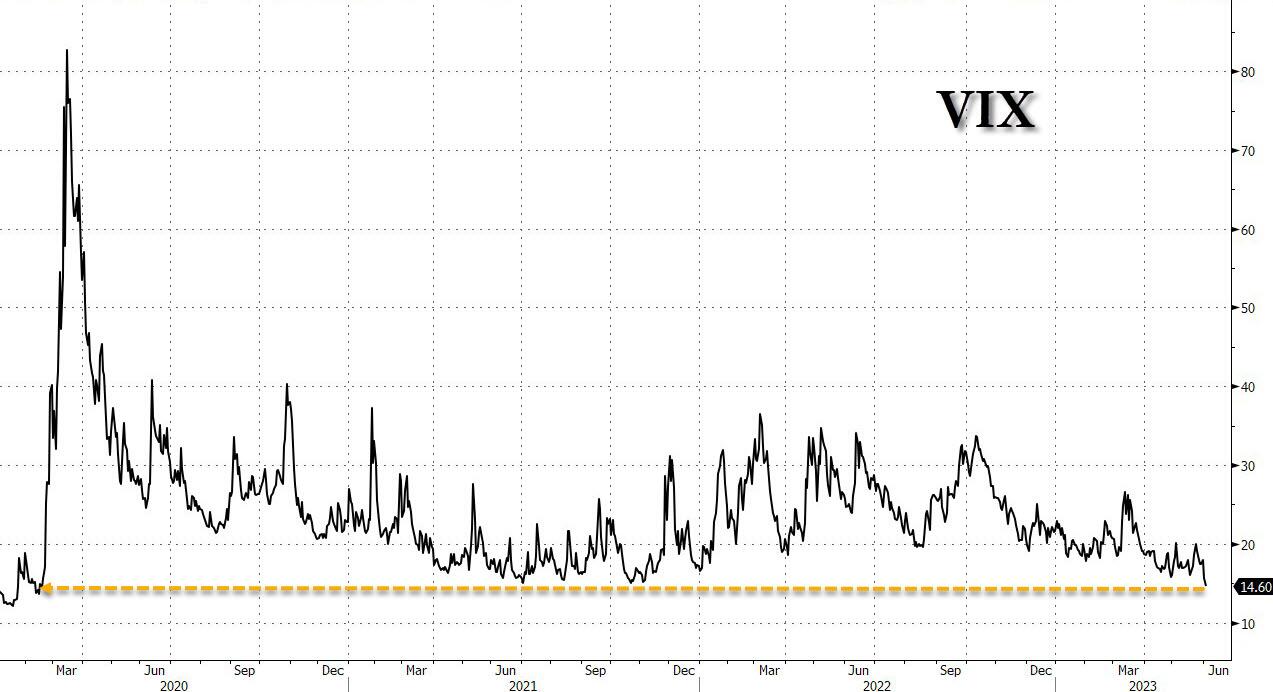
9:40 am:  Note that VIX made a new low at 13.90 this morning on day 271.

VIX futures rose from their Master Cycle low at 13.95 yesterday (day 270).  This low has not been seen since January 2020 and marks a 40-month Cycle low.  This bearish extension in the VIX may have been the product of the flood of liquidity injected by the Fed to save the banks.  The effort to refill the depleted treasury may reverse this phenomenon.

Today’s op-ex shows 16.00 as the most hotly disputed strike and Max Pain, as well.  There is not short gamma.  Long gamma starts at 17.00  and potentially runs to 47.50.


TNX may be rising from its mid-Cycle support at 36.81 to continue its journey to the Cycle Top at 41.20.  Trending strength may get a boost this weekend and continue through the end of the month.


USD futures appear to be consolidating near yesterday’;s low.  The short-term direction appears to be lower, with a potential Master Cycle low in the next week.


Posted in Published | 3 Comments

June 6, 2023

7:45 am

Good Morning!

It’s time to review the bluest of the blue chips as a contrast my previous reporting.  While the NDX is making new retracement highs, the DJIA may have already put in the high in December and is finishing a secondary retracement this week.  There may be a final probe to 34300.00, which has been the high since January.  In other words, all of the major indices are scheduled to reverse down tis week.


NDX futures are trading in a flat range this morning in a consolidation just beneath yesterday’s high.  It has accomplished its Fibonacci target at a 61.8% of the 2022 decline at 14324.71.  The turn date target for NDX is tomorrow.  However, it may have already put in the high.

In today’s op-ex, Maximum investor Pain in options is at 14560.00.  Long gamma begins at 14650.00 while short gamma starts at 14500.00.  The bulls may be losing their risk off impulse.

ZeroHedge observes, “Overbought

NASDAQ and NYFANG at very overbought levels, but people tend to forget we can stay at overbought levels for longer than most can “endure”.

Source: Refinitiv

Apple – zoom out…

…and you will see there is no trend in the world’s number one stock. Getting excited about break outs, both ways, has been an expensive strategy since late 2021, vision pro or not.”


SPX futures are also consolidating beneath yesterday’s high.  The SPX 17.2-month Cycle ends on Friday, but may reverse at any time.  It is fascinating to see the different Cycles of the three major indices all back on the same page…

Today’s op-ex shows Max Pain at 4265.00.  Long gamma may start at 4285.00, while short gamma may begin at 4260.00.  Not a lot of conviction on either side…

ZeroHedge reports, “US equity futures are flat, bond yields are lower, the dollar is higher, and commodities (ex-Ags) are weaker as the excitement over the Saudi 1mmb/d production cut fizzles and as hedge fund shorts once again take the upper hand. Ags are higher led by wheat on headlines from Ukraine, where a dam was damaged in an explosion.

As of 7:45am ET, S&P futures were unchanged with the Nasdaq fractionally in the red as well, with Apple down 0.4% in premarket trading on concern the ludicrous price ($3500) of its much-anticipated mixed-reality headset will crater demand. European semiconductor firms slid after Taiwan Semiconductor — the main chipmaker to Apple — said capital spending will be at the lower end of its guidance range. Overall, there appears to be a mild risk-off tone pre-market,  With the S&P 500 on the edge of a new bull market, there’s a sense among traders that markets have run up too fast on the hype for artificial intelligence. The balance of the week is light on macro data points so markets may trade in a tight range into CPI/Fed next week.”


VIX futures are flat, but may show trending strength as early as today.  That suggests the trendline and the 50-day Moving Average at 17.82 may be challenged.  An aggressive buy signal may be warranted due to the change in Cycles.  Confirmation may occur above the 50-day.

In tomorrow’s op-ex, the 16.00 strike is hotly contested.  However, there is no short gamma follow-through.  On the other hand, long gamma starts at 17.00 and runs hot to 47.50.

ZeroHedge remarks, “As discussed yesterday, the VIX may be getting close to a bottom after hitting the lowest level in more than three years.

As Bloomberg’s Akshay Chinchalkar writes, the VIX collapsed by ~19% last week, the largest drop this year, as the debt-ceiling standoff was resolved and the mixed payrolls data for May diluted the odds of a rate hike this month.

The retreat means the VIX is more than 34% below its widely-followed 200-DMA. Such a significant divergence has typically marked a trough.”


TNX tested its mid-Cycle support at 36.79 this morning and may now be moving higher.  It has just reached a midpoint in the current Master Cycle and has another month to go.  The rest of the week may be a consolidation, according to the Cycles Model, with trending strength returning over the weekend.

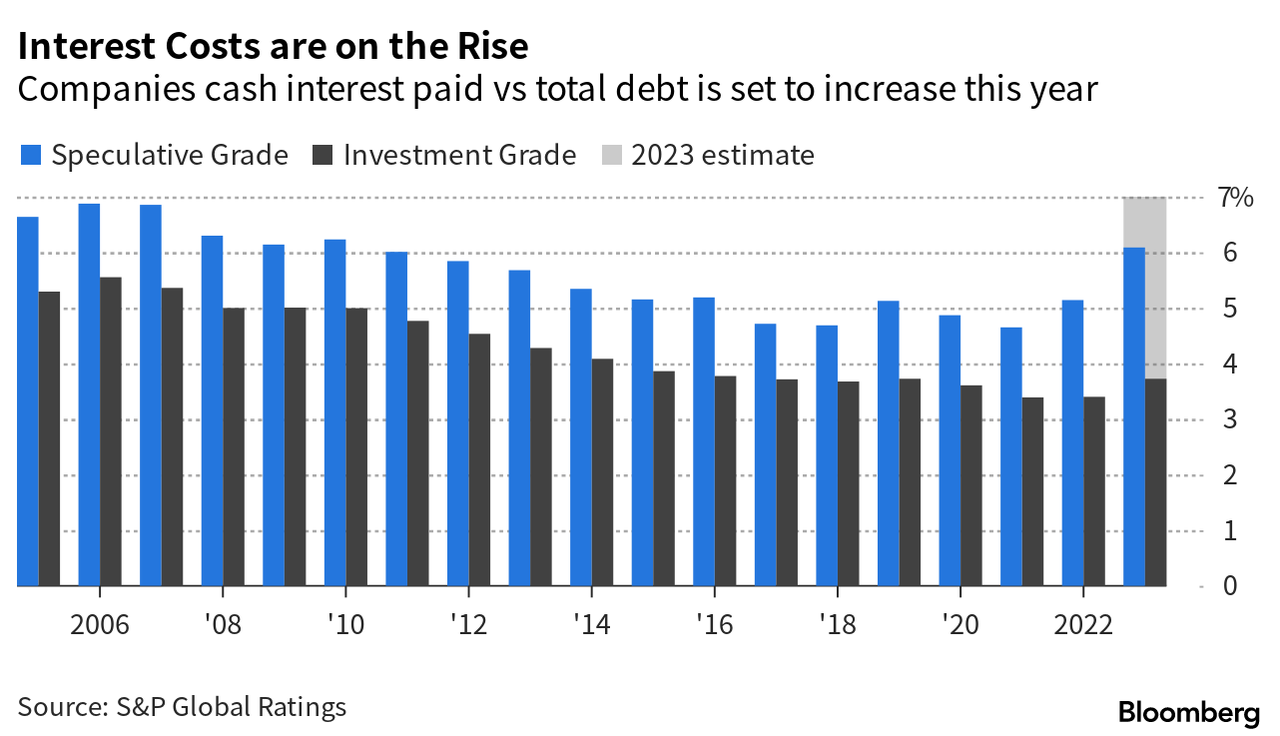
ZeroHedge observes, “For corporations with junk credit ratings, the cost of debt servicing has skyrocketed, reaching levels not seen in over a decade. This surge can be attributed to the Federal Reserve’s rate-raising campaign. And it might force some companies to reevaluate capital structures.

Bloomberg cited an S&P Global Ratings report that outlined junk-rated firms are paying an effective rate of 6.1% on debt, up from 5.1% last year. The 6.1% rate is the highest interest on debt since 2010.


Posted in Published | 20 Comments

June 5, 2023

8:00 am

Good Morning!

A weekly chart serves us best at this juncture.  The reason is that NDX just rose to the 61.8% Fibonacci retracements level (14324.71) of the 2022 decline on May 26.  To that extent, it has met a common retracement level for a Primary Wave [2].  In addition, on Wednesday it will have complete 18.5 months since its November 22, 2021 high on Wednesday.

NDX futures are lower this morning, but within Friday’s trading range.  Having met its 61.8% retracement level, it may simply go higher until the Cycle is complete later this week.  NDX is in throw-over, due to a very small number of AI “generals.”

ZeroHedge remarks, “Extremely narrow breadth has historically led to further index upside.

As discussed in my previous post, it is not inconceivable (but still unlikely) that the recent zeal for AI could avert a US recession.

Whether it does or not is really moot as an investor, what’s important is asset performance.

And on that basis, the AI rally is on more solid ground.

In short, narrow leadership often creates its own reality and ends up dragging the rest of the market along with it.

That’s may happen this time too.”


SPX futures are flat this morning.  The 17.2-month Cycle from January 4, 2022 may complete by Friday.  The 61.8% Fibonacci retracement level is at 4311.00.  A reversal from the cycle Top at 4280.00 may produce an aggressive sell signal.  Confirmation of a sell signal lies at Intermediate-term support at 4147.43 or the 50-day Moving Average at 4121.67.

In today’s op-ex, Maximum Pain for options investors is at 4265.00.  Short gamma may begin at 4260.00.  Long gamma may begin at 4285.00.

ZeroHedge reports, “Futures are flat with oil jumping after OPEC+ cut output by an extra 1mm bpd in a unilateral move by Saudi Arabia taking its production to the lowest level for several years.At 7:30am ET, S&P futures were flat, while Nasdaq futures were down 0.2% with some artificial-intelligence exposed stocks like Nvidia Corp. and C3.ai Inc. trading down. In contrast, Apple Inc. surpassed its previous closing record in premarket ahead of what’s expected to be its most significant product launch event in nearly a decade. Oil rose 2%, with oil giants such as Chevron and Exxon up in premarket trading. The Bloomberg dollar index is up as are 10Y yields now that the market’s attention turns to the $1+ trillion deluge in new debt issuance. Gold dropped, as did bitcoin after the crypto currency got its usual Asian session rugpull.”


VIX futures rose this morning after potentially making its Master Cycle low on Friday, on day 266.  The new Cycle low came through a rare and complex W-X-Y-Z extension adding a full month to the already massive Triangle formation, creating a 17.2-month Cycle.  VIX short players are ecstatic while commentators are viewing this as bullish for equities.

In Wednesday’s op-ex, Maximum Pain is at 16.00.  Short gamma is virtually non-exixtent, while long gamma begins at 17.00 and rises to 50.00.

ZeroHedge notes, “It turns out the bulls had every right to be Dancing in the Street as stocks posted a very strong week (even the Russell 2000 and Regional Banks participated). Friday’s jobs data seemed to put the nail in the coffin on rate hike fears. The market has decided, rightfully so, that we are almost done with rate hikes and unless we get disastrous inflation data, any future hikes will be small enough not to act as a headwind.”


TNX leaped above the mid-Cycle resistance at 36.77 this morning, on its way to the Cycle Top resistance at 41.23 in the next month.

ZeroHedge comments, “As the latest debt-ceiling drama winds down, Americans are varyingly exasperated, angered, anxious and maybe even a little bit entertained by the spectacle.

While their emotions vary, most citizens have something in common: They don’t realize they’re being misled about the actual depth of their government’s financial disorder. Despite all the talk of the federal government hitting a Congressionally-set $31.4 trillion debt limit, the truth is that DC’s actual liabilities are far higher than even that disturbing number.

Estimates by the relatively few scholars and organizations who venture to expose Washington’s charade vary, but they overwhelmingly place the federal government’s true total obligations at over $100 trillion. For example, Truth In Accounting’s latest tally puts Uncle Sam’s total IOUs at $156 trillion.”


USD futures rose to 104.35 this morning.  The Cycles Model suggests another week of rally prior to a retracement.  The immediate target appears to be the mid-Cycle resistance at 105.31.  While USD may overshoot its target, it may end up back beneath it in the next few weeks.


WTIC futures may bise to test the 50-day Moving Average at 74.54 this morning, adjacent tot he trendline.  Should it succeed in overcoming that resistance, the trend may change to the positive.  However, should it be repelled, the decline may resume for as long as seven more weeks.  Thus far in the current Cycle, the daily Cycle bottom at 67.06 is holding.  However, a resumption of the decline may send Crude Oil to a possible low of 54.00.


Gold futures are lower this morning, caught in a corrective pattern that may end back near the 50-day Moving Average at 1999.70 in the next week or so.  The Cycles Model then calls for the decline to resume with the next Master Cycle going to the end of July.

ZeroHedge observes, “Most politicians have used the “Ukraine invasion card” to justify the massive inflationary burst in 2021-2023.

It does not matter if inflation was already elevated prior to the war.

Supply chain disruptions, demand recovery, wage growth… Many excuses were used to justify inflation, except the only one that can make aggregate prices rise in unison, which is the creation of more units of currency well above demand.

Inflationists will blame inflation on anything and everything except the only thing that makes all prices, which are measured in monetary units, rise at the same: Money supply growth rising faster than real economic output.”


Posted in Published | 16 Comments

June 2, 2023

7:50 am

Good Morning!

The Cycles are providing more answers now, as the rally progresses.  The end of next week will give the initial bearish Cycle and its retracement exactly 17.2 months.  It appears that there may a few more days to complete the pattern, followed by a potential waterfall event.  Initially, the Primary Cycle appeared complete on February 2.  The pattern that followed did not reveal  its true intent until it broke through the February 2 high.

SPX futures are higher this morning, and may rise to the Cycle Top resistance at 4274.54.

ZeroHedge reports, “US Futures extended yesterday’s rally after the Senate passed a bill late on Thursday to raise the debt ceiling and prevent a US default, with risk-on sentiment getting a boost following the sharpest rally in Chinese stocks for three months amid Bloomberg reports that China is mulling a new stimulus package to support the property market after existing policies failed to sustain a rebound in the ailing sector.

At 7:45am, S&P futures rose 0.5% to 4249, while the Nasdaq rose by 0.6% and was set for a sixth straight weekly advance. Europe’s Stoxx Europe 600 index followed Asian benchmarks higher, with luxury-goods makers LVMH and Richemont among the leading gainers after the China stimulus report. Treasury yields were little changed, diverging from higher rates in Europe and the UK. Oil and bitcoin both gained more than 1%, while gold was little changed after three days of gains.”


VIX futures hit a morning low at 15.07, marking a potential Master Cycle low on day 266.  Intermediate Wave (E) has become more complex than expected, but no rules were violated.


Posted in Published | 11 Comments

May 26, 2023

7:45 am

Good Morning!

My internet provider was down most of the day yesterday.  They gave no reason for the outage, except the recorded messages implied that it happened in multiple locations across the country.  I must also report that I will be out of my office all of next week.  The chances of doing a remote blog are slim.

NDX futures have reached a new high at 14005.60 this morning.  Today is day 283 of the NDX Master Cycle.  The number of stocks carrying the market is now just one.  The NDX Hi-Lo Index closed at -119.00.

The Cycles Model shows no outstanding events until the end of next week.  From that I would infer a flat market or a mild decline for the next week.  The Memorial weekend is traditionally neutral-to-positive.  However, things change dramatically in the first full week of June.

Today’s op-ex shows Maximum Pain for investors at 13775.00.  Long gamma begins at 13800.00.  Short gamma begins at 13600.00.

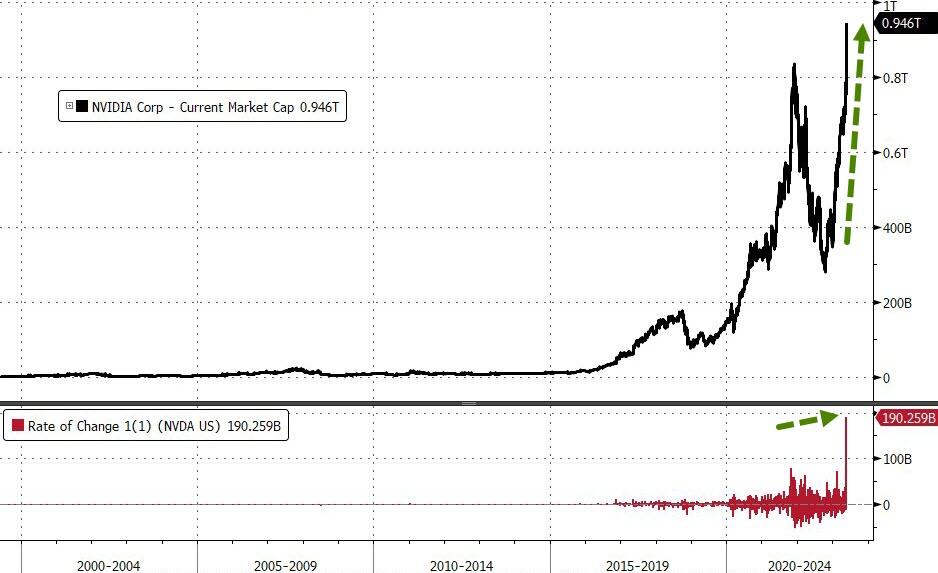
ZeroHedge remarks, “Yes there was macro data: GDP second look improved, jobless claims shitshow due to MS fraud revisions, pending home sales disappointed, Kansas City Fed better than expected; and some Fed Speak (Boston’s Collins sees a ‘pause’ – like everyone else), but really this was all about Jensen Huang (who’s personal; wealth jumped over $8 billion today).

From the open, the day was all about one stock – NVDA, soaring 25% or so and adding just under $200 billion in market cap – that is 2 Intels! – and from the Oct 2022 lows, NVDA has added $665 billion in market cap…

Source: Bloomberg

That is the largest single-day market cap gain for any stock in US equity market history…”

ZeroHedge notes this morning, “Boom

The NDX/NDXE ratio attacking all time highs. It is all about a(i) few great ones.

Source: Refinitiv

Not your normal short squeeze

Nomura’s McElligott weighs in: “…this is “Long Buyers” of the Stock chasing this AI theme; Yet it will likely be a MegaCap Tech “Spot Up, Vol Up” today on UPSIDE breakout and grabbing into what is relatively cheap Gamma, as the real “short squeeze” here will likely be from frequently mentioned Overwriters in MegaCap single-name and broad Nasdaq / QQQ OTM Upside Calls seen through 2023, which now AGAIN risk going “short strikes” and getting forcibly covered which will further bid “Upside”.”


SPX futures rose to an overnight high of 4160.50, suggesting yesterday’s after noon high may be the end of the retracement.    The Ending Diagonal trendline is at 4100.00, giving a confirmed sell signal.  Further confirmation awaits at the 50-day Moving Average at 4087.89.  The NYSE Hi-Lo Inces closed at -111.00 yesterday and is on a sell signal.

Today’s op-ex shows Max Pain at 4170.00.  Long gamma starts at 4190.00, while short gamma begins at 4150.00.

ZeroHedge reports, “US equity futures are higher across the board, amid speculation that a debt deal is taking shape and may be announced as soon as today (whether or not a 0.2% spending cut “deal” is something to be proud about is a different matter) and also thanks to optimism around Nvidia and AI prospects. S&P futures are 0.2% higher, rising to 4,169 and undoing the drop from the previous two days, while Nasdaq futures are up 0.4% amid continued AI-bubble euphoria. Treasury yields are falling, most markedly at the short end, on debt ceiling optimism, while a measure of the dollar is weakening. Commodities are mostly higher led by base metals. Oil prices are set for a weekly gain, climbing higher today. Gold prices are edging higher but still set for their third weekly decline.


VIX futures may be testing the 50-day Moving Average at 18.63.   The Cycles Model suggests a peak in the VIX by mid-June with a possible higher peak at the end of the month.  This activity seems to be related to the debt ceiling, but there may be something else afoot.

Next Wednesday’s op-ex shows Max Pain at 19.00.  Short gamma fizzles out at 16.00, while long gamma remains strong to 30.00.  Not much to see, yet.


TNX continued its relentless climb higher this morning.   The Cycles Model suggests a probable (minor) Trading Cycle low at the end of next week, so it may not be advisable to take any further action until the dust settles.

ZeroHedge notes, “The market’s recent re-pricing of the Federal Reserve’s rate trajectory is nothing short of dramatic. Investors will find it challenging to price Friday’s slate of data going into the long weekend while being fully mindful of the risks centered in Washington.

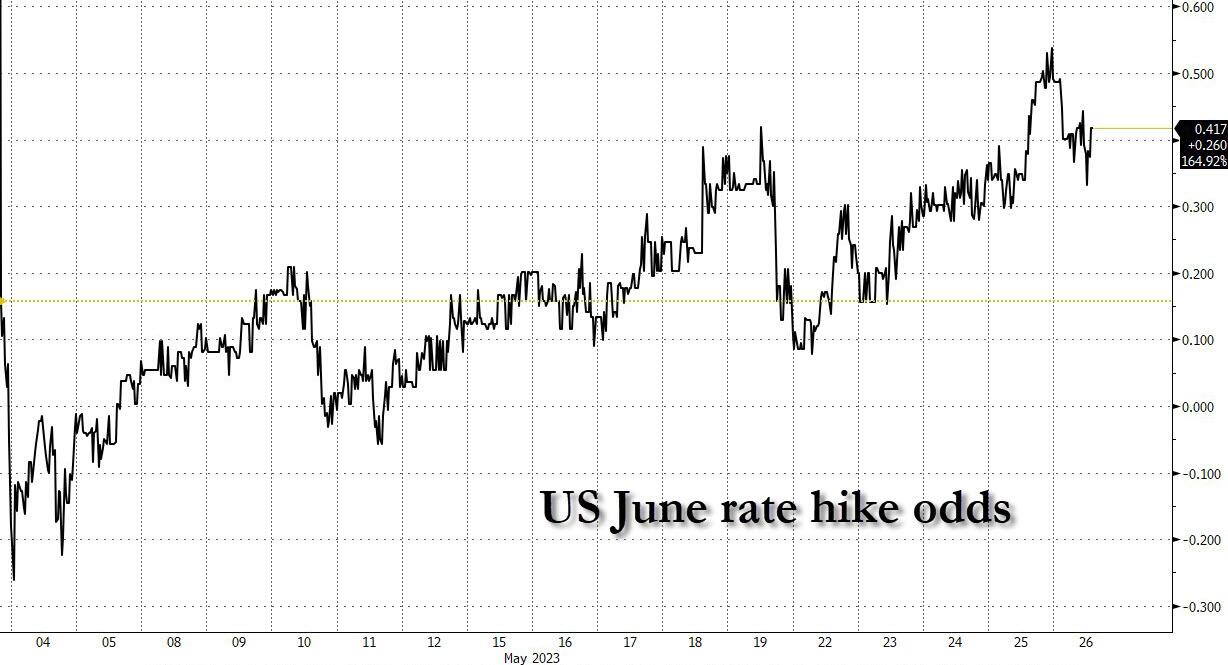
Just after the Fed raised rates earlier this month, the markets were assigning a more-than-50% chance of a rate cut in July and fully factoring in a reduction by September. After some hawkish jawboning from James Bullard as well as Neel Kashkari and Thursday’s better-than-forecast 1Q GDP numbers, interest-rate traders see the Fed raising rates yet again in July. Talk about the markets turning on a dime.

Will Chair Jerome Powell, who all but signaled that the Fed would stay on hold when it meets next month, be persuaded otherwise if today’s PCE data turn out to higher than the markets estimate? And will consumers’ expectations of inflation in the University of Michigan survey jump yet again, putting paid to the school of thought that inflation is oh-so-2022?


USD futures are lower this morning, although the Cycles Model does not confirm that it may last.  Additional strength may be coming online over the weekend followed by another boost in trending strength over the next two weeks.  A cross above the 200-day Moving Average may silence the dollar bears.

ZeroHedge opines, “Debt-ceiling worries are driving the dollar up for now, but real yields, the fiscal deficit and structural overvaluation favor the medium-term downtrend remaining intact.

All of the recent move higher in nominal yields (discussed here) has been driven by real yields. Inflation, erroneously, is seen as yesterday’s problem, with breakevens remaining near the lower end of their two-year range.

Higher real yields might be expected to be good for the dollar. The currency has indeed risen in recent weeks, but this is more to do with safe-haven demand in the event the debt ceiling becomes binding.”


GOLD futures are higher, to 1957.05 and may go as high as the 50-day Moving Average at 1996.88 in a short burst of strength.  However, the decline may resume shortly with an anticipated low by mid-June.

Investing.com comments, “Gold is finding support in the $1950 area on this week’s declines but is not finding support from buyers on the rally above $1985.

Gold is stuck in a range

Gold is stuck in a range

Support for this trading range is provided by the area of the late January price peak, which has also acted as a pivot point more than once in this growth cycle, halting the rally. The ability to hold above this previously strong resistance for an extended period is an important signal for speculators.


Posted in Published | 1 Comment

May 25, 2023

2:30 pm

Good Afternoon!

SPX may have completed its first hourly Cycle from its high.  If so, we may expect to see the decline begin from here.  More on Friday.


Posted in Published | 1 Comment

May 24, 2023

8:15 am

Good Morning!

NDX futures hit a new morning low at 13614.80 after breaking through the (August peak) trendline support at 13720.91.  It is currently challenging the Cycle Top support at 13616.00 and on an aggressive sell signal.  The throw-over bottom is at 13600.00, confirming the sell.  The NDX Hi-Lo Index closed at -1.00 and may be poised to give further confirmation beneath 0.00.

Today’s op-ex shows Maximum Pain for options investors at 13725.00.  Long gamma begins at 13750.00.  Short gamma may begin at 13700.00, with a growing number of contracts reaching 13500.00.

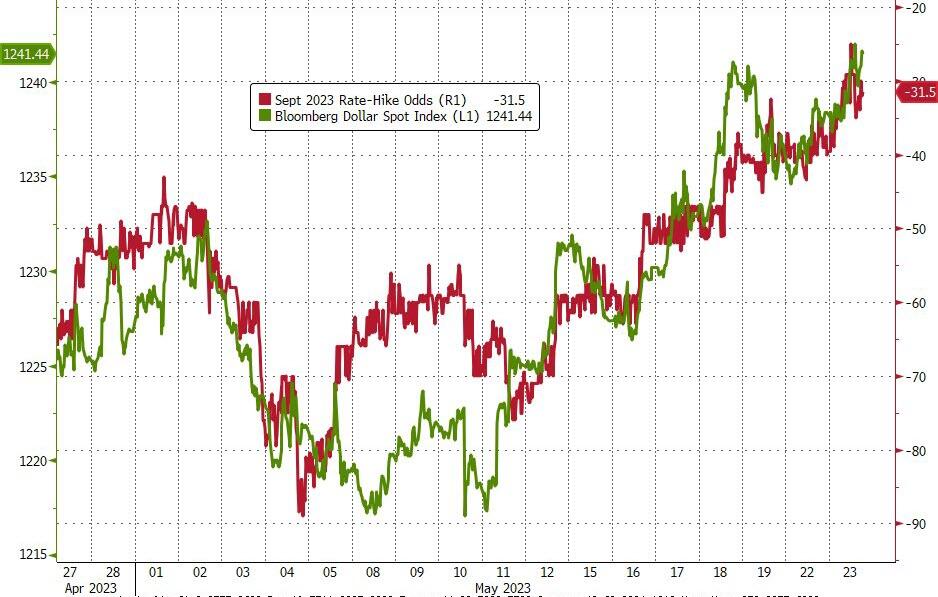
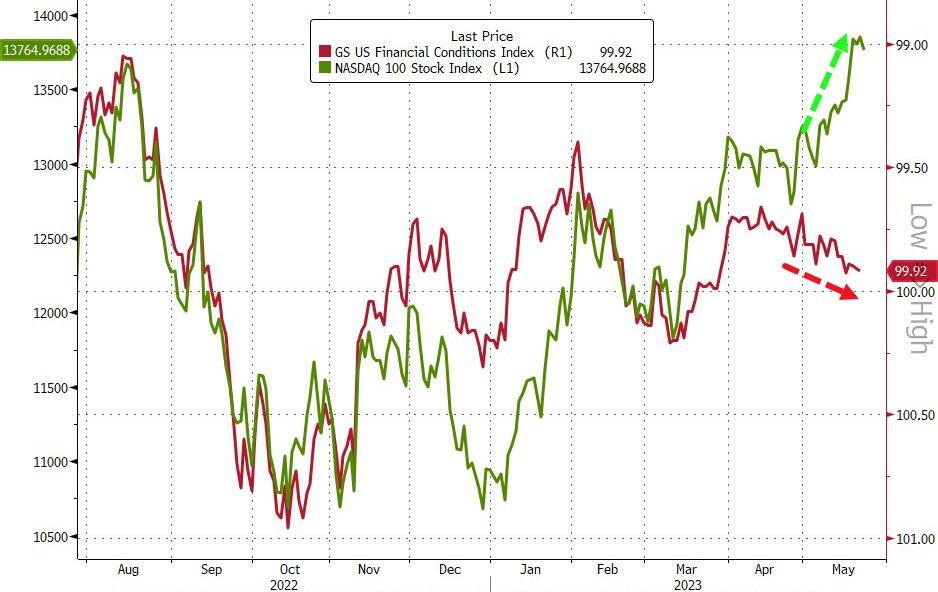
ZeroHedge observes, “The last few weeks have seen the market’s expectations for Fed’s rate trajectory shift significantly more hawkish (as the weights of the bi-modal probability distribution shift from ‘recession-emergency rate cut’ to ‘high for longer’) and that has dragged the dollar higher with it (on almost a tick-for-tick basis)…

Source: Bloomberg

The stronger dollar and higher rates have significantly tightened financial conditions in May, but stocks just don’t care…”


SPX futures declined to 4128.70, challenging the Intermediate-term support at 4130.65.  A further decline gives an aggressive sell signal which may be confirmed the the Ending Diagonal trendline at 4100.00.  The 50-day Moving Average lies just beneath it at 4077.33, giving a final confirmation of the sell signal.  The Cycles Model suggests a sideways-to-moderate decline through the next week, due to the Memorial Day holiday, which is seasonally positive.  However, the decline intensifies the first full week of June and continues at a strong (panic) phase through the end of the month.The NYSE Hi-Lo Index closed at -5.00 yesterday with the decline being confirmed beneath -32.00.

Today’s options expiration shows Maximum Pain for investors at 4160.00.  Long gamma starts at 4175.00 while short gamma begins at 4150.00.

ZeroHedge reports, “US equity futures drift drift lower for the second day following a deluge of bad news across global markets driving European stocks to their biggest drop in two months, pushing copper below $8,000 and snuffing out this year’s gains in China equities. As of 730am ET, S&P futures were down 0.4% to 4,143  following Tuesday’s 1.1% drop with Nasdaq futures sliding the same amount. Treasury yields are flat trading around 3.67%, the USD is slightly stronger, and bitcoin got the usual Asian session trapdoor as gold rose. Commodities are mixed: energy rallied (WTI + 2.1%) while metals are falling on concerns about China’s fading recovery. Yesterday, we saw de-risking in crowding stocks with Momentum Winners and MegaCap Tech being the biggest laggards. On debt ceiling negotiation, two parties have not come to an agreement. Today, we will receive the FOMC Minutes at 2pm ET; AI-leader Nviidia reports after the close.”


VIX futures hit a new high at 19.74 this morning after challenging the 50-day Moving Average yesterday.  It is on a buy signal with plenty of elevation ahead of it.   The primary target over the next few months may be the 2020 high at 85.47.  The Cycles Model suggests a peak as early as mid-June, with a probable higher peak at the end of June.

Today’s expiring options show Max Pain at 17.00 with virtually no short gamma to report.  Long gamma extends to 40.00.

Despite the buy signal, some analysts believe the low VIX is bullish.

RealInvestmentAdvice offers this comment, “Last week, the S&P 500 volatility index (VIX) fell below 16 for the first time since November 2021. The VIX index uses options prices to imply how much future volatility the market expects. Typically, in upward-trending markets, the VIX trends below 20. Conversely, in bearish markets or shorter drawdowns, it lingers in the 20s but can peak above 50. Lower volatility, like the current reading of 16, implies the market is very comfortable with potential risks.”


TNX may pull back to the mid-Cycle support at 36.58 this morning and may even extend the pullback as far as the 200-day Moving Average at 36.04.  However, once accomplished, it may offer a burst of energy higher.  The Cycles Model maintains that yields may climb until early July.

ZeroHedge Notes, “Two weeks ago we published a lengthy report looking at the hypothetical consequences of a US default – including “Clearinghouse Collapse And Shockwave Of Catastrophic Treasury Margin Calls” – which again are purely hypothetical: as we first said last week…

… and as Stifel’s Brian Gardner confirmed just a few days later…

Federal revenues cover only 75 percent of outlays so at some point, without an increase in the debt limit, Treasury will be unable to pay all of the government’s bills.  It seems clear that Treasury will prioritize the payment of principal and interest on U.S. Treasuries, so the chances of a default on Treasuries is remote.  Also, it is unfathomable that the government would not pay Social Security recipients or meet payroll of the American military. On any given day, however, Treasury would likely have to delay payments of some obligations. Depending on who the creditor is (a government contractor, veterans’ benefits, other social safety net payments, etc.), delayed payments would likely increase political pressure which would, in turn, increase the chances of reaching a debt ceiling deal, but would also be accompanied by some economic disruption and possibly a downgrade in the credit rating of U.S. government debt.

… because despite all the posturing, the US can and will prioritize debt and interest payments and avoid a technical default, even if it means that some 20 million deep state bureaucrats go unpaid for a week or two.”


Posted in Published | 2 Comments

May 23, 2023

2:48 pm

BKX appears to be in an irregular correction that may have further to go.  Despite poor fundamentals, BKX appears to be headed higher…for a time.  If so, BKX may venture to its April high of 85.95 before resuming its decline.  The debt ceiling impasse may have a positive effect on bank stocks.  It may be the Treasury refilling its coffers after the impasse is settled that will nail bank stocks due to rising interest rates.


2:35 pm

VIX has challenged the 50-day Moving Average at 18.85 on a trending strength day.  This lends further confirmation to the buy signal.  While trending strength may diminish over the Memorial Day holiday, it may pick up strength in the first full week of June, which purports to be an active month.  Meanwhile, traders are picking up nickels in front of a steam roller shorting the VIX.

ZeroHedge notes, “I mean seriously… make it stop, please!”

Nomura’s Charlie McElligott is worried that things are just a little too good to be true for traders currently.

Specifically, he highlights that the dangerous dance builds – as from a risk-adjusted basis, “Short Vol” is crushing even “Long Stock” in everything but QQQ / Nasdaq Long only, with the AI “manna from heaven” – as a lot of the Asset Manager complex looks at the SPX fully-valued here at 19x and is more than happy to keep Overwriting (while others Underwrite), and Systematic “Short Vol” prints.

Over the past two weeks a strategy of selling Daily 25-Delta Puts has a Sharpe Ratio of… wait for it… 34!

But… and it’s a big butt! The cross-asset strategist warns that this impossibly-smooth “Short Vol” return in recent weeks, this “smooth risk-adjusted return” path is indicative of asymmetry, fragility and instability.”


8:00 am

Good Morning!

NDX futures consolidated inside yesterday’s trading range as the markets await the FOMC announcement on Wednesday.  NDX is in a throw-over phase of its Ending Diagonal formation.  Once finished, the target is commonly the starting low in October.  An aggressive sell signal awaits investors beneath the August high at 13720.91.  The Cycle Top at 13594.16 provides confirmation.

Today’s op-ex shows Maximum investor Pain at 13800.00.  Long gamma starts at 13825.00.  Short gamma may start a t 13760.00,  but not a lot of conviction.

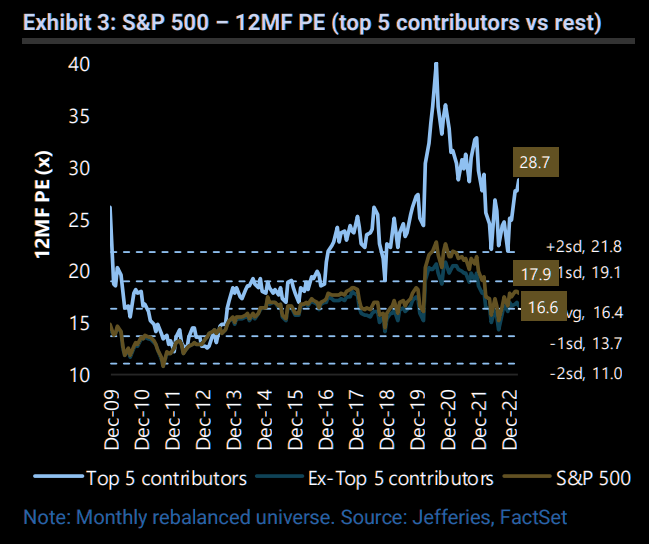
ZeroHedge comments, “Big five PE

Narrow and powerful…Jeff writes: “…29% of the stocks outperforming and the top five stocks driving 78% of S&P 500’s returns this year.”

Source: Jefferies

Lowest since 1999

The number of stocks outperforming the SPX has crashed formidably.


SPX futures are trading lower, but still within yesterday’s range.  Intermediate-term support is at 4129.30, beneath which an aggressive sell signal may be taken.  Friday May 19 remains the Master Cycle high in the SPX.

Today’s op-ex shows Max Pain at 4190.00.  Long gamma starts at 4215.00, while short gamma may begin at 4175.00.

ZeroHedge reports, “US equity futures are lower, as treasuries also dropped across the curve, with the two-year yield rising for an eighth day, after the latest round of talks between Joe Biden and Kevin McCarthy Monday ended without a deal, while Eurozone manufacturing activity shrank at the fastest pace since the pandemic shuttered factories three years ago, threatening to sap momentum from an economy driven by services. The dollar rose as did bitcoin, gold fell again while oil reversed earlier losses and jumped to session highs after Saudi Arabia’s energy minister told oil speculators to “watch out” just over a week before the OPEC+ alliance is due to meet.

At 7:45am ET, US equity futures dropped 0.2% to session lows, dropping back under  4,200, whlie the Nasdaq was shocking in the red perhaps finally realizing where the 10Y yield is. Lowe’s slipped 1.5% in pre-market trading after cutting its sales outlook. In Europe, a rout in luxury-goods makers including Hermes International and LVMH dragged the Stoxx 600 lower after Deutsche Bank AG analysts warned the sector is crowded and valuations are lofty. Tokyo’s Topix index fell for the first time in eight days, with semiconductor-related stocks turning lower on news that Japan’s tighter export controls will take effect July 23.”


VIX futures rose above the trendline at 17.60, giving a technical buy signal.  The Cycles Model shows increasing trending strength starting today.  The next phase may last through mid-June, but the final target may not come until the end of June.  Hedge when you can, not when you must.

Tomorrow’s op-ex shows only long gamma, starting at 17.00.  Currently, long conviction rises to 40.00.  Note; the June 21 conviction rises to 85.00.


TNX continues its rise above all resistance levels with the exception of the Cycle Top.  Trending Strength is rising, according to the Cycles Model.  Any pullback may only be a retest of supports as low at 36.00.  Meanwhile, the Cycles Model shows rising rates into early July.

Zerohedge remarks, “The White House and GOP negotiators plan to meet again Tuesday to continue negotiations on a months-long impasse over raising the nation’s $31.4 trillion debt ceiling before a default occurs.

Republicans say the White House isn’t negotiating in good faith, with House Financial Services Chair Patrick McHenry (R-NC) saying on Tuesday that he’s not sensing urgency from the White House – which waited months to arrive at the bargaining table at the 11th hour.

Rep. Garret Graves (R-LA), who authored the House GOP’s opening bid on permitting reform, says that Republicans and the White House are still ‘far apart’ on a deal.

After a Monday night meeting between President Biden and House Speaker Kevin McCarthy (R-CA) – their third meeting, failed to produce meaningful progress, White House aides headed back to Capitol Hill for further talks throughout the night.

House Appropriations Committee Chairwoman Kay Granger, a Republican, also suspended work on pending funding bills this week “to give the Speaker maximum flexibility as talks continue,” she said in a statement.

The lack of clear progress continued to weigh on Wall Street with U.S. stock indexes set to open lower Tuesday morning and global markets on edge. –Reuters

Meanwhile, the Treasury Department has asked federal agencies if they can delay payments, the Washington Post reports, citing two people familiar with the matter, as the Biden administration looks for ways to limp things along until a deal is struck – or June 15 quarterly tax payments roll in, buying Congress a bit more time to negotiate before the so-called “X-date” when reserves run dry.”


Posted in Published | Comments Off on May 23, 2023

May 22, 2023

8:00 am

Good Morning!

NDX futures declined to 13749.90, just above the trendline at 13720.91.  On Friday it made a new yearly high at 13874.42, on day 276 of the Master Cycle.  While the NDX may go as high as 14200.00, the Cycle is very stretched.  A decline beneath the trendline may constitute an aggressive sell signal.  Should a reversal occur, the NDX is due for a decline to the end of June.

Today’s options expiration shows Maximum Pain for options investors at 13790.00.  Long gamma begins at 13820.00, while short gamma starts at 13750.00, at the tip of the Ending Diagonal.

ZeroHedge remarks, “Nobody talks about this one

Majority of pundits are only talking about the big SPX spec short, but there are many offsetting positions, one of them the NASDAQ long…currently at rather long levels.

Source: DB

NASDAQ technicals

The break out has managed sucking people in. We continue to trade inside the trend channel. Note the 14k, give or take, is a big resistance area to watch.”


SPX futures have remained in a very narrow corridor between 4175.00 and 4197.00.  SPX managed to make a new 2023 high, but remained beneath the August peak.  The top of the trading channel is near 4220.00.  Intermediate-term support lies at 4127.30, where a potential aggressive sell signal lingers.  Although the probability of a new high was evident, the surprise came late in the day.

Today’s op-ex shows Max Pain at 4175.00.  Long gamma starts at 4200.00. while short gamma begins at 4150..00.

ZeroHedge reports, “US futures are flat as we start a new week and inch closer to the debt ceiling x-date: as a reminder, according to Janet Yellen the US could be in default in just 10 days. At 8:00am ET , S&P futures were up 0.1%, near session highs, after trading in a narrow range overnight; the tech-heavy Nasdaq was pressured by losses on semiconductor stocks after China said products from Micron Technology had failed a cybersecurity review. Micron shares dropped more than 5% in New York premarket trading, dragging down other chipmakers, including Nvidia and Qualcomm.  Asian markets are higher, while European stocks trade near session lows. Bond yields are higher, rebounding from session lows, while the USD is slightly in the green with commodities also erasing earlier losses. MegaCap Tech names are up slightly pre-market. McCarthy and Biden spoke on Sunday and will resume negotiations today. Fed’s Kashkari, a Fed dove turned hawk (and soon to turn dove again) is now open to holding rates steady in June; OIS now sees more than 80% odds of a pause at the June mtg. Biden expected ties with China to improve very shortly and considers lifting sanctions on Chinese Defense Minister.”


VIX futures rose to a weekend high at 17.43, approaching the trendline at 17.60.  Although the VIX may waver near the low, the correction appears complete.

ZeroHedge observes, “What happens when Ranges are broken? Finally some moves…

a. What is the client feedback in the last 48 hours as debt deal optimism increases? Who ya got?

  • I have been pinged more times in the past two days than all year. Clients are re-engaging and sentiment has dramatically improved. If there are positive headlines over the weekend, this rally has legs. Current short (low risk) positioning is not reflective of improving sentiment and a potential move higher.

b. Who is moving off the sidelines back into equities (said another way, was the equity demand real or covering related)?

  • S&P trading above $4200 Friday morning, which is the top end of the range. I think investors will continue to add risk next week if we see any positive developments over the weekend and the top of the range gets extended to $4300/$4400 to the topside.

c. What is client consensus and what does the consensus think about the consensus?

  • Bearish sentiment continues to wane. No one wants to be forced into the market, and that entry be the new top tick. This feels more orderly and buying the highest quality sustainable themes. The worst thing would be a correction shortly after the cover bid is completed.”


TNX may be beneath Friday’s peak, but it still appears on its way higher, adding strength along the way.  It is now above mid-Cycle support, giving it legs to go higher.  Trending strength may appear this week, but comes back in spades in mid-June.

ZeroHedge notes, “Negotiations in Washington DC over the debt ceiling have taken a big step back over the weekend, as the White House and House Republicans continue to point fingers at each other.

“It seems as though he wants default more than he wants a deal,” House Speaker Kevin McCarthy (R-CA) told Fox News on Sunday. “We have got 11 days to go,” McCarthy continued, urging Biden and the Democrats to be “sensible about this.”


USD futures took a small step back after its rally last week.  However, trending strength may arrive as early as today and may continue dominating for the next three weeks.
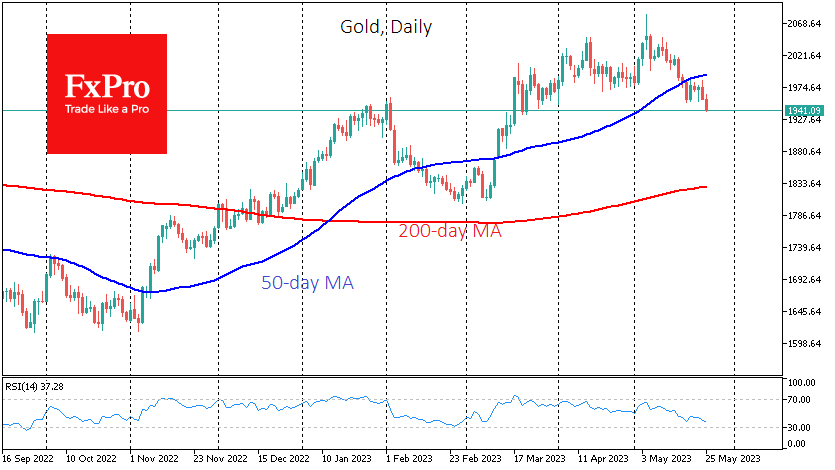
 

Gold futures may resume their decline after testing the 50-day Moving Average at 1988.74.  Gold is on a confirmed sell signal.  The Cycles Model suggests that the decline may continue through mid-June.  The next support level is the mid-Cycle support at 1836.69.  Don’t be surprised should it go there.


Posted in Published | Comments Off on May 22, 2023

May 19, 2023

3:02 pm

BKX also suffered a reversal  just beneath the 50-day Moving Average after an irregular correction.  We may see a panic decline over the next three weeks.  Note that TNX broke out this morning, signalling higher rates (and more bank losses).

ZeroHedge remarks, “Amid a major short-squeeze which has lifted the regional bank stocks almost 10% this week – the best week since Nov 2020 – CNN is reporting that during Thursday’s meeting with the CEOs of large banks, Treasury Secretary Janet Yellen told executives that more bank mergers may be necessary as the industry continues to navigate through a crisis, two people familiar with the matter told CNN.

Yellen echoed remarks from US regulators who have said there may be bank mergers in the current environment, one person familiar with the matter said.

Additionally, this is nothing new as during an interview with Reuters this week, Yellen said a certain degree of consolidation in the regional and mid-size banking sector could occur.

“This might be an environment in which we’re going to see more mergers, and you know, that’s something I think the regulators will be open to, if it occurs,” Yellen told Reuters.

Roughly translated that means expect more imminent bank failures.”


2:39 pm

SPX did not take long to make its reversal.  A close beneath 4160.00 may make it a Key Reversal.

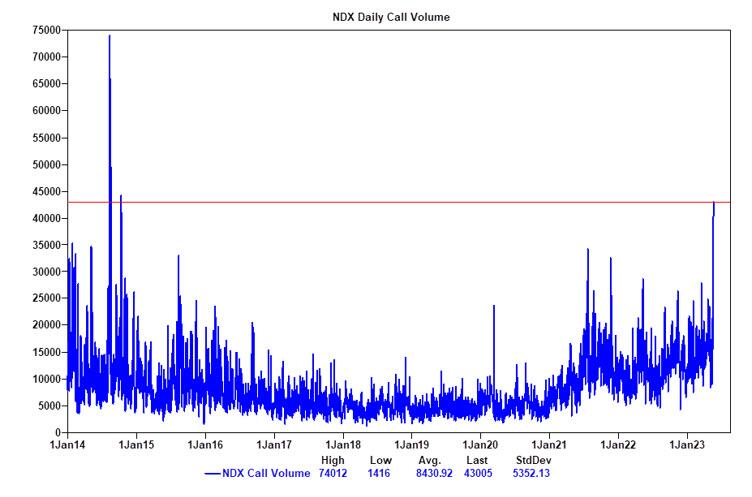
ZeroHedge notes, “As we discussed last night, Goldman’s Sales and Trading desk was bombarded on Thursday by clients eager to know what has been behind the recent meltup in tech stocks. In response, Goldman shared several explanations starting with the near record Nasdaq gamma squeeze which saw the most NDX call buying since 2014…

… as well as several other mostly technical catalysts:”


8:30 am

Good Morning!

NDX futures reached an overnight high at 13905.00, but have eased back to the flat line.  Should NDX go higher, today is day 276 of very stretched Master Cycle.  The August high and Cycle Top resistance have both been challenged.  The Cycles Model maintains that the next move may be a decline to the October low by the end of June.

Today’s op-ex shows Max Pain at 13660.00.  There is virtually no short gamma, while long gamma begins at 13700.00 and runs to 14000.00.  If options investors have their way, NDX would rise to 14000.00. today.

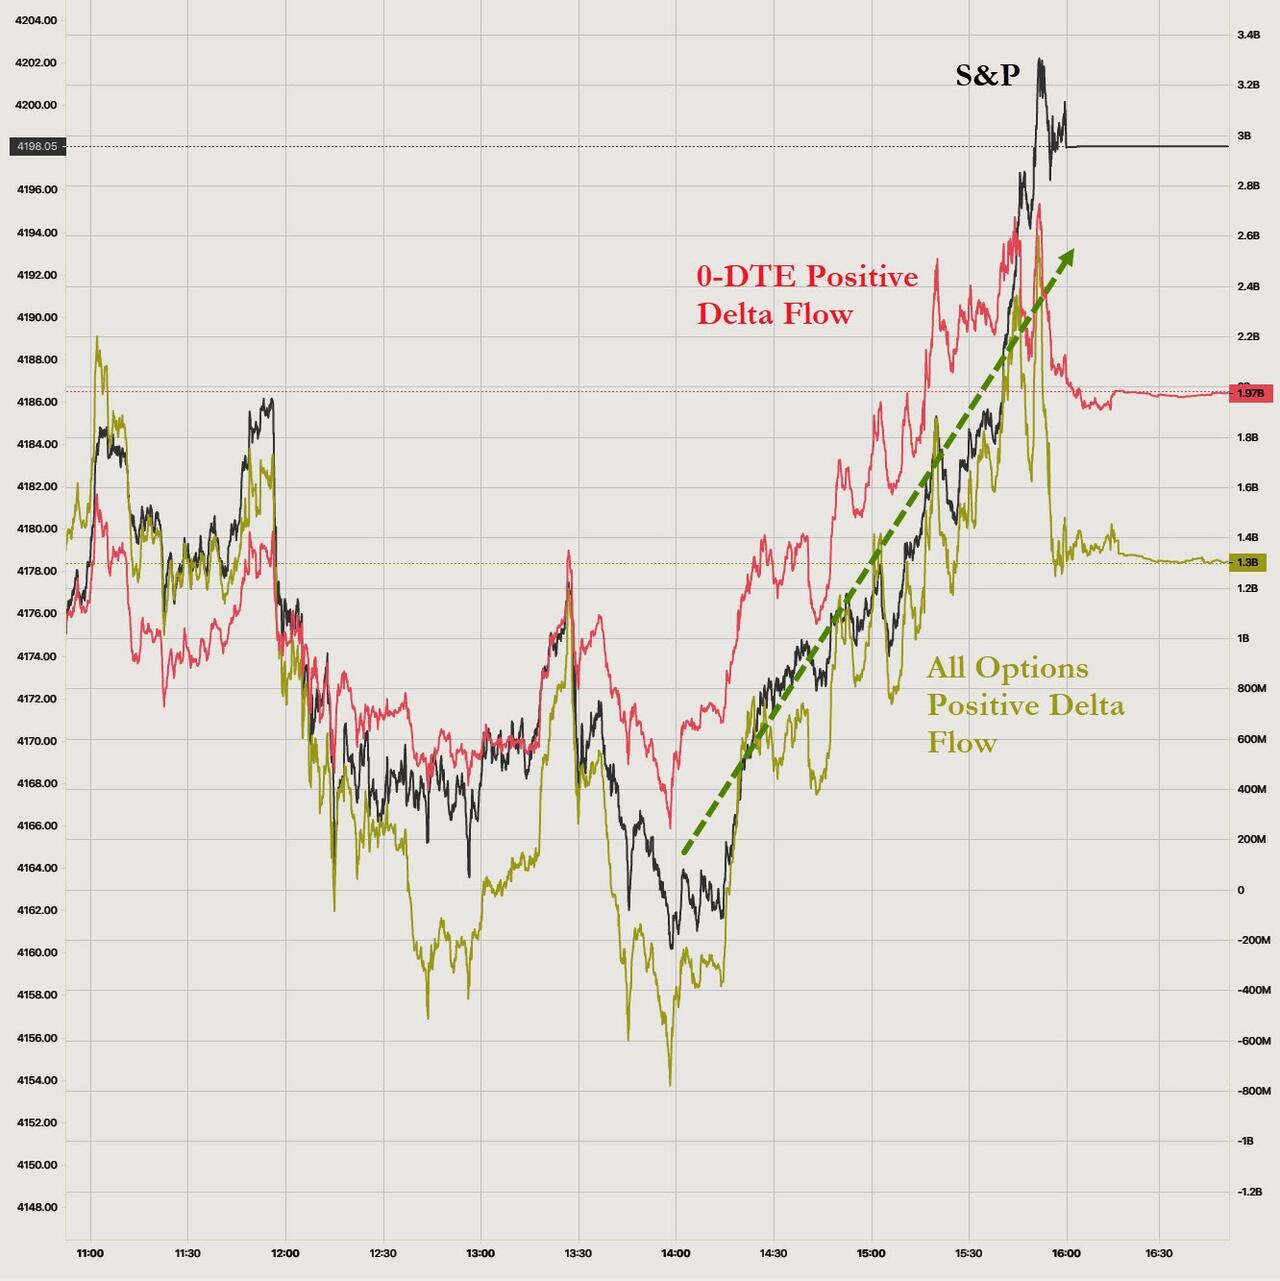
ZeroHedge remarks, “Today is one of those 12 days a year where 0-DTE and monthly OpEx are the same and despite the overwhelming strength from yesterday and Goldman noting that it is a relatively small expiry with a total of $1.7 trillion notional ($735bn of this is AM expiry, with the remaining $1trillion of this SPX pm + ETF + single stock), SpotGamma believes there are some reasons for concern.

But first, Goldman’s derivatives guru Brian Garrett sets the scene:

Dealers are long ATM and downside options, but short upside tail (we saw how powerful this can be yesterday into the bell!)…

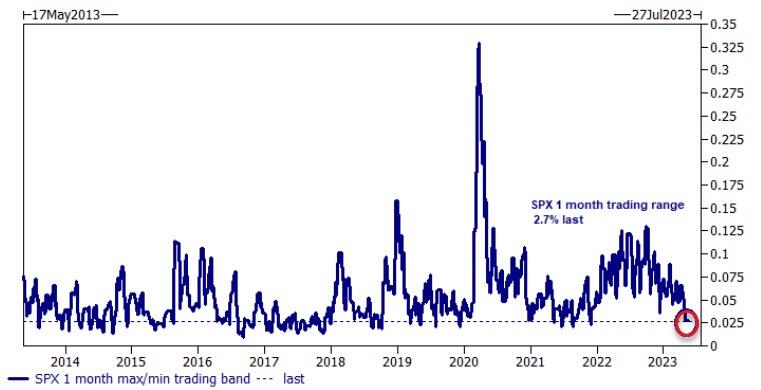
Also of note – for any breakout risk – the 1 month trading band hasn’t been this tight in years…

…historically, this level of “coiled spring” has a short lifespan… now it’s just a question of breakout or breakdown.”


SPX futures have reached an overnight high at 4214.00 and remain near the high thus far this morning.  Yesterday I mentioned the weekly mid-Cycle resistance at 4198.50.  Note the close was nearly spot-on.  Whether the SPX goes higher today or not, all the signs point to an imminent reversal with a decline to the end of June.

Today’s op-ex shows 4150.00 being hotly contested, with long gamma above running to 4300.00 and short gamma beneath it running to 4000.00.

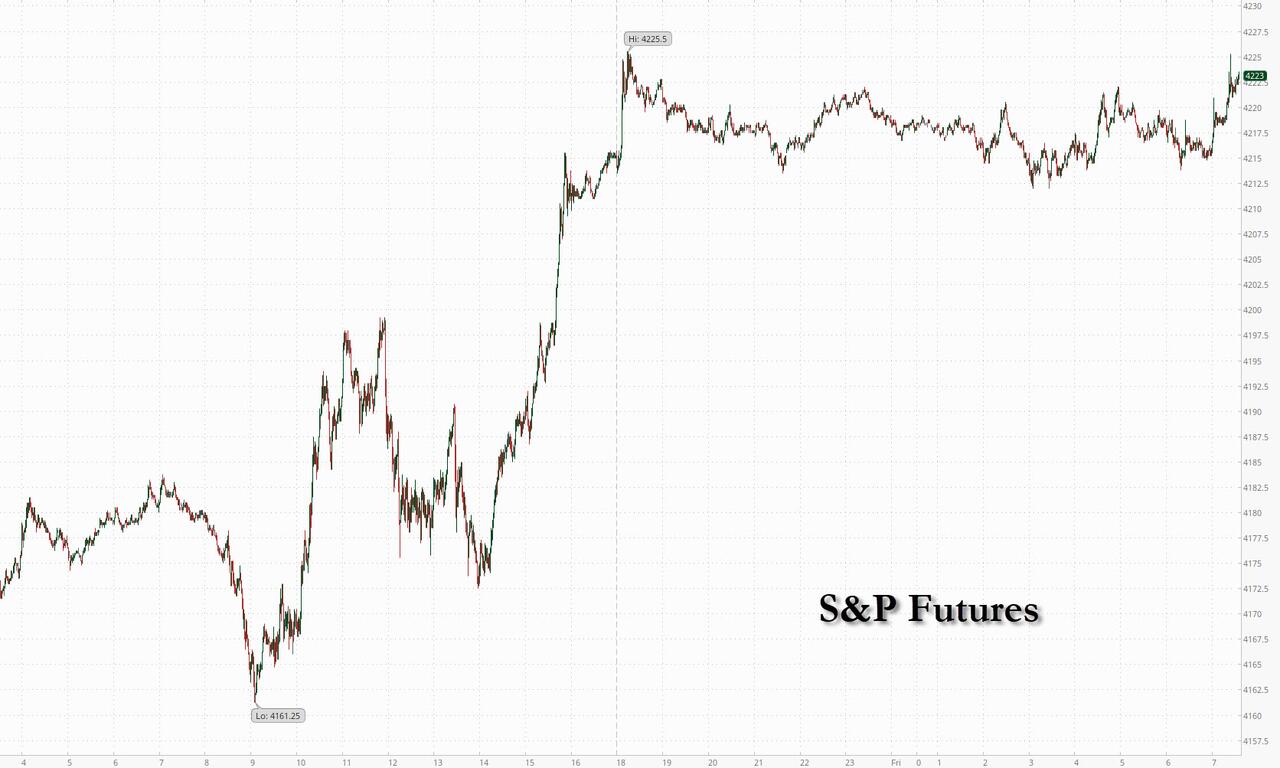
ZeroHedge reports, “After breaking out to new 2023 highs, US equity futures are up small (on “debt talk progress” even though there has been zero actual debt talk progress) ahead of Powell’s speech today, trading in a narrow 10 points. As of 730am ET, S&P futures are up 0.2% to 4,220 while Nasdaq futures are up 0.1%. European stocks are up 0.8%m near session highs with Germany’s DAX set for a record close for the first time since January 2022 while the Nikkei 225 closed at a 33-year peak, as momentum carried over from Wall Street.  Bond yields reversed earlier losses and hit session highs around 3.65% while dollars are weaker. Pre-market, megacap tech, where we just saw the biggest call buying since 2014, continues to drive higher amid yesterday’s rally. Commodities are mixed: oil is set to close its best week since mid-April while base metals are lagging. Macro calendar is quiet today with the major focus on Powell’s speech at a panel at 11am ET (Fed) where former chair Ben Bernanke will also be present. Keep an eye on the key 4200 level today.”


VIX futures made a new morning low at 15.86.  Despite that, the VIX is very tightly wound up at all degrees for a sizeable breakout .


TNX has clearly broken out above its April high and due to go higher.  Today is already showing strength and may be due for more.  The Cycles Model suggests that TNX may continue to rise until early July.  Powell’s highly anticipated speech at 11:00 am may give further impetus to the new trend.


Posted in Published | 1 Comment