The Lord’s Prayer
Our Father, who art in heaven, hallowed be thy name. Thy Kingdom come, Thy Will be done, on earth as it is in heaven. Give us this day our daily bread and forgive us our trespasses, as we forgive those who trespass against us. And lead us not into temptation, but deliver us from evil. Amen.
7:45 am

Good Morning!
SPX futures spent the overnight session pinballing between Intermediate resistance at 7378.00 and round number support at 7300.00. The correction may be complete after a retest of the low at 7237.85. Failing to go lower, the upsurge may resume. A test of the 52-day Moving Average is still possible, but fading fast. On June 3 I speculated that, should the SPX keep its former pace, it may achieve 7800.00 to 8100.00 by the end of June. That speculation may still be valid, despite this week’s correction. Today’s CPI may influence the outcome of today’s direction. A surge above resistance at 7384.00 may indicate the bounce may have legs.
Today’s options chain shows Max pain at 7400.00. Long gamma may strengthen above 74535.00 while short gamma lurks beneath 7375.00.
ZeroHedge reports, “Markets continue to trade with a risk-off bias this morning, with equity futures and macro credit weaker, rates selling across the curve, as the USD and oil sensitive currencies outperform.”

The premarket VIX is consolidating above the 52-day Moving Average at 19.52. The bounce may have run its course yesterday, allowing the VIX to test new lows by the end of the month. The target appears to be the lower Triangle trendline near 15.00. However, Month-end action may produce a tail beneath the trendline.

The US 10-year Bond Yield is testing the Cycle Top support at 45.25 this morning. A further rally from here may allow TNX to advance toward the neckline near 46.87, cementing the rising trend.
ZeroHedge remarks, “With expectations of a 4%-plus print, all eyes are on this morning’s CPI report as we move past April’s shutdown-related distortions.
Headline CPI rose 0.5% MoM (as expected) in May, lifting prices 4.2% YoY (also as expected). The first 4%-plus print since April 2023..”
Also reported by ZeroHedge,”With markets thrown in turmoil following Trump’s threat to restart war against Iran in retaliation for downing a US Apache helicopter, it wasn’t clear how today’s $58 billion 3 year auction would go. In the end, it wasn’t great, or terrible: a little tail, but besides that all metrics were relatively solid. ”

USD continues to consolidate, taking its cue from TNX. Normally a pullback may be warranted for a week or two after a Master Cycle high. However, pressure to go higher may limit the depth of a pullback.

Bitcoin has resumed its decline after a 8.56% correction. The Cycles Model suggests the following decline may be quite lively over the next two weeks. A probable target may be round number support at 50000.00. A decline to 45000.00 may be possible, but less likely.

Crude oil bounced after making a probable Master Cycle low at the Triangle trendline near 86.00 yesterday. Should this be correct, the Cycles Model suggests a rally to follow lasting to mid-August. A small tail shows in the chart. An alternate view is calling for a longer tail.
OilPrice.com observes, “India is scrambling to contain the economic and financial impact of the worst oil supply disruption in history as analysts say the high oil prices would continue to weigh on the Indian currency, economic growth, and public finances as long as supply is choked at the Strait of Hormuz.”
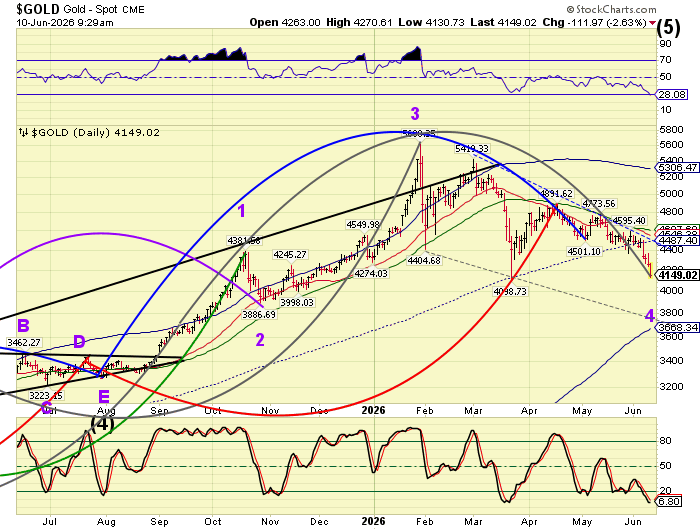
Gold is being sold heavily this morning as central banks are liquidating gold for oil. The selling may turn into a panic over the next few days with an extended target approaching the Cycle Bottom at 3668.29, should the decline last to the weekend. A breakdown beneath the March 23 low at 4098.75 may confirm this event.
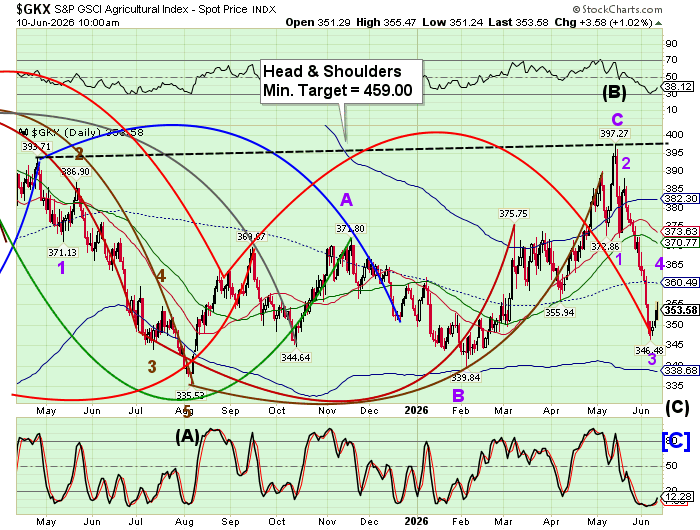
The Ag Index is bouncing off the June 5 master Cycle low. Its target may be the mid-Cycle resistance at 360.49 by the end of the week. Should it do so, a reversal may occur, allowing the Ag Index to resume its decline to, or beneath, the Cycle Bottom at 338.68 by the end of June. Harvest season begins in July, which may bring in estimates of the 2026 crops.
ZeroHedge remarks, “The good news for US farmers is that urea fertilizer prices have returned to pre-US-Iran conflict levels after spiking from late February through mid-April. This is great news for farmers, though they are not out of the woods, as drought continues to plague some of the nation’s top agricultural belts.”