The Lord’s Prayer
Our Father, who art in heaven, hallowed be thy name. Thy Kingdom come, Thy Will be done, on earth as it is in heaven. Give us this day our daily bread and forgive us our trespasses, as we forgive those who trespass against us. And lead us not into temptation, but deliver us from evil. Amen
8:30 am
Good Morning!
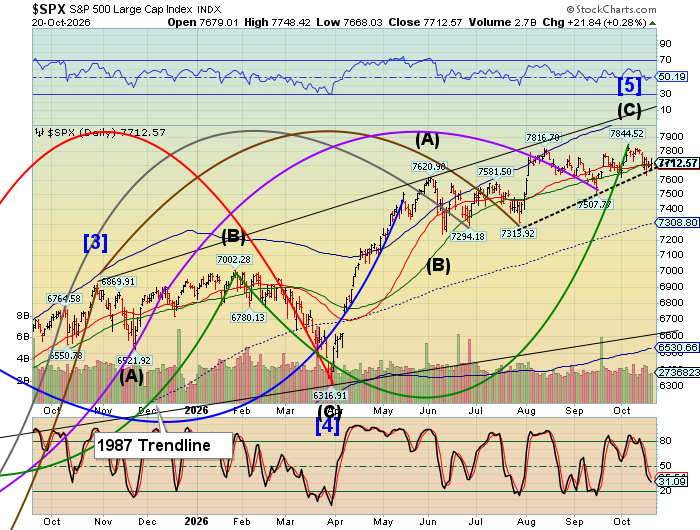
SPX futures rose to 7751.10 this morning, near the 61.8% Fibonacci retracement at 7762.42. A retracement may go higher, all the way to, but not exceeding, the top tick at 7844.52. However, most retracements fall within the confines of the Fibonacci gradients. The Cycles Model infers a rise in volatility later this week, usually associated with a breakout or breakdown. So the market is trying to decide whether to go higher (to challenge the top) or lower. Hedge funds have reduced their exposure while retail investors are buying at a rate not seen since 2017. Corporate buybacks are due to resume next week. The breaking point on the downside is the Diagonal trendline at 7675.00 today.
Zerohedge reports, “US futures are higher as blowout results from SpaceX and a monster preannouncement from Super Micro gave the battered AI trade a reason to bounce, while Elon Musk’s open endorsement of a SpaceX-Tesla merger added to the buzz…”
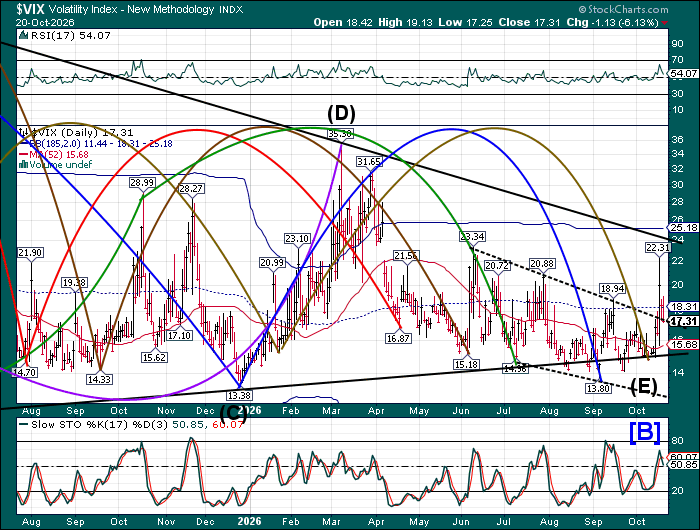
The premarket VIX is challenging its prior trading channel trendline at 17.31 this morning. The Cycles Model anticipates a possible reversal later this morning. Should that happen, the VIX may begin to rise toward the upper Triangle trendline, near 24.00. A breakout may be universally recognized as it approaches the Cycle Toop at 25.18.
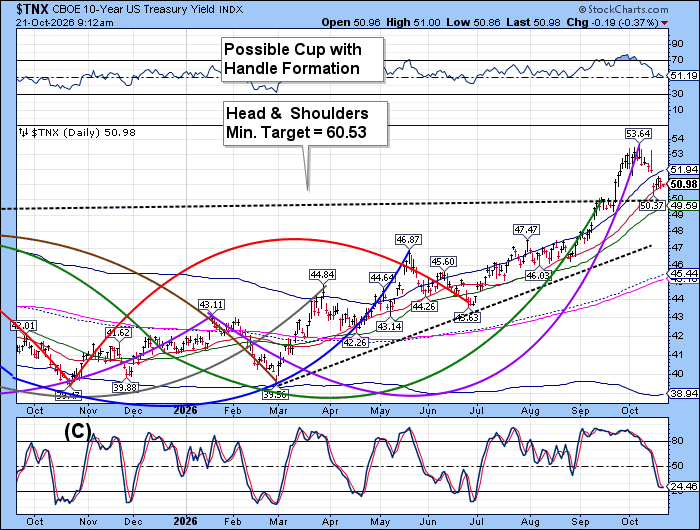
The US 10-year Bond Yield continues to climb up the rising Inttermediate support at 50.95 this morning. There; may be a slight risk of falling back toward the 52-day Moving Average at 49.59. However, the retracment fractal may be complete at the low of 50.37. That comment is brought forward by an indication of a possible minor Cycle low this weekend.
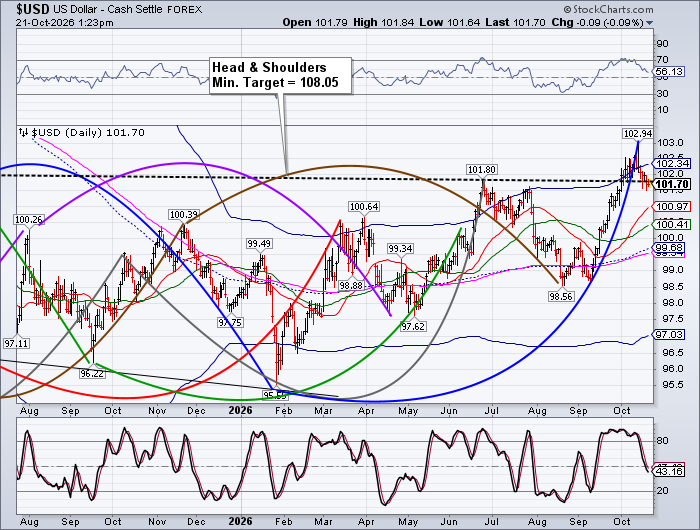
The US Dollar is hovering beneath the Head & Shoulders neckline at 101.80. It, too may be in a minor Cycle low this week. A rise above the neckline at 101.80 may signal a reversal may be underway, offering an aggressive buy signal. The buy signal may be confirmed on a rally above the Cycle Top at 102.34. The USD may gain volatility near the end of the month.
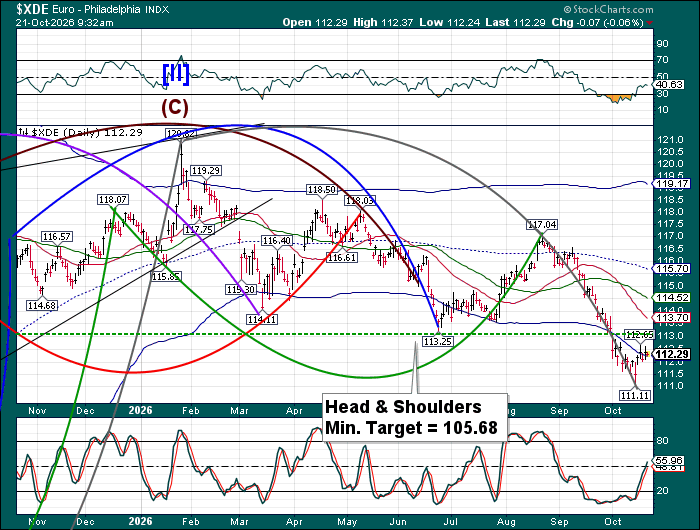
The Euro may be attempting to maintain support at the Cycle Bottom at 112.22. However, should it lose that support a sell signal may be used. The potential for a free-fall in the Euro may arise next week that may last to the end of November.
ZeroHedge remarks, “France’s accelerating death spiral, amid social unrest by far-left groups, political gridlock, and deteriorating public finances as the welfare state teeters on the brink of implosion, comes just six months before a presidential election that has only given polling tailwinds to right-wing candidate Marine Le Pen.”
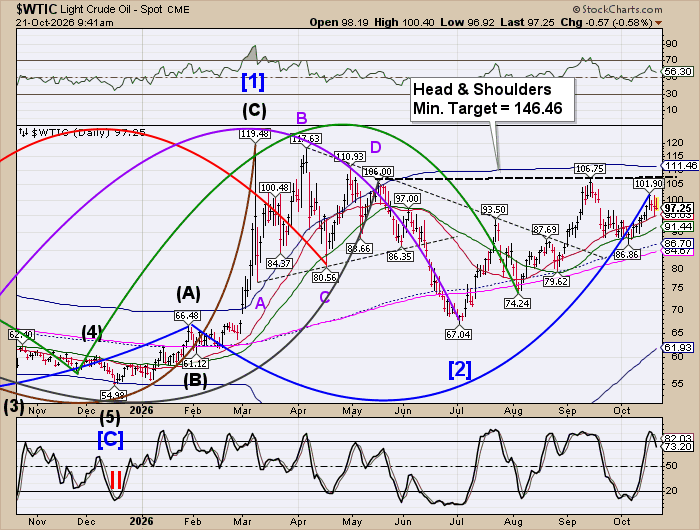
Crude oil may be corrcting its recent rally with a decline to te 52-day Moving Average at 91.44. An alternative may be a sideways consolidation over the next week as WTI burns off its overbought condition. Volatility may pick up near the end of the month.
ZeroHedge observes, “OSINT X accounts will soon cover the first Russian tanker carrying diesel for the US market, following President Trump’s deal with Moscow to supply the US amid a global refining crisis sparked by Ukraine hitting Russian energy assets and ongoing disruptions in the Strait of Hormuz.”
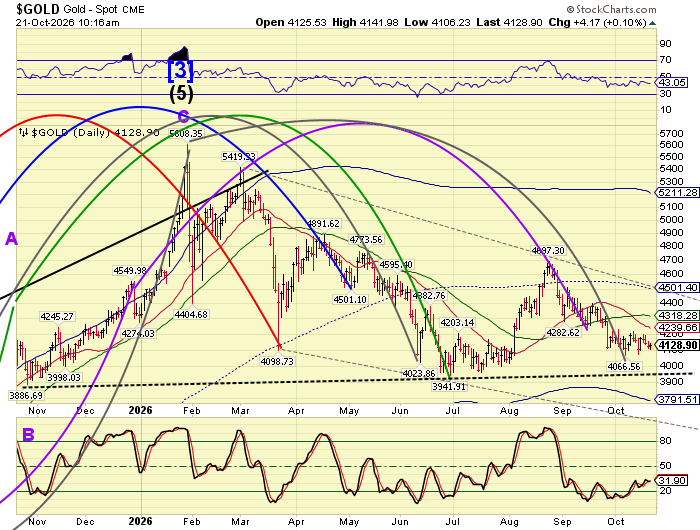
Gold continues its consolidation beneath major resistance at 4239.66 and above a trendline near 3950.00. The consolidation may resolve itself by the weekend. Volatility may spike next week. The trend remains “down” until further notice.
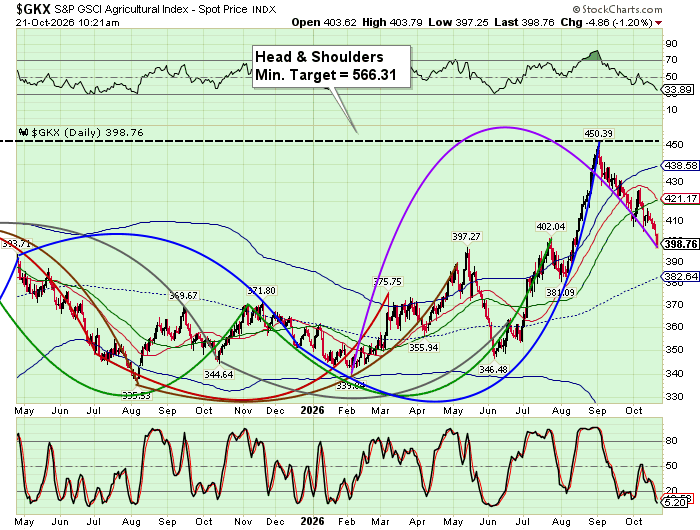
The Agriculture Index may have made its final low in its current Master Cycle this morning. A reversal may be imminent. The new master Cycle may challenge the Head & Shoulders neckline at 450.39 by the end of October. Harvest is still underway.
ZeroHedge quips, “Wheat futures just touched a two-month low, which for some is a sign the food-inflation scare of the summer has come and gone. Goldman disagrees.”